


EN
Vail Resorts (MTN) Could Be 7% Above Fair Value Following Proxy Fight Escalation
Vail Resorts (MTN) is in a full proxy fight after Oasis Management escalated its activist campaign, filing definitive proxy materials, nominating two directors, and issuing a critical letter that spotlights governance and operational concerns.
Against this backdrop, Vail Resorts’ recent share price momentum has been positive, with a 7 day share price return of 4.45% and a 30 day share price return of 9.62%. However, the 5 year total shareholder return is down 43.95% and the 3 year total shareholder return is down 15.61%. This leaves the current US$158.59 share price and 14.63% 1 year total shareholder return looking more like a rebound under scrutiny from activists than a clean bill of long term health.
Spot fresh ideas before the next proxy fight hits your watchlist by scanning our hand picked 19 high quality undiscovered gems featuring strong fundamentals and under the radar stories.For Vail Resorts, a 1 year total return of 14.63% after a 5 year decline of 43.95% raises a simple question: Is this bounce telling you the business has turned a corner, or just that sentiment has swung?
Most Popular Narrative: 7% Overvalued
Compared with the narrative fair value of $148.36, Vail Resorts at $158.59 is priced higher. This aligns with a story that already incorporates resilience, capital spending and dividends.
Ongoing pressure from activists and other external critics around governance, portfolio structure and investment pacing, including proposals for potential asset sales and capital allocation changes, could lead to decisions that reshape the balance between capital spending, free cash flow and earnings.
See why 12 investors see Vail Resorts as 7% overvalued.
Result: Fair Value of $148.36 (OVERVALUED)
Still, the narrative can crack if visitation softness around Epic pass trends persists, or if activist driven changes disrupt Vail Resorts’ capital plans and cash flow.
Find out about the key risks to this Vail Resorts narrative.
Another View on Vail Resorts Valuation
The first story presents Vail Resorts as 7% overvalued versus a fair value of $148.36. A different lens presents another perspective. Our DCF model puts future cash flow value at $234.95 per share, with MTN trading at $158.59, which screens as undervalued. Which signal do you rely on more: sentiment or cash flows?
For investors who want to see how that cash flow math is built line by line, it is worth spending time with the SWS DCF model itself, not just the headline number. Look into how the SWS DCF model arrives at its fair value.
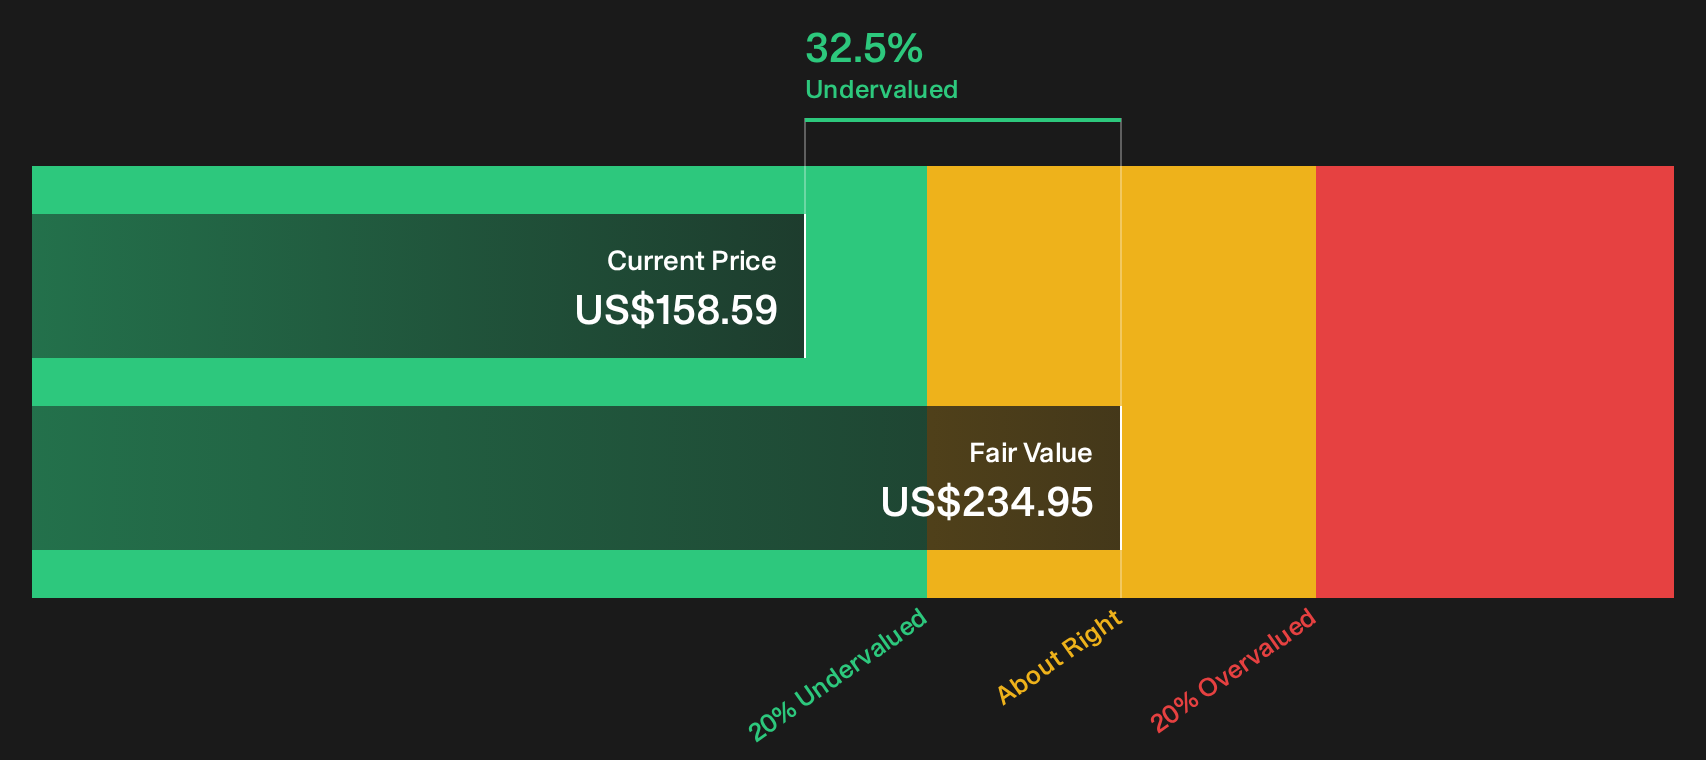
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vail Resorts for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
It remains uncertain whether the latest Vail Resorts moves reflect genuine improvement or simply a change in sentiment around activism and valuation signals. Consider acting promptly and weighing both sides of the story by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vail Resorts?
If Vail Resorts has you rethinking what belongs in your portfolio, do not stop here. Fresh opportunities often show up where the crowd is not yet looking.
- Target potential bargains early by scanning companies that combine quality metrics with beaten down valuations through the 39 high quality undervalued stocks.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (24 results) before the next bout of volatility tests weaker businesses.
- Keep risk in check by filtering for a 29 resilient stocks with low risk scores that may fit more conservative return targets without stretching your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com