


EN
Ouster (OUST) Lifted Guidance And Launched ZED Box 2, Is The Discount Warranted?
Ouster (OUST) has just paired a fresh third quarter report with new guidance and a robotics product launch, giving investors a dense cluster of data points to assess the stock.
The recent guidance update and ZED Box 2 launch arrive after a sharp 1-day share price return of 14.01% and a 7-day share price return of 17.00%, even though the 30-day and 90-day share price returns declined 16.50% and 19.83% respectively. That pattern points to fresh momentum building around Ouster in the short term, while the 48.89% year to date share price return and very large 3-year total shareholder return indicate a story that has already rewarded investors willing to tolerate past volatility.
Scan beyond Ouster and see how other robotics and AI hardware plays are lining up in our hand picked list of 52 AI infrastructure stocks.
After a sharp rebound and a roughly 41% discount to analyst targets, Ouster now sits between optimism and caution. Is the gap a genuine mispricing, or a fair reflection of risk as losses continue?
Most Popular Narrative: 41% Undervalued
Against a last close of $34.80, the most followed Ouster narrative anchors fair value at $59.40, putting a wide gap between price and story and tying that gap directly to how far the physical AI platform can scale.
Ouster's efforts to build a full physical AI platform through the integration of Stereolabs cameras, ZED Box 2 edge AI compute and expanded BlueCity and Gemini software, supported by lidar capacity that can ultimately exceed 100,000 units per year and a cash balance above US$450 million with no debt, give it room to pursue multi year contracts that can affect revenue scale and earnings power.
See why 90 investors see Ouster as 41% undervalued.
Result: Fair Value of $59.40 (UNDERVALUED)
Still, this bullish Ouster setup can fray quickly if higher operating costs persist while losses continue, or if further equity raises dilute shareholders again.
Find out about the key risks to this Ouster narrative.
Another View: Ouster Through The P/S Lens
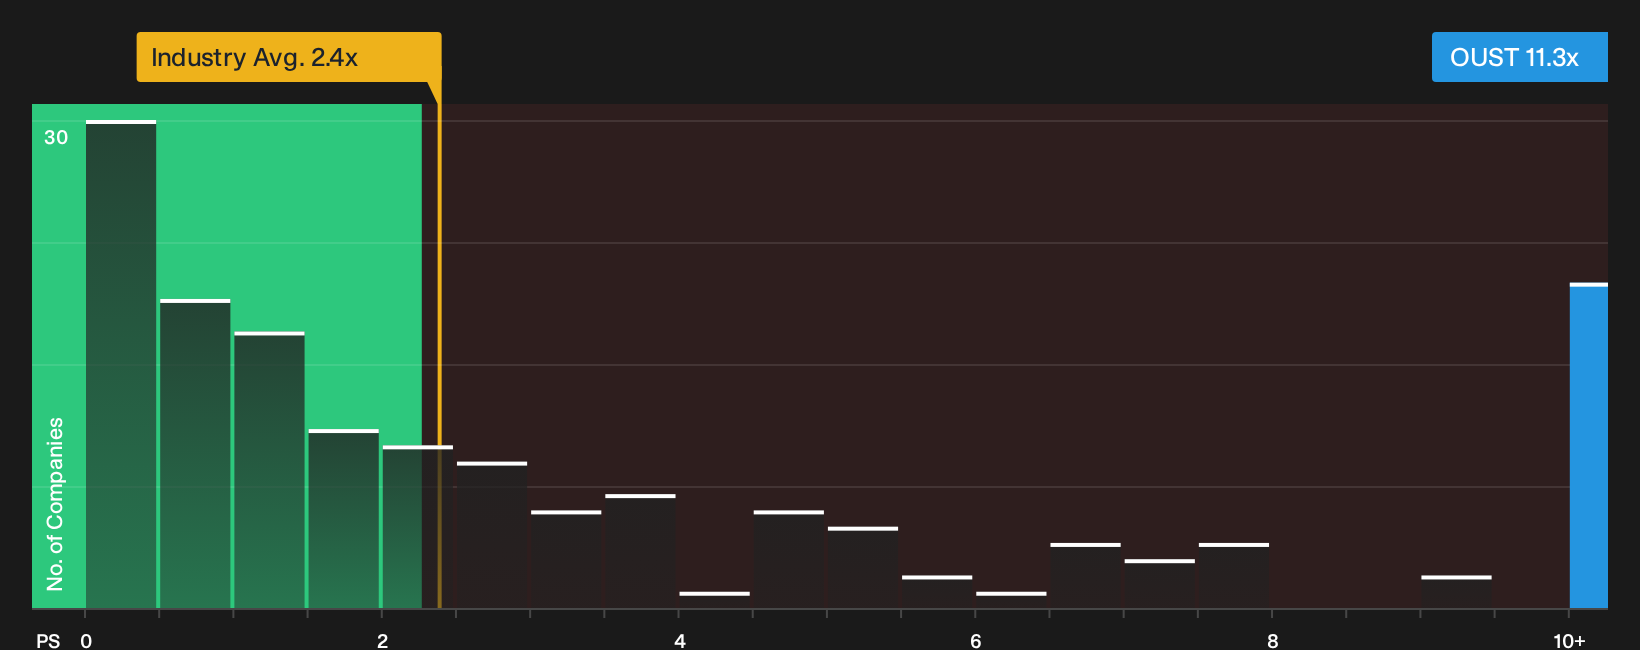
The story looks very different when you step away from fair value narratives and focus on what investors are actually paying for Ouster’s revenue. At a P/S of 11.3x, the stock is priced far above the US Electronic industry at 2.4x and the peer average at 3.9x.
The fair ratio model points to a P/S closer to 4.6x as a level the market could move toward over time. This leaves today’s pricing looking rich rather than cheap. For anyone weighing the bullish physical AI thesis against this premium tag, the key question is whether the growth case truly earns that spread.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
See something different in this mix of enthusiasm and concern around Ouster and want to move fast while sentiment is shifting? Weigh both angles by checking the 3 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Ouster?
If the Ouster story has sharpened your thinking, do not stop here. Broaden your watchlist and let fresh ideas compete for your capital.
- Target fast growing underappreciated businesses by scanning the 39 high quality undervalued stocks to find companies that pair stronger fundamentals with prices that lag the underlying potential.
- Lock in income focused ideas with the 8 dividend fortresses to see higher yield payouts supported by balance sheets you can scrutinize in one place.
- Prioritize resilience first by reviewing the 29 resilient stocks with low risk scores to identify companies with steadier risk profiles when you want fewer surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com