


EN
Did Record Jet Orders Just Shift Boeing's (BA) Investment Narrative?
- Avolon has completed a record purchase of 140 Boeing 737-10 jets, while IAT Leasing has agreed to expand its Boeing-based freighter fleet with a 767-300 Boeing Converted Freighter and options for two more aircraft.
- Boeing reported continued losses per share in Q3 2026 even as its commercial backlog and defense orders grew, which highlights the tension between strong demand and ongoing production and profitability pressures.
- We will now examine how Boeing's investment narrative is shaped by record 737-10 orders, along with production stability that is not anticipated until 2027.
Boeing Investment Narrative Recap
To own Boeing today, an investor needs to believe the commercial recovery can outpace its problem list. The core bet is simple. Strong demand and a record 737 order book eventually flow through a more stable 737 production system and turn a still pressured commercial unit into a consistent cash generator.
The short term swing factor is execution on 737 output and quality, which management does not expect to fully stabilize until 2027. Avolon’s record 737 10 deal supports long term utilization of that line but does not fix near term bottlenecks or high debt. The biggest risk remains fresh delays or cost overruns that drag on cash and margins.
The Avolon order for 140 737 10s is the clearest operational data point tied to this catalyst. It reinforces that lessors and airlines are committing to larger single aisle aircraft, with the 737 family already representing about 30% of all financed jets and more than 1,450 737 MAX units ordered by lessors overall.
For a shareholder, that contract helps frame the debate. The backlog and 737 10 per seat economics look supportive for longer term volume and pricing power, while the near term story still hinges on certifying variants, smoothing the supply chain, and using that order book to work down a sizeable debt load without further operational shocks.
Boeing's current analyst roadmap points to forecast revenues of US$125.6b and earnings of US$7.9b by 2029. That profile incorporates revenue growth of 10.9% per year and an increase in earnings of US$6.0b from US$1.9b today.
Uncover why Boeing's fair value indicates a 40% potential upside to its current price, which could be realized more quickly than many investors expect.
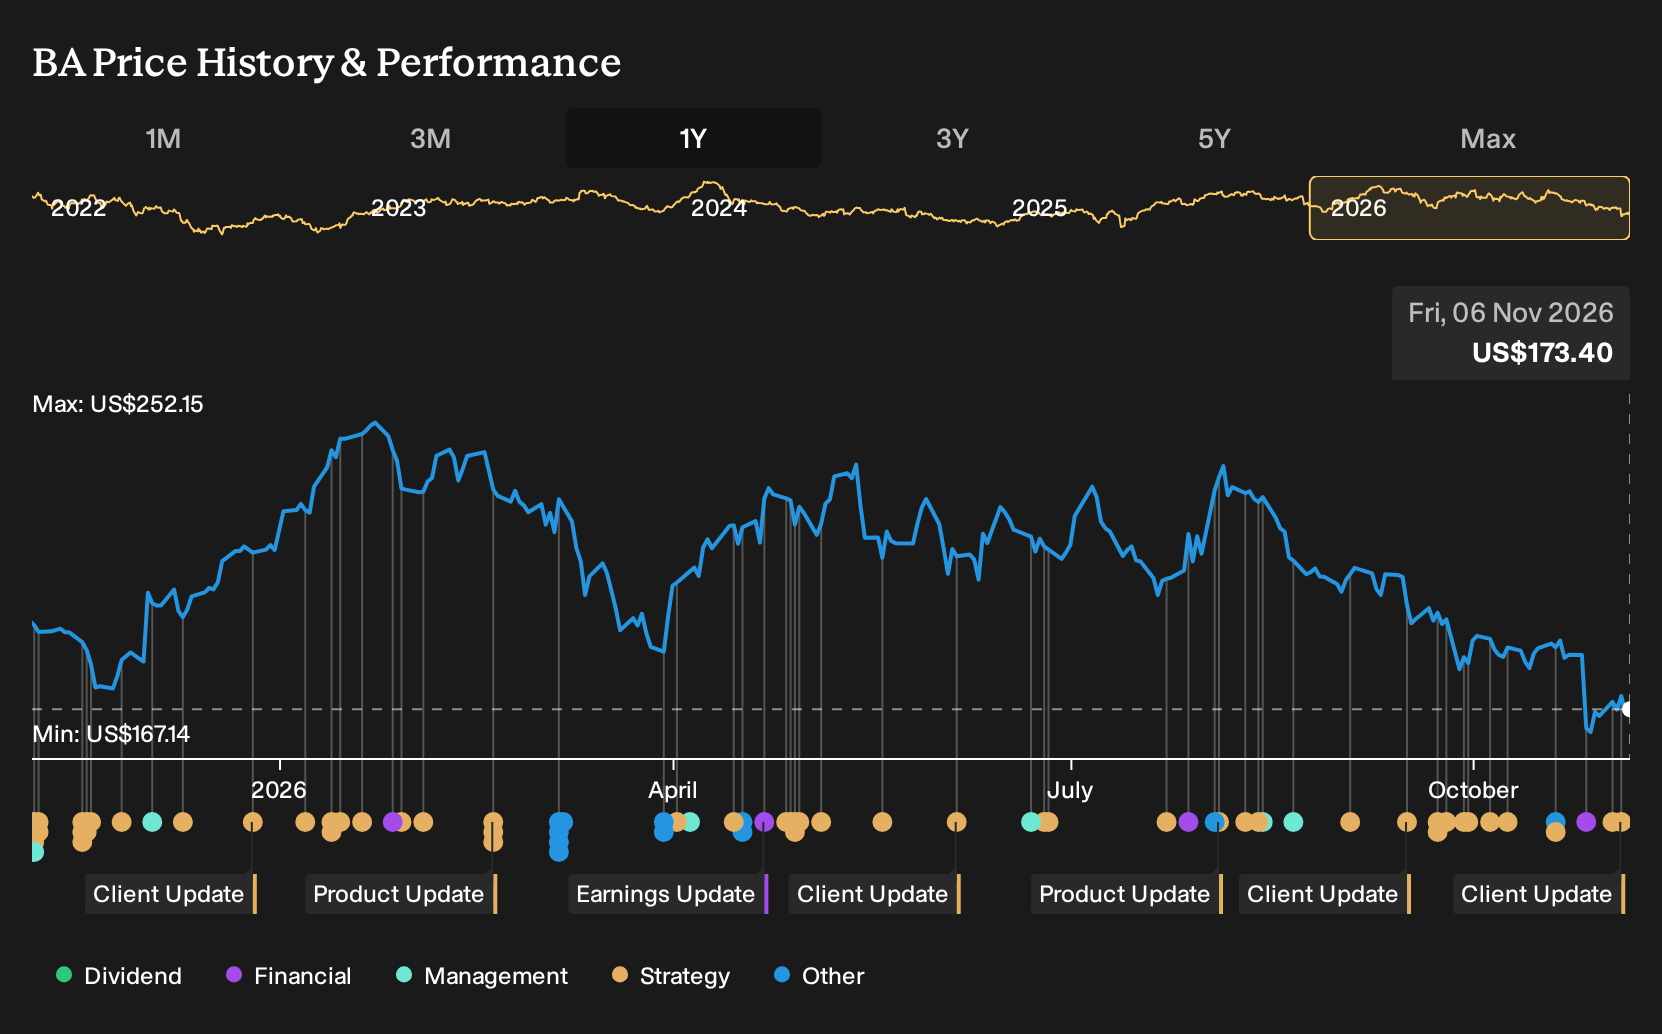
Exploring Other Perspectives
One bullish twist you might explore is the backlog story. The most optimistic Boeing analysts were already penciling in about US$142.2b of revenue and US$10.4b of earnings by 2029 before this Avolon order hit the tape. You can treat that as a stretched upside case and then decide whether fresh 737 10 demand nudges that narrative higher or not.
Explore 6 other Boeing fair value estimates, including one that suggests as much as 113% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Boeing research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Boeing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Boeing's overall financial profile at a glance.
Looking for more Boeing investment ideas and beyond?
If you want to put Boeing in context and build a wider watchlist, the Simply Wall St Screener can help you surface other stocks that fit your risk profile and return goals in a structured way.
- For potential value opportunities with quality fundamentals, review a curated 39 high quality undervalued stocks that may complement or contrast your view on Boeing.
- If capital resilience is a priority, filter for companies with robust finances using the list of solid balance sheet and fundamentals (24 results) and see how they stack up next to large aerospace exposures.
- To widen the opportunity set beyond widely followed large caps, cast a wider net across a 19 high quality undiscovered gems that might offer different risk and return profiles to Boeing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com