


EN
Is Enerflex (TSX:EFX) A Bargain Following Stronger Earnings And A Dividend Increase?
Enerflex (TSX:EFX) just reported new financial results. Third quarter sales were US$623 million, with net income of US$55 million and earnings per share of US$0.45 from continuing operations.
Enerflex shares have pulled back sharply in the short term, with a 7 day share price return down 16.9% and a 30 day share price return down 18.8%. This is occurring even though the year to date share price return is 25.6% and the 3 year total shareholder return is very large, suggesting recent momentum has cooled while longer term holders have still seen strong gains.
Scan how Enerflex compares with other energy infrastructure plays by reviewing the hand-picked 42 power grid technology and infrastructure stocks now catching investors' attention after earnings season moves.
The recent slide in Enerflex looks sharp next to rising earnings per share and a higher dividend. Is this a rethink of the business, or just sentiment resetting the price tag ahead of a valuation check?
Most Popular Narrative: 39% Undervalued
On the numbers in front of investors today, Enerflex is trading at CA$27.45 against a widely followed narrative fair value of CA$45. This frames the recent share price pullback as a debate over how much of the long dated project pipeline will actually turn into durable earnings.
Expansion into data center and AI power generation projects, including a 1.5 gigawatt opportunity set and new U.S. data center contracts with deliveries into 2027, increases reliance on a relatively new and competitive end market. Any shift in hyperscaler or developer plans could affect backlog conversion, revenue visibility and earnings stability.
See why 1 investors see Enerflex as 39% undervalued.
Result: Fair Value of CA$45 (UNDERVALUED)
Still, Enerflex’s heavy reliance on long lead time gas infrastructure and concentrated data center power projects could quickly challenge that undervalued thesis if execution slips.
Find out about the key risks to this Enerflex narrative.
Another View On Enerflex’s Valuation
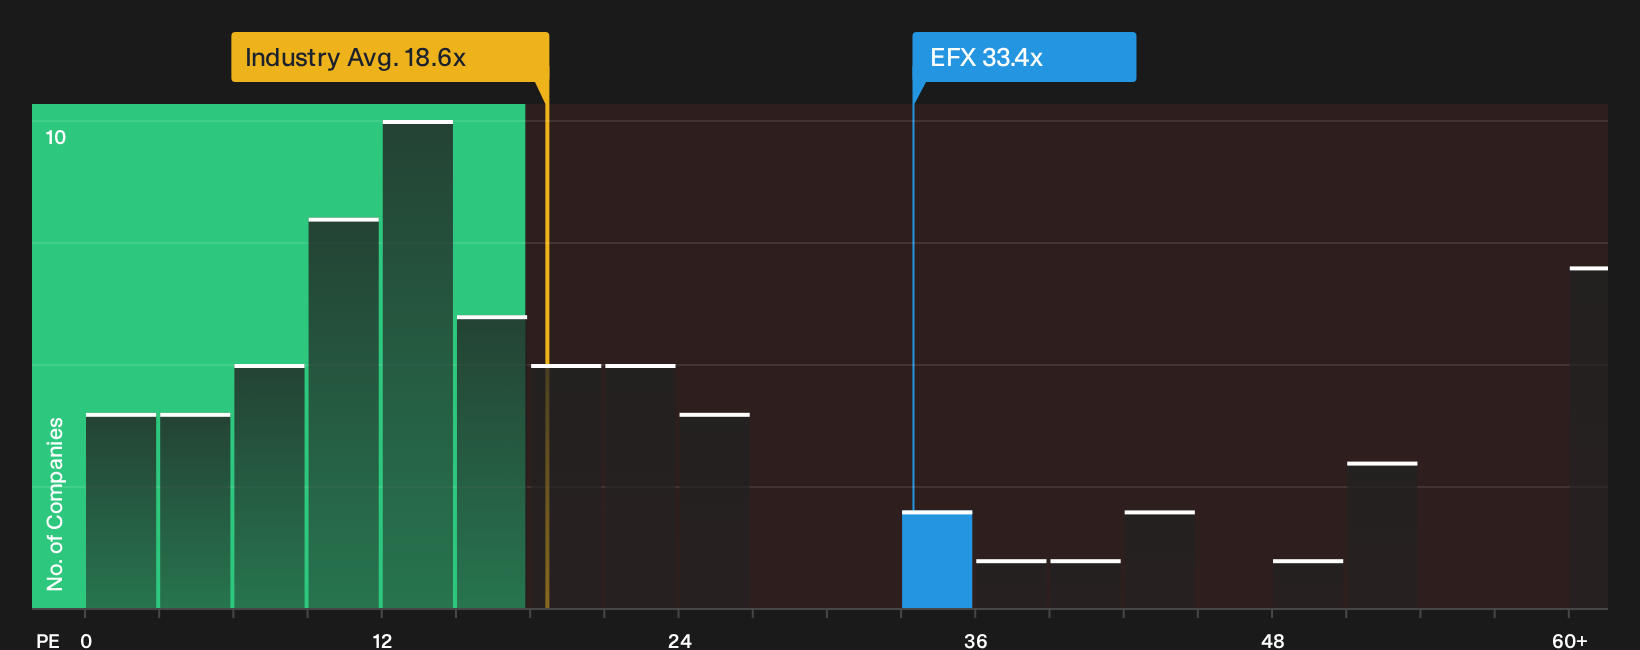
The story shifts when price is compared with earnings. Enerflex trades on a P/E of 33.4x, while peers in the North American Energy Services group sit near 17.8x, and the fair ratio points closer to 20.6x. That gap suggests investors are paying up, so how comfortable are you with that premium?
For a closer look at how these earnings multiples stack up against what the numbers imply as a fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure whether this recent Enerflex pullback reflects real concern or just short term noise, especially with both risks and rewards in play. Act quickly and weigh the full mix of concerns and upside potential by reviewing the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Enerflex?
If Enerflex has your attention, now is a smart moment to scan a wider field of opportunities so you are not relying on a single story.
Use the Simply Wall St screener to pressure test your watchlist against other stocks that match different return and risk profiles.
- Target stronger balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (5 results) that combine financial resilience with room for management to make disciplined capital decisions.
- Hunt for mispriced potential by checking the 7 high quality undiscovered gems where solid fundamentals have not yet attracted broad market attention.
- Dial down portfolio volatility by focusing on the 9 resilient stocks with low risk scores which concentrates on businesses with lower risk scores and steadier financial characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com