


EN
Vericel (VCEL) Stock May Trade At A Premium Following Raised Revenue Guidance
Vericel has delivered strong share price gains in recent years, and with the stock now around US$54.62, the key question is whether that move can be explained by its earnings power. With so much of the story tied to how profit scales from its burn and cartilage repair therapies, the current price sets a clear test for what the business is actually earning today.
- Over the past 3 years the stock has returned 61.1%, which puts real pressure on the current earnings base to carry the heavier expectations now embedded in the valuation.
- Recent profit growth alongside higher full year revenue and margin expectations can support a case that earnings may be starting to catch up with the share price, but only if that improvement proves durable.
- Your read on Vericel is one view; the desks covering it have another. See what analysts think Vericel's shares could be worth.
The issue now is whether Vericel's recent earnings justify the valuation that investors are paying for the stock today.
If you want to test the same earnings question that Vericel now faces across a wider set of companies, take a look at 39 high quality undervalued stocks.
Is Vericel Getting Expensive on Earnings?
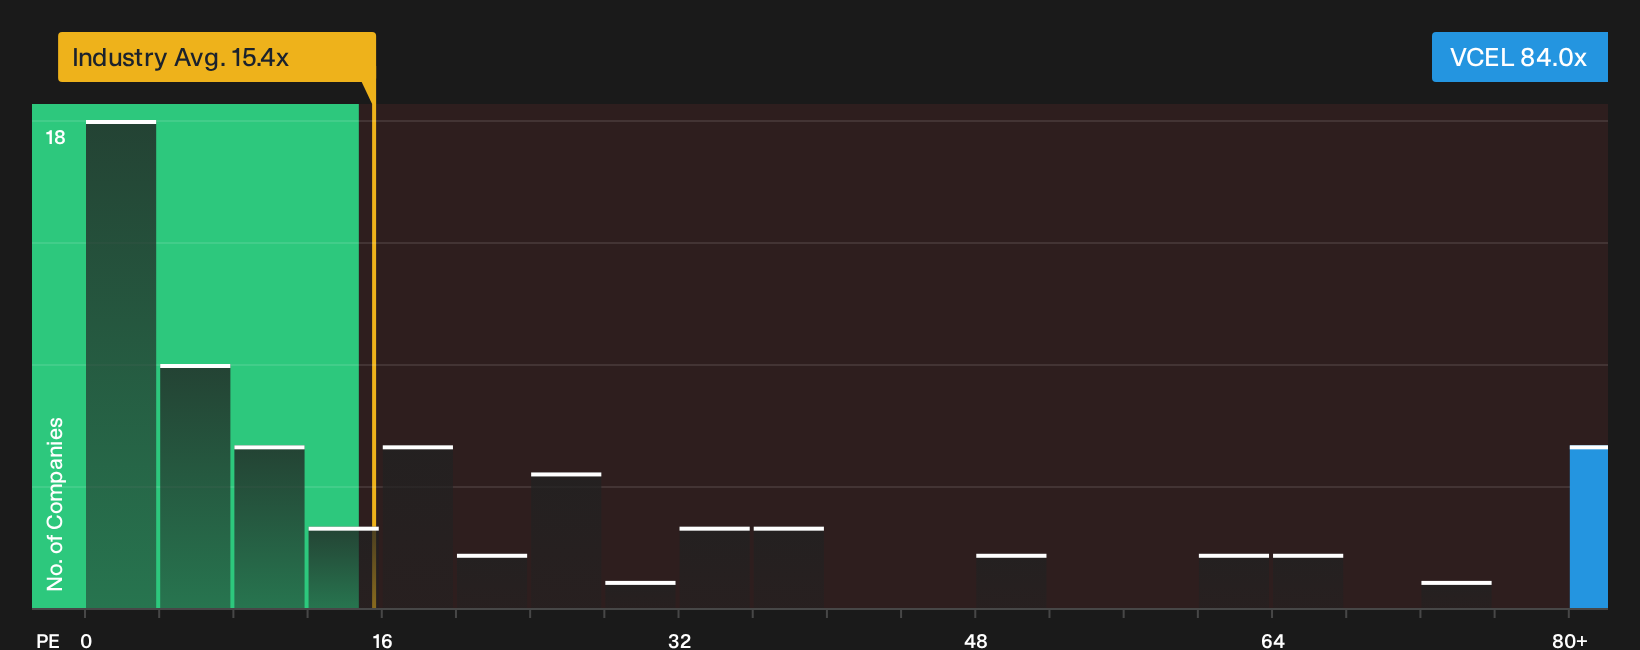
P/E fits Vericel quite well because investors are currently focused on the earnings power behind its commercial therapies. On this metric, the stock trades at about 84.0x, compared with roughly 15.4x for the wider biotechs industry and around 8.7x for similar peers. As a result, the market is putting a far richer tag on each dollar of profit than is typical in the sector.
The fair multiple that a tailored model suggests for Vericel, which factors in growth, margins, size and risk, comes in far lower than where the shares are priced. That gap is large enough that the model reads less like a precise target and more like a warning flag that the stock screens as overvalued on earnings. Because the strong Q3 2026 update lifted guidance and pushed the share price sharply higher in a short window, the current P/E now bakes in a lot of confidence that recent profitability can be sustained. Explore the numbers behind Vericel's P/E valuation.
The Vericel Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Vericel's valuation puzzle leaves off by explaining which future paths for growth, profitability and earnings would need to occur for the stock to appear materially more expensive or cheaper than it does today. Each scenario links an implied fair value to a specific mix of potential catalysts and risks, allowing you to see over time which version of Vericel's story is tracking closest to reality on the Community page.
One of the top community narratives on Vericel: 10% undervalued
"Burn Care’s evolution into a second growth and cash engine, with NexoBrid supported by a BARDA agreement valued at up to about US$197m..."
Discover why this Narrative puts Vericel at 10% undervalued.
Vericel's price is only one piece of the investment puzzle
After looking at what the current P/E implies, the next useful cross-check is how professional analysts think Vericel’s earnings profile could look a few years from now, and how that compares with where the shares trade today. Explore where analysts expect Vericel to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com