


EN
Veradermics (VRDX) Stock Trades At A Premium On Book Value Concerns
Veradermics has been on a sharp run in 2026, and the jump in its share price now puts a spotlight on whether the stock still lines up with what its balance sheet says it is worth. With book value as the anchor, the question is how comfortably the current market price sits against the assets backing each share.
- Veradermics has gained about 267.6% year to date, which puts a lot of weight on whether its asset base and equity cushion can carry that kind of move.
- The business model leans heavily on converting research spending into future products, which can change how much of the current price rests on hard assets compared with expectations for future returns on that capital.
- Your read on Veradermics is one view; the desks covering it have another. See what analysts think Veradermics's shares could be worth.
The issue now is whether Veradermics' current share price is adequately supported by its book value when set against the industry average.
If you want more context around whether Veradermics' run aligns with its balance sheet, compare it with other companies screened for solid balance sheet and fundamentals stocks screener (24 results).
Is Veradermics Getting Expensive on Book Value?
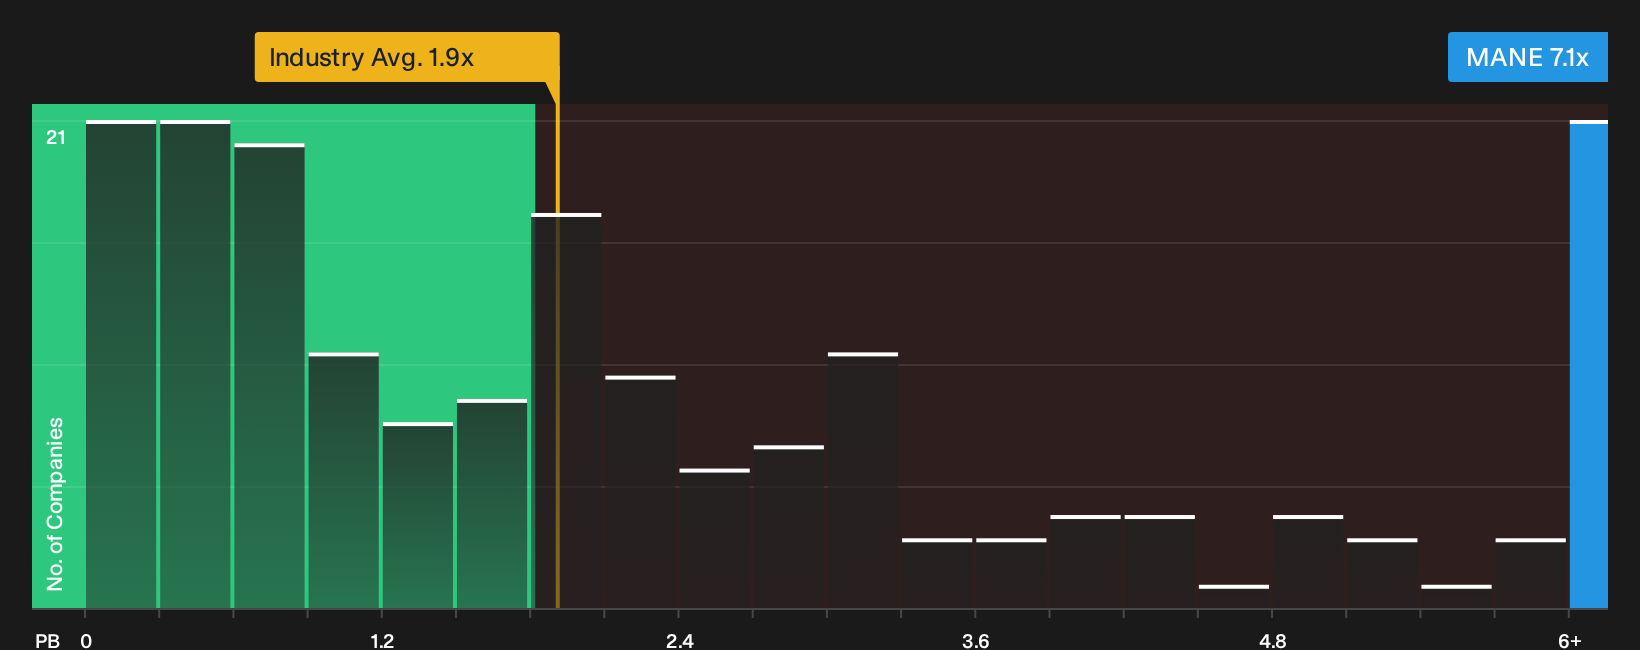
P/B is a clean lens for Veradermics because so much of the current debate is about what investors are paying for its equity base. On this score, the stock trades at about 7.1x book value.
That level sits far above the Pharmaceuticals industry average P/B of roughly 1.9x and is also well ahead of the peer group around 23.4x, which already runs richer than the sector. Veradermics therefore prices in a substantial premium to the typical drug developer on this metric, and the gap is large enough that any valuation model is likely to flag the shares as screening very expensively. For you as a shareholder or potential buyer, the question is whether the research pipeline and balance sheet quality justify paying more than both the broad sector and specialised peers for each dollar of net assets. Explore the numbers behind Veradermics's P/B valuation.
The Veradermics Narrative: What Would Justify Today's Price?
Veradermics' valuation puzzle sets up the role of Simply Wall St Narratives, which spell out what kind of growth, margins and earnings profile would need to play out for the shares to look meaningfully richer or cheaper than today’s price and sit on the Community page. Each narrative ties a specific fair value estimate to a clear storyline about Veradermics' potential catalysts and key risks so you can track which version of events is gradually taking shape.
Community views on Veradermics are split between those who see more upside in the hair loss program and those who think a lot is already reflected in the price.
Bull case: 19% undervalued
"Expanding focus on pattern hair loss in women, who currently have no FDA approved oral prescription treatments despite representing around 30 million people in the U.S., creates a large addressable pool of new patients..."
Discover why this Narrative puts Veradermics at 19% undervalued.
Bear case: roughly fairly valued
"Although Veradermics highlights a large, underserved pattern hair loss population with high willingness to pay, the company still has no approved product converting this interest into revenue..."
Explore why this Narrative puts Veradermics at roughly fairly valued.
One more Veradermics puzzle that could matter to you
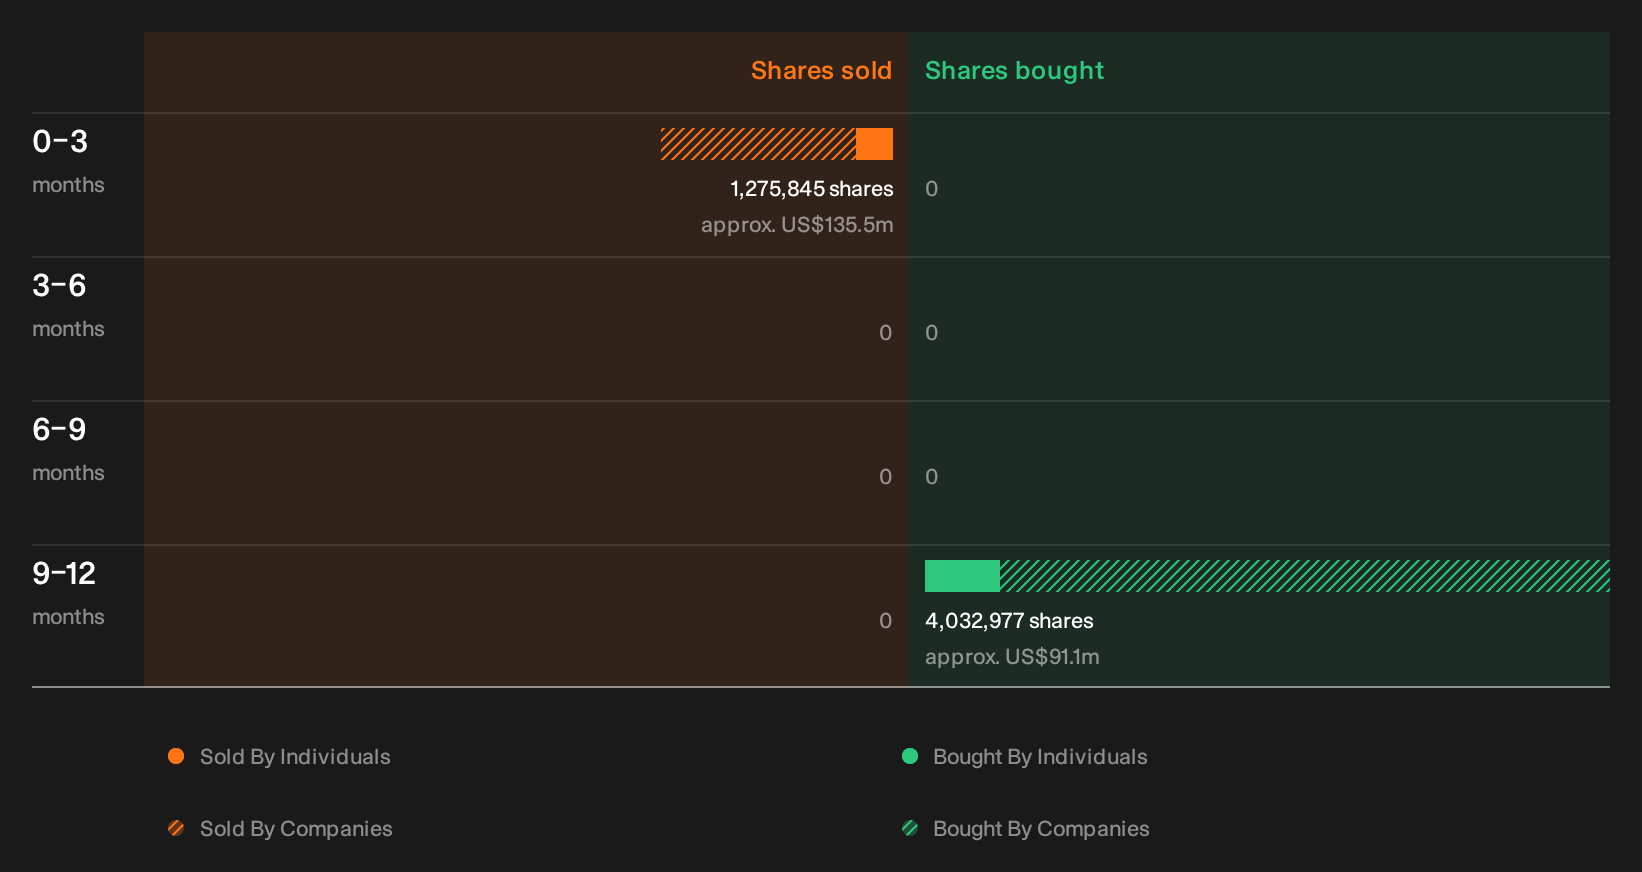
Valuation tells only part of the story for Veradermics, because recent dealings by people inside the business have also been flagged by our checks and the individuals involved, the size of those trades and what they might signal are still for you to unpack. See the recent insider selling flagged for Veradermics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com