


EN
What Bio-Techne Doubters Overlooked
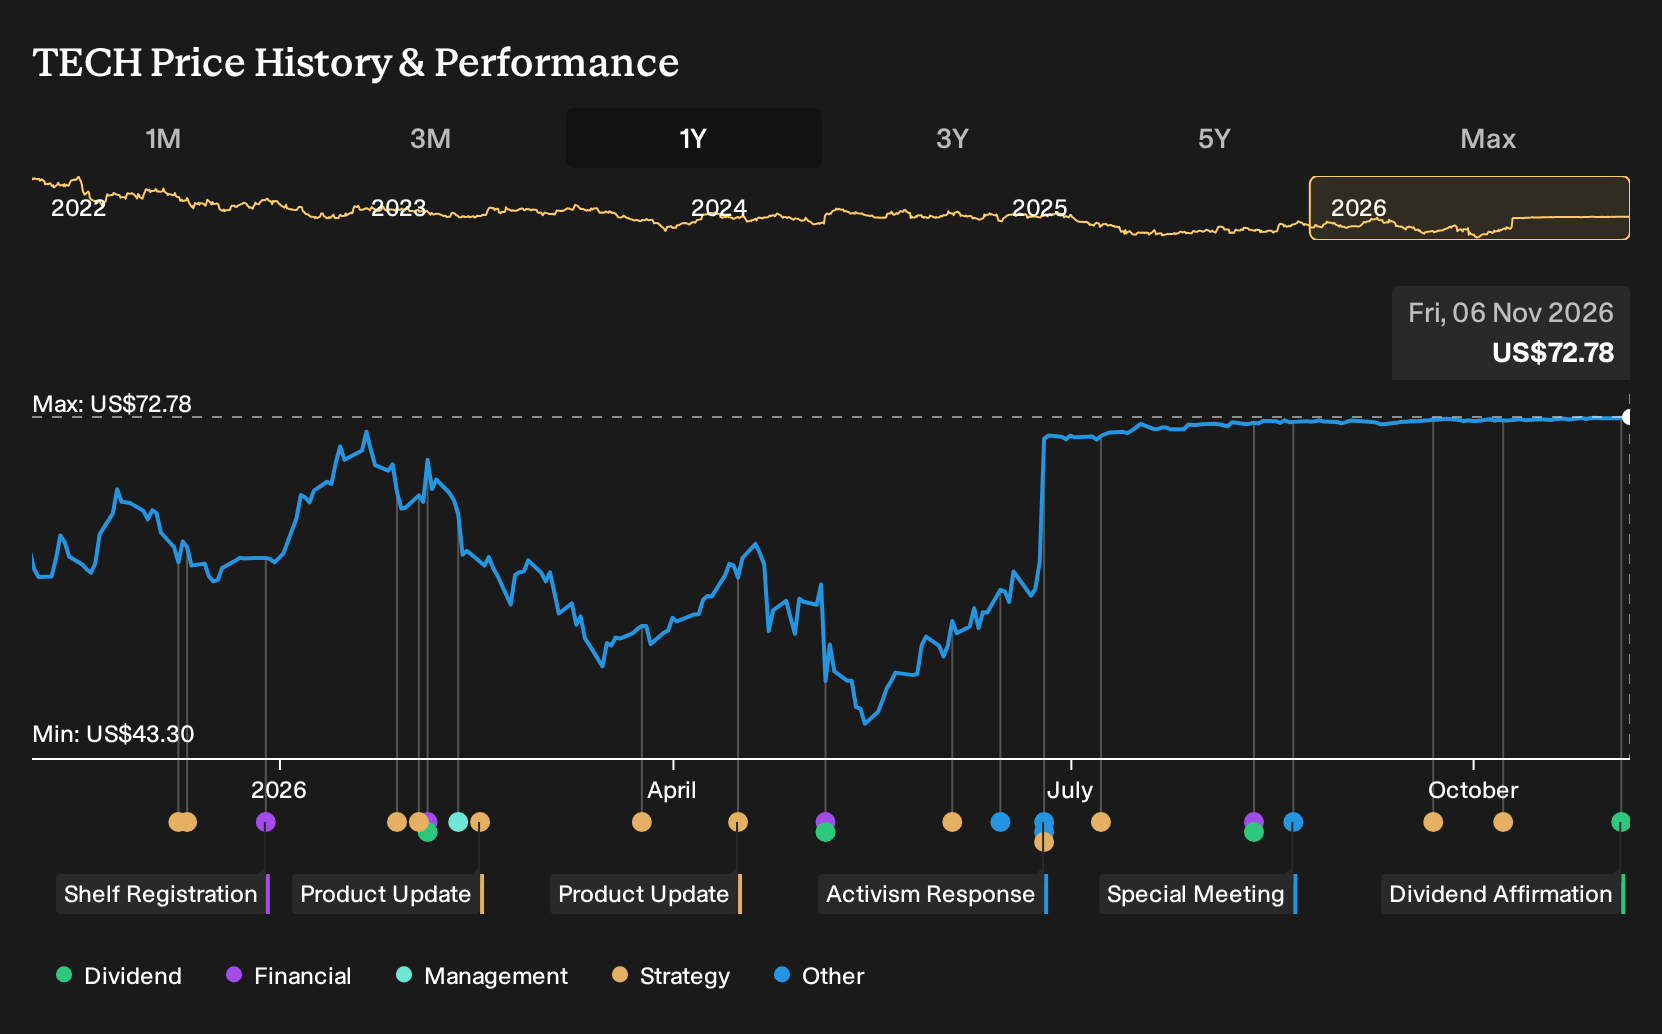
If Bio-Techne sat on your watchlist rather than in your portfolio, the outcome may feel like a missed shot. For Bio-Techne shareholders, the return over the past year was 27.5%, including dividends. That gain now raises an uncomfortable question. Back on 6 November 2025, could you reasonably have spotted that a business built on essential life science consumables and platforms might be priced as if those recurring revenues were less durable than they proved to be?
The move put Bio-Techne in the middle of this trade. Scan 35 healthcare AI stocks for other companies exposed to it.
The Two Stories Investors Had To Choose Between On Bio-Techne
The shares cost US$58.18 at the start of the period, and anyone looking at Bio-Techne then had to decide which story felt more realistic.
On the optimistic side, the bullish narrative put Fair Value at US$80, a rough guide to what the price might be if assumptions played out. That view leaned on rapid uptake of platforms like Simple Western, high-margin consumables, and 80% recurring revenue from reagents and diagnostics tools.
The cautious script argued for a Fair Value of US$54.08, implying only limited upside. That bearish case focused on possible cuts to NIH funding, tighter healthcare budgets in the US and Europe, and pressure on pricing as reagents and instruments risked commoditisation.
What The Results Changed For The Bio-Techne Debate
Bio-Techne’s Q4 2026 report showed revenue of US$321.2 million and net income of US$54.6 million, with net margin moving from a loss of 5.6% to a 17.0% profit. That shift in profitability aligned more with the optimistic script that expected margin resilience, although the period’s flat to modest top-line record kept the cautious view on demand alive. Overall, the evidence cut both ways.
The key assumption here was how durable and profitable Bio-Techne’s consumables and platforms would be. For another stock built on recurring tools and reagents, focus on the trend in net margin alongside revenue in quarterly filings to see whether high recurring sales actually convert into improving profitability.
What Bio-Techne's Recent Run Already Prices In
Bio-Techne now trades at US$72.78 after a 27.5% gain over the past year. The selected Narrative’s Fair Value sits below that price, framing today’s level as already baking in a cleaner Merck integration and a smoother earnings path than its more cautious view assumes.
The same Narrative hinges less on funding worries and more on whether higher engagement in proteomic and cell therapy tools can support organic revenue and margins without overpaying for that promise. Anyone buying here is effectively assuming integration delivers and product mix holds up. How does that square with the highlighted risks?
"While Merck is targeting high single digit revenue growth from Bio-Techne and has identified about €140 million of cost synergies that it expects to realize within three years of closing, any shortfall in merger integration or inability to capture these savings could leave group margins and EPS below current expectations, which could put pressure on the combined company’s earnings profile."
The price and this Narrative do not agree. → Uncover what this Narrative says Bio-Techne is actually worth
Bio-Techne And Chronic Disease Demand
Bio-Techne sits in the tools layer of healthcare, supplying assays and reagents for lab work.
Patients with chronic cardiometabolic conditions confront a separate challenge. They depend on prescription treatments that can alter long term care patterns.
An unnamed pharmaceutical group is developing therapies for obesity, diabetes and related complications to expand treatment choices for specialists.
Those drugs do not move through Bio-Techne platforms, but they reflect a shared trend.
As chronic disease care evolves, demand for both tools and therapies could diverge in unexpected ways.
One Narrative has already put a figure on it. → Uncover the company trading 18% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com