


EN
Is Cushman & Wakefield (CWK) Undervalued As Strong Q3 Earnings Reaffirm Full Year Guidance?
Cushman & Wakefield (CWK) drew fresh attention after reporting third quarter 2026 results that exceeded analyst earnings expectations, while reaffirming full year guidance for revenue growth toward the high end of its 6% to 8% target range.
The recent guidance reaffirmation and Q3 beat have arrived after a mixed stretch for Cushman & Wakefield’s investors. The 1 month share price return of 22.24% suggests momentum has picked up, although the year to date share price return is still down 11.87% and the 1 year total shareholder return has declined 11.25%. Even with an 84.90% total shareholder return over three years, this points to a longer run recovery story that the latest earnings and capital markets news appear to have brought back into focus.
See how Cushman & Wakefield’s post-earnings move compares with other real estate and services stocks seeing renewed interest with our curated 39 high quality undervalued stocks.
Cushman & Wakefield now trades at a sizeable discount to analyst targets and an even wider gap to some fair value estimates. After this sharp rebound, is that pricing caution, or is the opportunity being misjudged?
Most Popular Narrative: 18% Undervalued
Cushman & Wakefield’s most-followed valuation story pegs fair value at $17 per share against a last close of $13.96, which raises a clear question about whether the recent rally has fully closed that gap or only partially narrowed it.
The intensified focus on operational efficiency supported by technology investments and internal restructuring continues, with recent margin expansion in EMEA services and AI tools in project management indicating additional operating leverage that can support net margin and earnings quality.
See why 2 investors see Cushman & Wakefield as 18% undervalued.
Result: Fair Value of $17 (UNDERVALUED)
Still, Cushman & Wakefield’s reliance on cyclical leasing and capital markets fees, along with the ongoing Pinnacle legal exposure, could quickly weaken that undervalued narrative.
Find out about the key risks to this Cushman & Wakefield narrative.
Another View: Cushman & Wakefield On Earnings Multiples
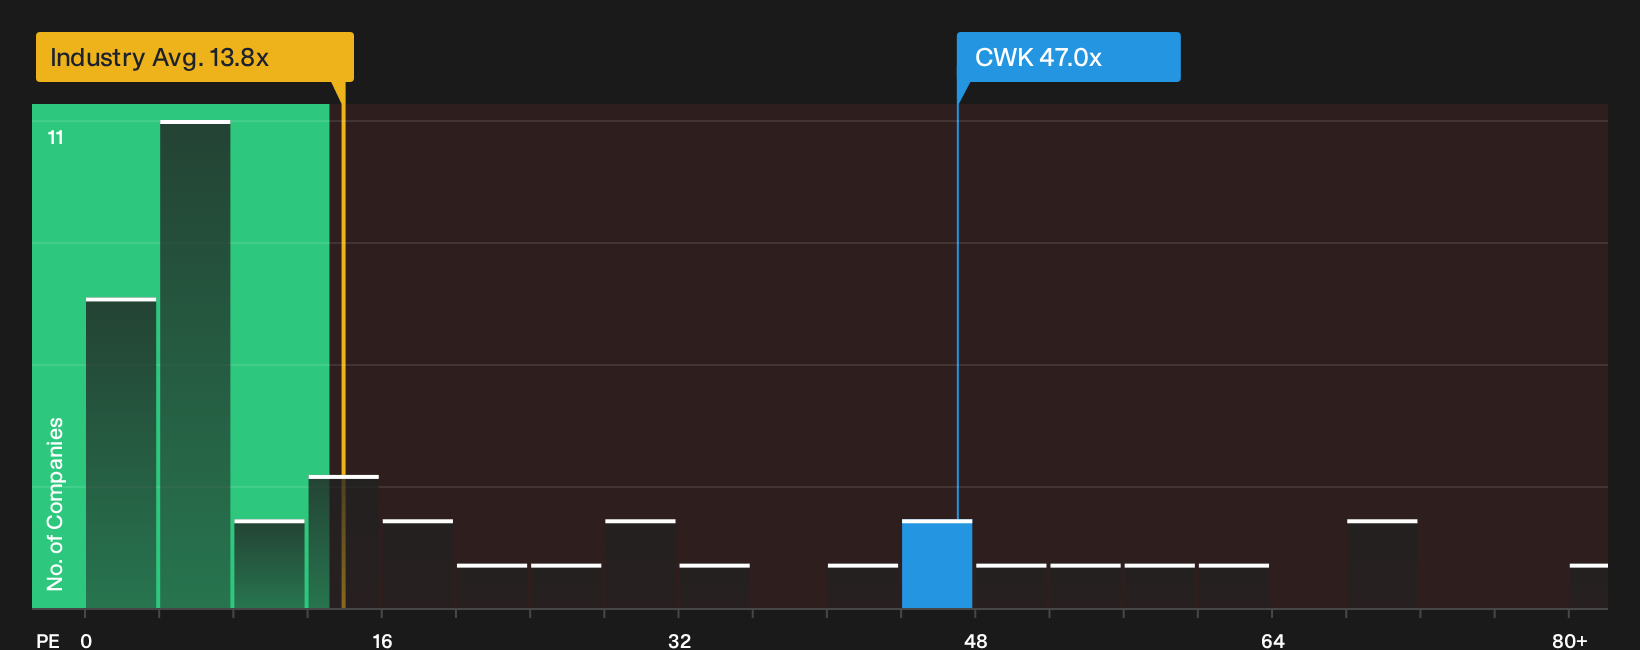
Cushman & Wakefield screens as undervalued on cash flow models, yet the P/E ratio of 47x tells a different story. That is more than triple the wider US real estate sector on 14.2x and still above the 25.6x fair ratio that the market could move toward. If sentiment cools, how much of that gap do you think closes first?
To pressure test the earnings-based view against the cash flow case, investors can review our valuation breakdown in more detail, including how earnings, sector peers and the fair ratio all line up for this stock, through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals around Cushman & Wakefield leave you torn, move quickly from headline takeaways to the underlying numbers and judgement calls. The business carries both concerns and potential upside, so balance the red flags against the brighter spots by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cushman & Wakefield?
Do not stop with one earnings story. Broaden your watchlist now so you are not chasing the next move after everyone else has already reacted.
- Target dependable cash flows by reviewing companies that show up in our 8 dividend fortresses for income-focused opportunities with meaningful yield support.
- Hunt for quality at a discount by scanning the 19 high quality undiscovered gems that pair solid fundamentals with limited current market attention.
- Prioritise resilience by assessing businesses in the 29 resilient stocks with low risk scores that combine sturdier balance sheets with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com