


EN
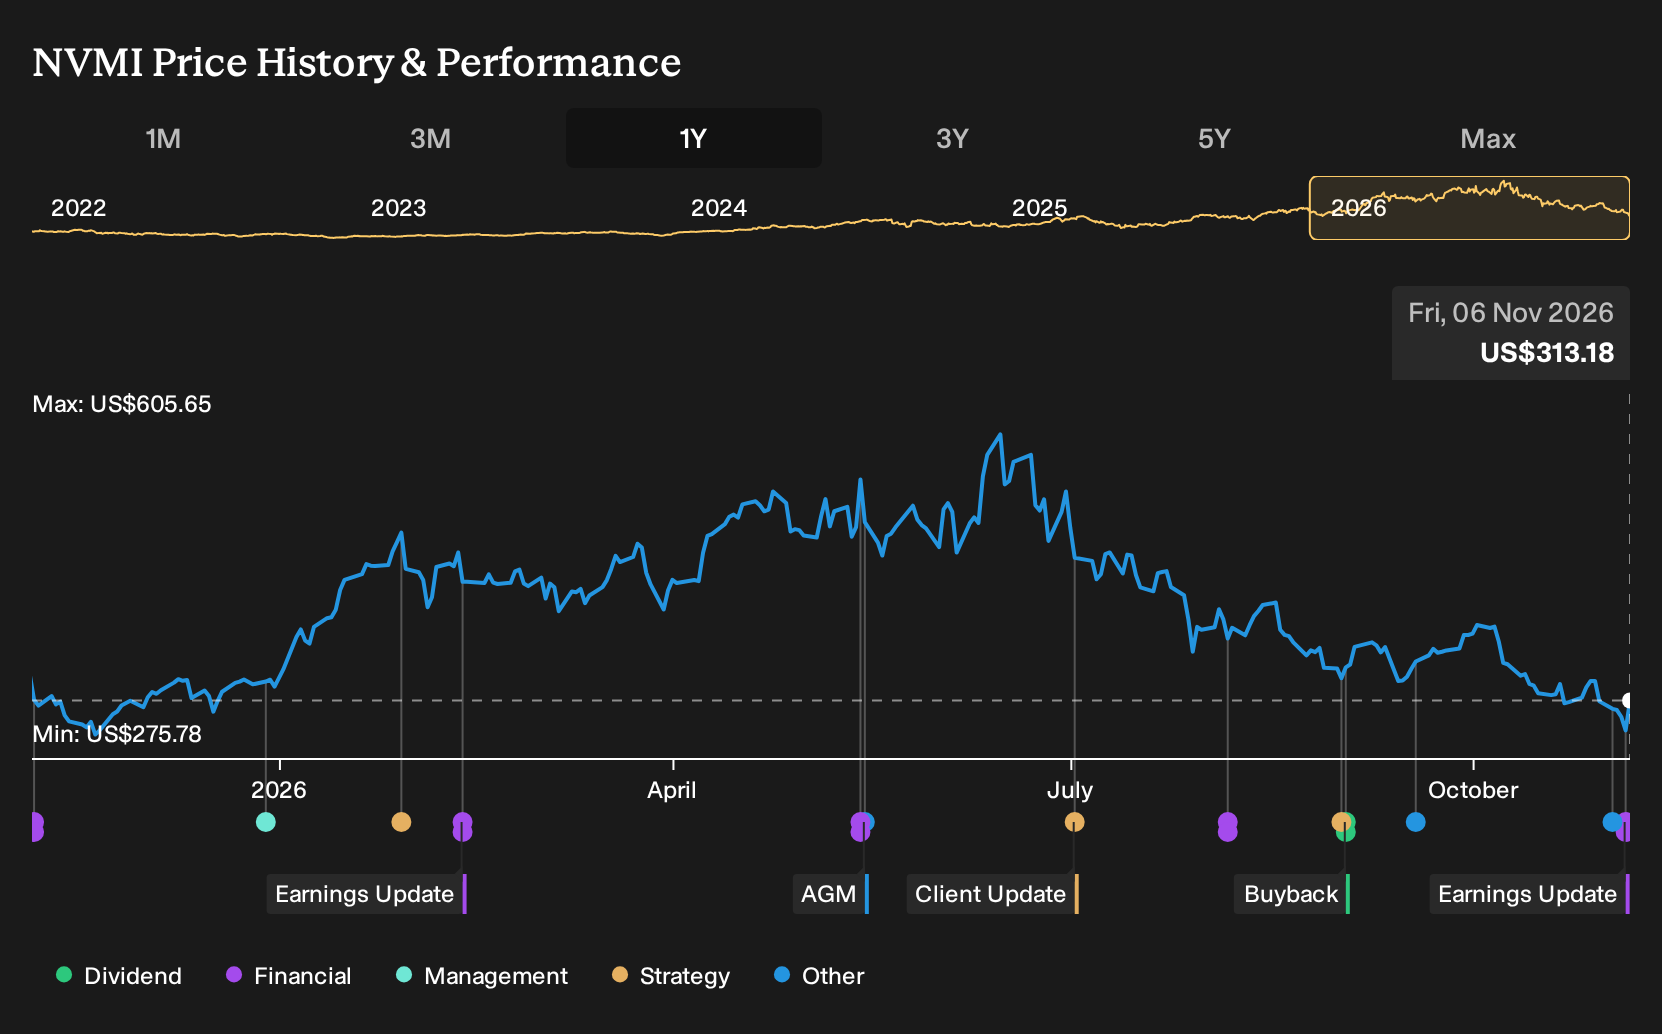
Nova Stock Q3 Earnings Beat Has The Bull Case Changed
- Nova Ltd. reported record Q3 2026 results, with revenue of US$287.84 million and net income of US$89.96 million, alongside stronger than expected Q4 guidance for both sales and diluted GAAP EPS.
- The business highlighted intense demand in memory and advanced packaging, while operating margins moved above its target range despite supply chain constraints and higher R&D spending.
- We will look at how Nova's record Q3 revenue performance and confident Q4 outlook reshape the broader investment narrative around the business.
Scan how Nova's Q3 momentum in memory and advanced packaging compares with other potential breakouts across 52 AI infrastructure stocks in the same supply chain.
Nova Investment Narrative Recap
To own Nova today, an investor has to believe that rising metrology intensity in memory, logic and advanced packaging continues to translate into healthy tool demand and solid profitability. The latest quarter supports that thesis at the operating level, with record Q3 revenue of US$287.84 million and net income of US$89.96 million, alongside higher R&D and supply chain friction that the business is still absorbing.
The key short term catalyst is whether this operational momentum carries into year end and into new fab ramps, without mix headwinds from DRAM heavy spending or NAND upgrades dragging on tool placements. The biggest near term risk remains execution against that backdrop, including China exposure and local competition, rather than anything materially new in the Q3 print itself.
The most relevant update for that catalyst is Nova’s Q4 2026 guidance. Management is calling for US$305 million to US$315 million in revenue and US$2.78 to US$2.93 in diluted GAAP EPS. If achieved, this would keep the firm on the path set by the record Q3 and the US$1 billion annual revenue milestone reached a year ahead of plan.
For you as a shareholder or prospective holder, the question is whether those targets look achievable given supply constraints, a still mixed wafer fab spending pattern and growing Chinese metrology vendors. If the company continues to place tools into high complexity nodes and advanced packaging while protecting margins above its target model, that Q4 range becomes a useful reference point for how much operational headroom might be left.
Nova's current analyst narrative points to revenue of US$1.7b and earnings of US$569.9 million by 2029, based on an assumed 22.6% yearly top line expansion and an earnings increase of about US$299.5 million from US$270.4 million today.
Uncover how Nova's fair value indicates a 64% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist in the Nova story comes from advanced packaging. The most optimistic analysts were already assuming revenue could reach about US$1.9b and earnings around US$587.2 million by 2029, driven by packaging metrology gaining share. Those views were set before this Q3 beat and fresh guidance, so expectations could easily shift again from here.
Explore 3 other Nova fair value estimates, including one that suggests as much as 64% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nova research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nova's overall financial health at a glance.
Looking for more investment ideas beyond Nova?
If Nova has sharpened your appetite for opportunities in semiconductors and adjacent areas, it can help to widen the lens and compare it with other companies that share similar quality markers or risk profiles.
- For investors who care most about valuation and balance sheet strength, start with a curated 39 high quality undervalued stocks that combine solid cash generation with financial resilience.
- If income stability is your priority, check out a focused set of 8 dividend fortresses that aim to pair higher yields with more durable payout profiles.
- For a broader watchlist anchored on financial robustness, build out your universe using the list of solid balance sheet and fundamentals (24 results) to quickly spot companies with cleaner leverage and stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com