


EN
Will Raised Earnings Guidance Change Teleflex Stock Narrative
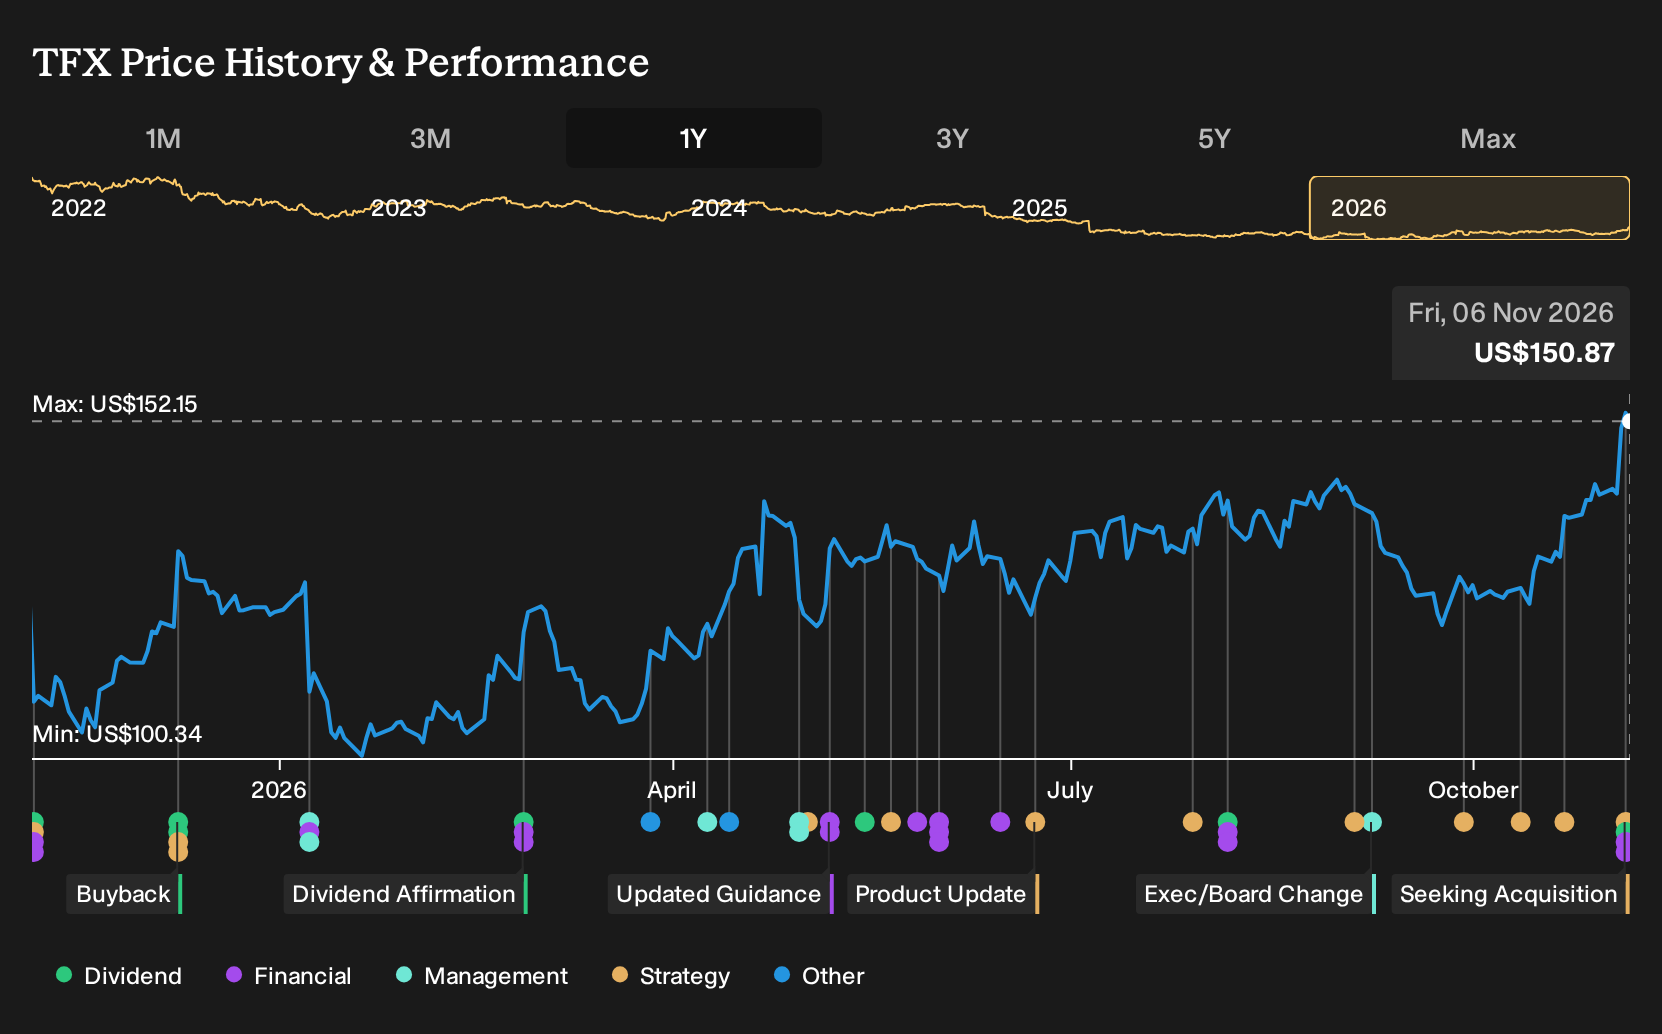
- Teleflex reported Q3 2026 sales of US$567.78 million and a swing to profit, raised full year GAAP and adjusted earnings guidance, kept its US$0.34 quarterly dividend, completed a roughly US$573.35 million buyback program, and signaled interest in tuck in acquisitions aligned with its three core segments.
- The combination of margin expansion, higher earnings outlook, sizable share repurchases equal to 9.96% of stock outstanding, and a continued dividend suggests Teleflex is leaning on both operating performance and capital returns, while keeping capacity for targeted deals.
- We will now look at how Teleflex's higher full year earnings guidance could shape the existing investment narrative around margin reset.
Scan how Teleflex’s mix of earnings guidance, buybacks and tuck in deal appetite compares with other potential opportunities by reviewing the list of solid balance sheet and fundamentals (24 results) in one pass.
Teleflex Investment Narrative Recap
To own Teleflex, you need to be on board with a story that leans on margin repair, better execution in Interventional, and disciplined use of capital. The raised 2026 GAAP and adjusted EPS guidance, alongside a swing back to profit, points to earnings rather than the top line being the near term focus. The main short term catalyst remains progress on margin expansion.
The biggest near term risk still sits in integration and cost execution, especially around stranded costs and the Interventional segment catching up with earlier expectations. Recent results and guidance changes do not remove that risk, but they reduce immediate concern around earnings power if current trends hold.
The most relevant fresh data point is the completion of the US$573.35 million buyback program, which retired 9.96% of Teleflex’s share count. That scale of repurchase, in combination with higher 2026 adjusted EPS guidance, tightens the link between operational delivery and per share outcomes. It also amplifies any execution miss.
With a continued US$0.34 quarterly dividend and management stating that excess capital may go to further buybacks or eventually M&A, your attention probably shifts to how consistently Teleflex converts margin plans, R&D investment, and tuck in deals into cash generation. That is the core axis along which future catalysts and setbacks are likely to be felt.
Teleflex's current analyst storyline points to forecast revenues of US$2.5b and projected earnings of US$374.2 million by 2029. This outlook is built on an assumed 3.9% yearly revenue growth rate and a swing in earnings from a loss of US$25.1 million today to that US$374.2 million figure, which is an increase of roughly US$399 million.
Uncover why Teleflex's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view around Teleflex focuses less on tuck in acquisitions and more on the risk that margins stay stuck. The most pessimistic analysts were modeling revenue of about US$2.5b and earnings of roughly US$262.3 million by 2029, far below the US$374.2 million consensus path. This fresh guidance and deal appetite may shift those narratives.
Explore 3 other Teleflex fair value estimates, including one that suggests it could be worth just $154.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Teleflex research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teleflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teleflex's overall financial health at a glance.
Looking for more investment ideas beyond Teleflex?
If Teleflex is on your radar, it can help to set it alongside a few different types of opportunities and see how the risk, balance sheet strength, and income profile stack up.
- For investors who care about resilience first and upside second, compare Teleflex against a group of companies flagged as having lower risk profiles through the 29 resilient stocks with low risk scores.
- If you want to keep capital preservation front and center while still leaving room for upside, weigh Teleflex against a list of solid balance sheet and fundamentals (24 results) that filters for stronger finances.
- Those hunting for underappreciated stories can contrast Teleflex with a 19 high quality undiscovered gems that puts quieter but higher quality opportunities on your screen.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com