


EN
FormFactor Stock Gains Attention After Earnings Beat and Chip Equipment Rally
- FormFactor reported Q3 2026 sales of US$280.55 million and net income of US$73.82 million, with basic EPS from continuing operations at US$0.94, and issued Q4 guidance that points to expected revenue of about US$285 million and net income per diluted share around US$0.84.
- The latest results show FormFactor generating higher earnings from its existing footprint over the first nine months of 2026. This suggests management is controlling costs and using its capacity and product mix more efficiently as demand for semiconductor testing equipment remains important for customers.
- We will now look at how FormFactor's stronger earnings profile could influence the broader investment narrative around its AI focused test portfolio.
Scan how FormFactor's earnings story fits into the broader chip equipment trade by comparing it with 52 AI infrastructure stocks, which is riding the same demand for high performance compute testing and capacity builds.
FormFactor Investment Narrative Recap
For you to stay interested in FormFactor, you need to believe that demand for AI related, high complexity chip testing continues to require dense probe card content and more systems, and that the Texas footprint and operational changes support that workload. The latest quarter shows the business generating higher earnings on a larger base, but the key near term swing factor remains how smoothly advanced AI and HBM programs move from pilot into steadier volume.
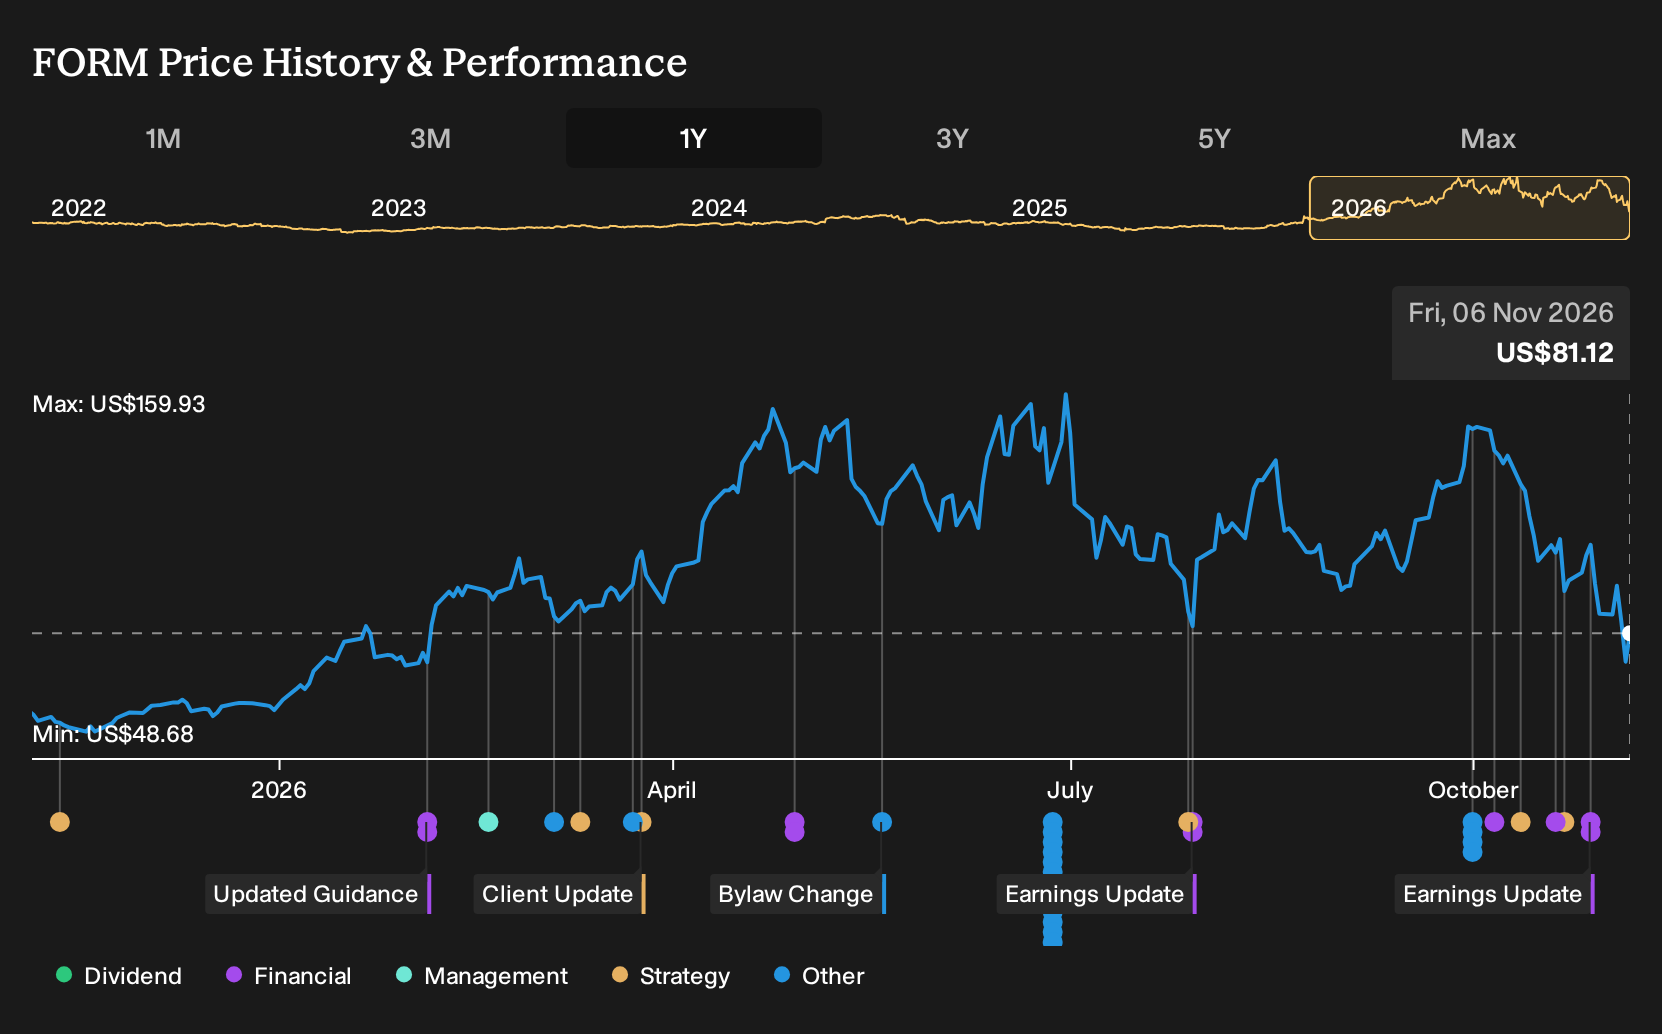
The biggest risk in the short run still appears to be disappointment against very high expectations, particularly after a strong multi year share price run and sectorwide enthusiasm. Any cooling in AI test intensity or a mix shift away from high value DRAM and GPU projects could pressure margins and order visibility, even if operational execution remains tight.
The clearest operational reference point in the latest news is FormFactor’s Q4 2026 guidance, with management indicating expected revenue of around US$285 million and net income per diluted share of around US$0.84. That guide provides a near term benchmark for how sustainably the company can convert its recent AI and HBM probe wins, and the newer systems programs, into consistent profitability.
Guidance also frames the execution test. If FormFactor delivers on that revenue range while maintaining a healthy earnings run rate, it supports the idea that the cost base and product mix are working at the current scale. If results land toward the lower end, or if volatility emerges around large DRAM and GPU customers, it would highlight how exposed the company still is to concentrated AI infrastructure cycles.
FormFactor's narrative projects US$1.6b revenue and US$519.5 million earnings by 2029. That path assumes 20.8% yearly revenue growth and an earnings increase of roughly US$404 million from US$115.5 million today.
Uncover why FormFactor's fair value indicates a 90% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle you might explore is the bullish catalyst around FormFactor’s Texas expansion. The most optimistic analysts were already modeling about US$1.9b of revenue and roughly US$597.5 million of earnings by 2029, before factoring in this latest quarter and guidance. That is a far more upbeat story than consensus, so use this Q3 surprise and Q4 outlook as a chance to compare how those contrasting assumptions could evolve from here.
Explore 3 other FormFactor fair value estimates, including one that suggests as much as 147% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your FormFactor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FormFactor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FormFactor's overall financial health at a glance.
Looking For More Ideas Beyond FormFactor?
If FormFactor is already on your radar, it can help to widen the lens and compare it with other companies that fit different risk and return profiles. The Simply Wall St Screener lets you scan for stocks that match the kind of balance sheet strength, income potential, or upside you want to focus on next.
- For investors who care most about resilience and downside protection, filter for companies with sturdier financial profiles using the 29 resilient stocks with low risk scores.
- If long term compounding and quality at a sensible entry price matters to you, cast a wider net across businesses trading below their estimated worth through the 39 high quality undervalued stocks.
- When reliable cash returns are a priority, shape a shortlist of income ideas by scanning for higher yielding payers via the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com