


EN
Missed Manappuram Finance's Run? What Holders Had To Believe
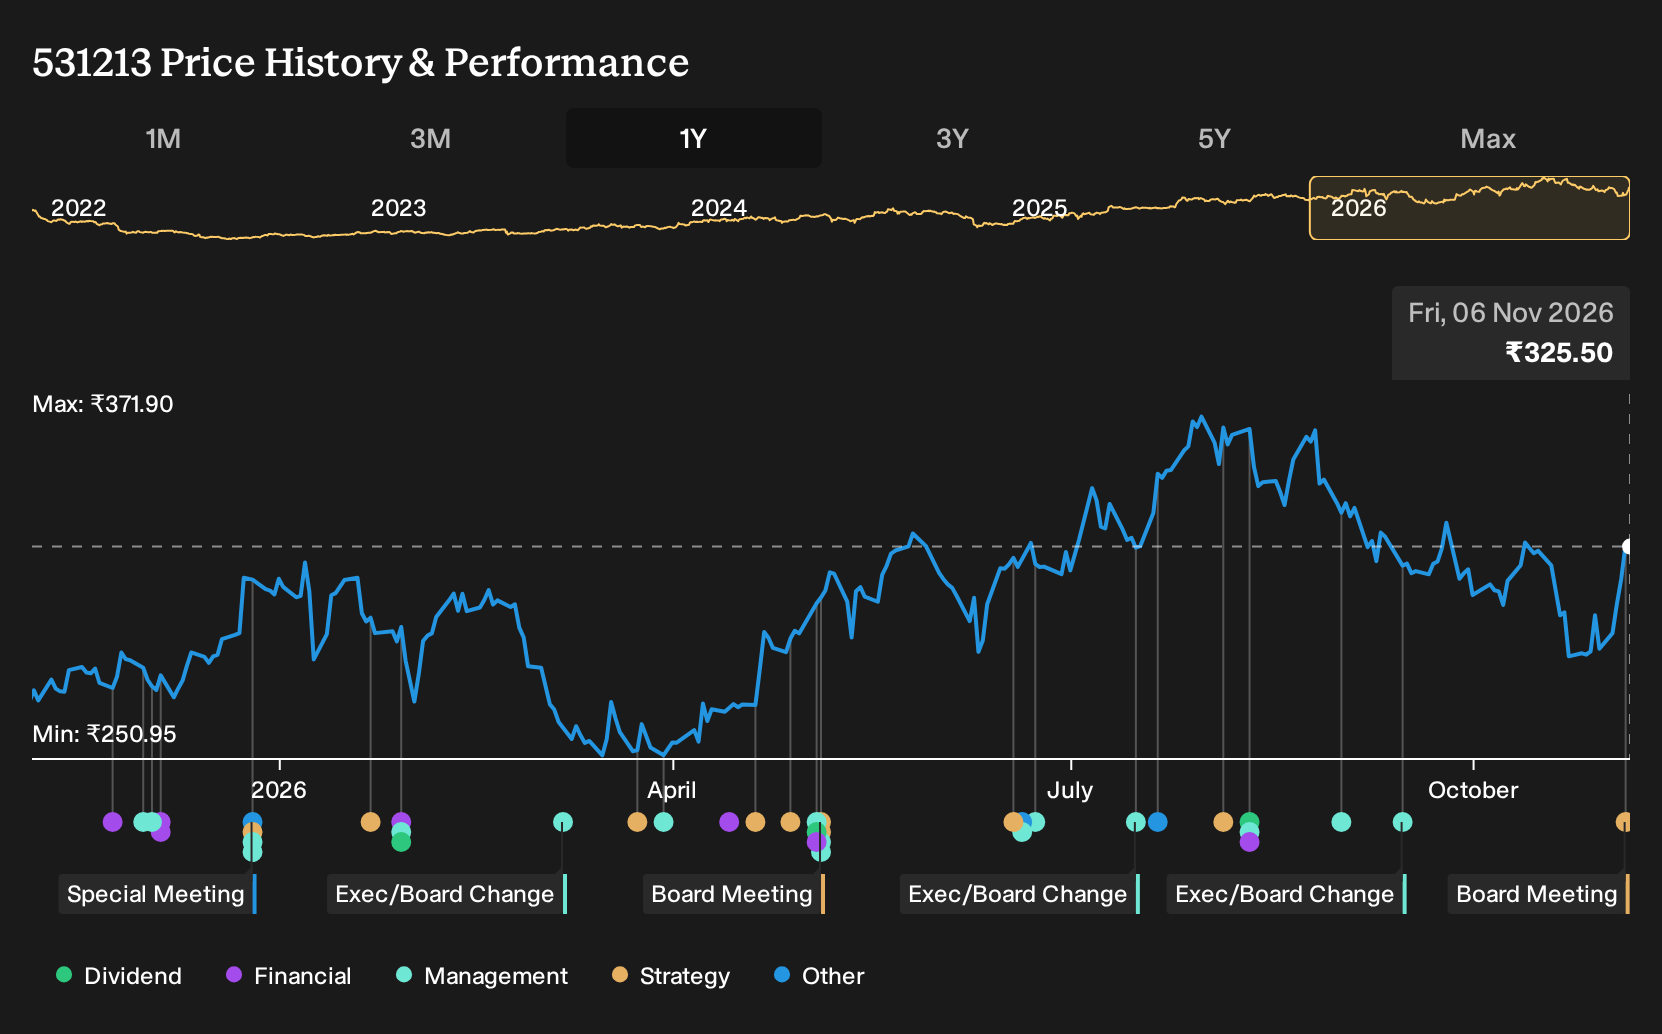
Manappuram Finance’s latest quarterly filing put hard numbers on a shift that had only been theory before. Revenue came in at ₹14,922.2m and net income at ₹5,845.8m in Q1 2027, compared with ₹8,286.4m and ₹1,383.8m a year earlier. Investors who held Manappuram Finance over the past year are up 21.0%, including dividends. If you had been deciding on 6 November 2025, what would you have needed to believe about digital gold lending and margins before those results appeared?
If the move has made Manappuram Finance harder to judge, start where the gap is still open and scan 224 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Manappuram Finance
The shares cost ₹274 at the start of the period, so any view on Manappuram Finance hinged on whether digital lending could really justify that entry point.
The bullish narrative pointed to a Fair Value of ₹300, a price level implied by expectations that digital adoption and AI underwriting would keep sourcing about 85% of gold loans online and compress the cost to income ratio.
The bearish view anchored on a Fair Value of ₹185 and focused on rising fintech rivalry, yield cuts in gold loans, and the risk that tighter competition would steadily squeeze net interest margins.
What The Results Changed For The Manappuram Finance Thesis
The clearest fact is the Q1 2027 print. Manappuram Finance reported revenue of ₹14,922.2m and net income of ₹5,845.8m, up from ₹8,286.4m and ₹1,383.8m in Q1 2026, with net margin rising from 16.7% to 39.2%. That shift in profitability gave more weight to the bullish argument about digital efficiency and wider margins, even though one quarter cannot settle a multi year debate.
The lesson is simple. When a story leans on digital adoption and cost to income gains, you test it against reported net margin and absolute profit, not just revenue growth. For any other lender pitching a similar upgrade, track whether rising tech spend actually coincides with a fatter margin line a year or two later.
What Manappuram Finance’s Price Now Asks You To Believe
Manappuram Finance trades at ₹326 after a 21.0% gain over the past year. The selected Narrative sees its Fair Value below that quote, because higher funding costs and legacy asset quality questions still sit alongside the stronger gold loan engine.
A buyer today effectively assumes management can hit ambitious ROA and ROE goals despite these frictions. The key question is how the required return targets compare with the Narrative’s concerns about borrowing costs and stressed non gold books.
"The current valuation implies that Manappuram Finance will meet ambitious return targets such as 3.5 to 4% ROA and 15 to 18% ROE at a time when funding costs are elevated and some non gold segments still show residual asset quality risk."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 20% below our estimate - targets surgeons adopting antibiotic-eluting bone grafts to reduce systemic drug exposure.
- Company 2 - 15% below our estimate - scales an asset light legal platform enabling senior lawyers to design flexible careers.
- Company 3 - 40% below our estimate - sells AI chips and software into data centers upgrading for GPU heavy computing demand.
Three companies from the same screener. Open every one of the 193 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com