


EN
How Investors May Respond To Hanover Insurance Group Stock After Strong Nine Month Earnings
- Hanover Insurance Group reported third quarter 2026 revenue of US$1,735.5 million and net income of US$172.6 million, while nine month figures reached US$5,163.1 million in revenue and US$551 million in net income, and the insurer completed a US$119.69 million buyback covering 1.59% of shares.
- The combination of steady year to date earnings progress and a completed repurchase of 556,851 shares tightens Hanover Insurance Group's equity base, which can amplify per share metrics and indicates management's focus on returning capital alongside operational execution.
- Investors may now assess how Hanover Insurance Group's nine month earnings performance could influence its broader investment narrative for long term holders.
Hanover Insurance Group Investment Narrative Recap
To own Hanover Insurance Group, you need to be comfortable with a fairly measured growth story that leans on underwriting discipline, technology driven efficiency and Specialty plus Small Commercial expansion. The latest quarter showed revenue of US$1,735.5 million and net income of US$172.6 million, with nine month earnings still supporting that broader thesis.
The main near term swing factor remains execution in Specialty and Core Commercial while keeping loss ratios in check, especially around catastrophe exposure. The biggest risk is slower top line progress or heavier catastrophe activity, which could pressure margins. The recent results do not radically change that near term risk reward balance.
The most relevant update here is the third quarter and nine month earnings report. Revenue for the nine months reached US$5,163.1 million and net income was US$551 million, with diluted EPS from continuing operations at US$15.43 compared with US$12.70 a year earlier. That earnings profile gives you concrete figures to measure execution against the long term plan.
For catalysts, those EPS figures sit alongside ongoing investment in AI enabled underwriting and claims tools, which are intended to support expense and loss adjustment ratios over time. In the context of risks such as potential catastrophe losses and competitive pressure in Core and Small Commercial, this earnings report allows you to track whether Hanover Insurance Group is turning those technology and product ambitions into durable profitability.
Hanover Insurance Group's current earnings of US$753.8 million sit against analyst expectations for US$7.4b in revenue and US$629.6 million in earnings by 2029, which implies forecast annual top line expansion of 3.2% and an earnings decline of about US$124 million from today's level.
Uncover why Hanover Insurance Group's fair value is essentially aligned with its current price.
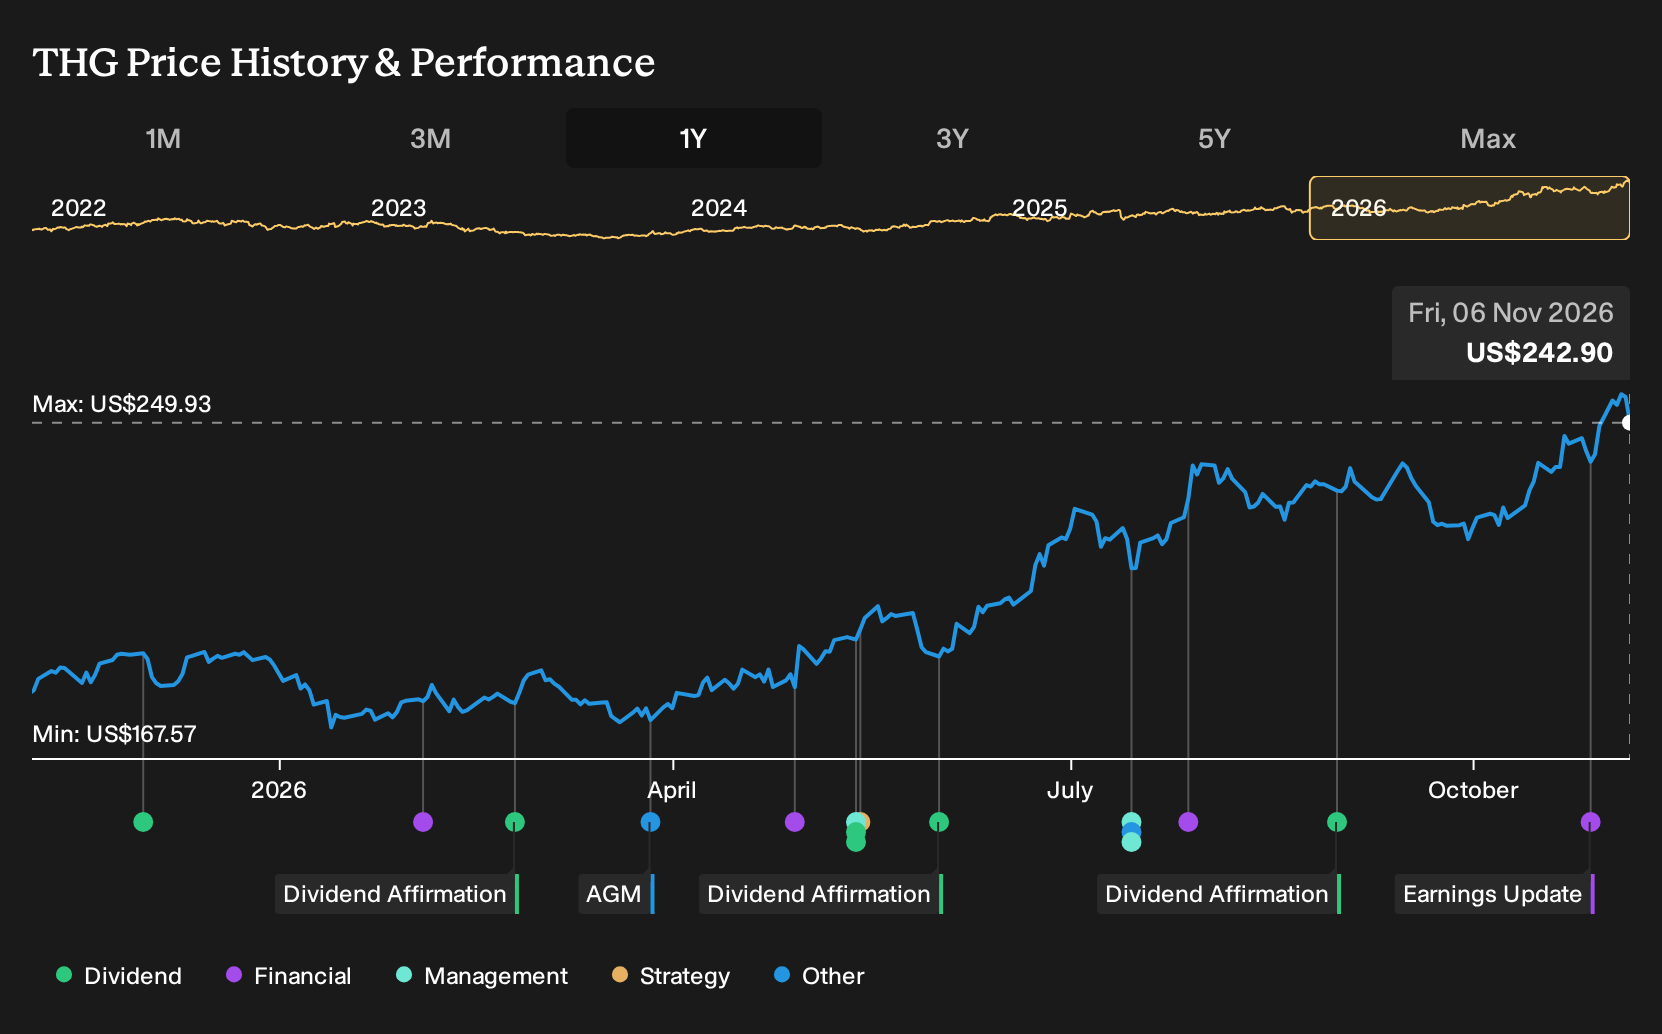
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span a wide band, from about US$238 per share up to roughly US$506, reminding you that opinions on Hanover Insurance Group can diverge sharply. Consider those homegrown models in light of the recent buyback completion, as well as ongoing catastrophe and Specialty risks, then explore more community viewpoints before firming up your own stance.
Explore another Hanover Insurance Group fair value estimate, including one that suggests as much as 108% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hanover Insurance Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hanover Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hanover Insurance Group's overall financial health at a glance.
Looking For More Ideas Beyond Hanover Insurance Group?
If you want to apply the same disciplined approach you use for Hanover Insurance Group to a wider watchlist, the Simply Wall St Screener can help you quickly filter the market for specific qualities rather than scrolling through tickers at random.
- For investors who care most about valuation and balance, scan a focused set of 39 high quality undervalued stocks that pair compressed pricing with stronger fundamentals than the broader market.
- If income steadiness matters to you, narrow the field to companies offering resilient cash distributions by reviewing a curated pool of 8 dividend fortresses that meet a 5%+ yield hurdle.
- When capital preservation sits near the top of your checklist, start with a 29 resilient stocks with low risk scores that filters for businesses flagged with resilient financial profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com