


EN
International Seaways (INSW) Delivers Record Q3 As $5.05 Dividend Puts Payout In Focus
- On 5 November 2026, International Seaways (NYSE: INSW) reported record Q3 2026 results, citing exceptionally strong tanker market conditions.
- Management highlighted the recently completed Bruton Limited fleet acquisition as a key driver of scale, alongside further dual fuel LR1 tanker investments.
- The board approved an expanded share repurchase program and a higher dividend, signalling a larger cash return to shareholders.
- This mix of record Q3 performance, the Bruton Limited deal and richer capital returns deserves weighing against our wider thesis on International Seaways. Check out 4 warning signs (2 major) that International Seaways investors should know about.
For readers comparing International Seaways with other income ideas in shipping and beyond, the next stop is 8 dividend fortresses.
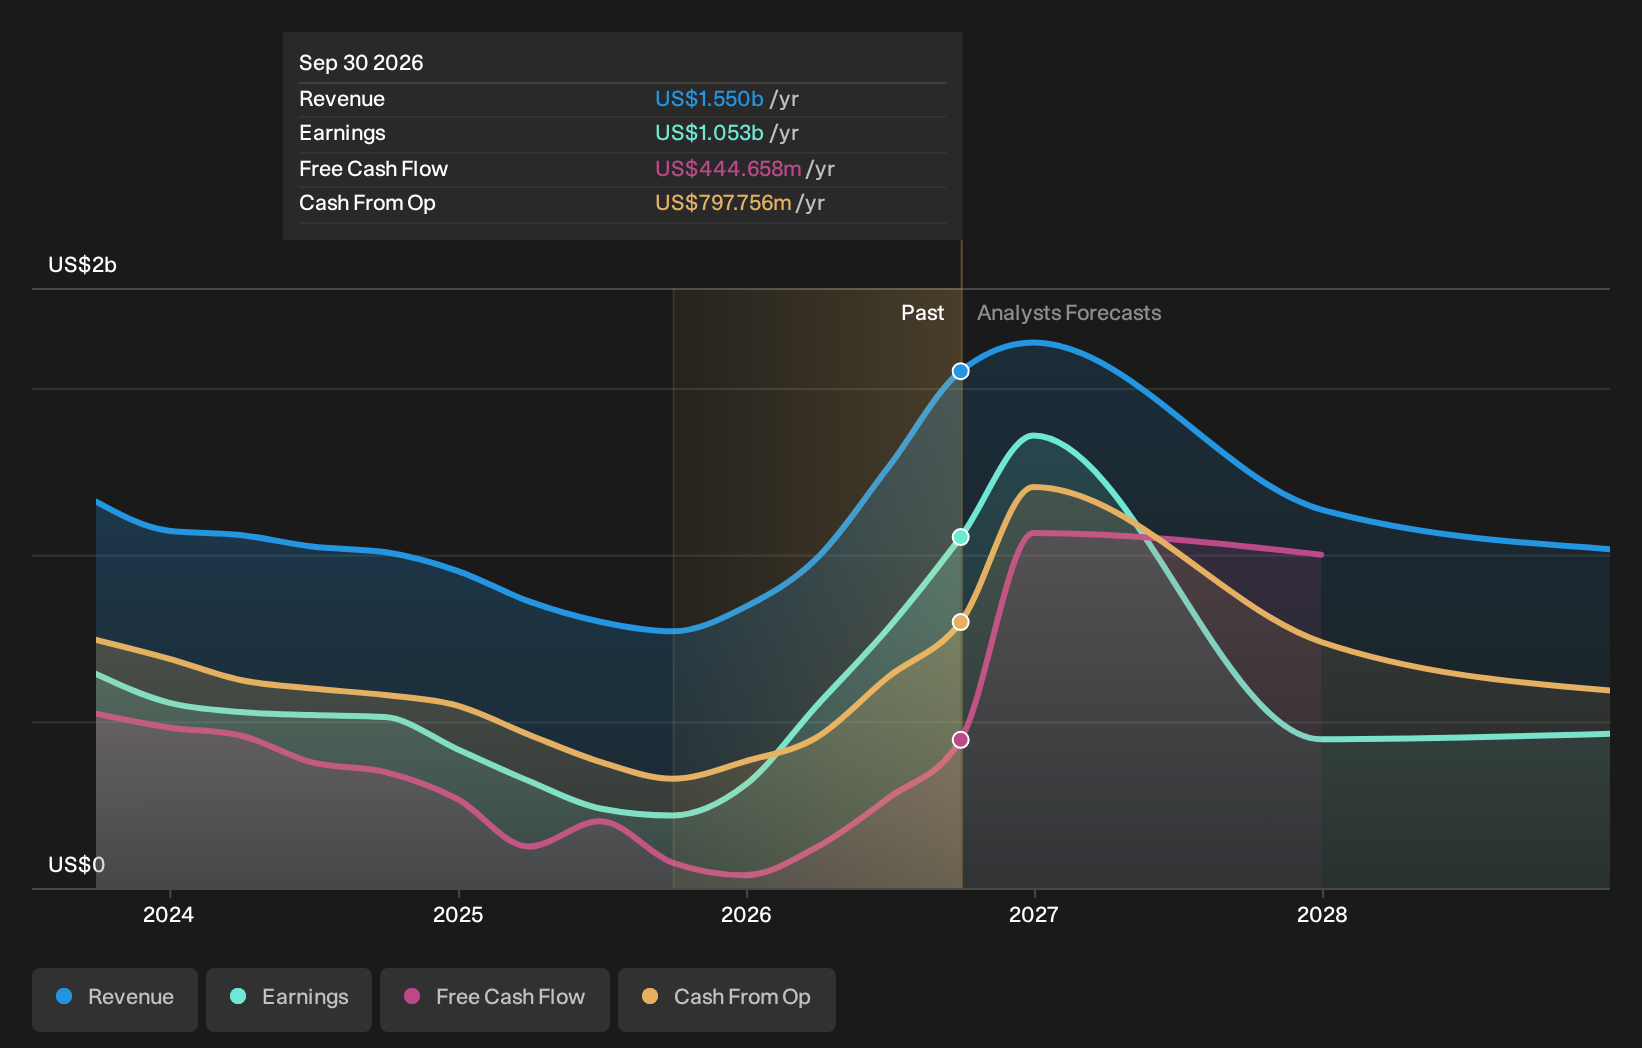
International Seaways operates a global fleet that hauls crude oil and refined products across international routes. This record-heavy quarter sits squarely in the middle of the energy transport chain, where vessel supply, charter demand and access to modern dual fuel ships can all influence how much cash the business generates.
Record quarter puts International Seaways’ high payout policy under the spotlight
The latest Q3 performance, paired with International Seaways’ US$5.05 dividend and enlarged buyback, leans directly into the Narrative catalyst around returning at least 85% of adjusted net income to shareholders. That reinforces the idea that management is comfortable sending a large share of current earnings out as cash, even while analysts model revenue and profit margins moderating over time. At the same time, the flagged risk around dividend sustainability and free cash flow coverage is now more front and center, because a richer regular payout raises the bar for how much future tanker cash generation needs to support.
See how these catalysts shape International Seaways' path to a $126 fair value.
If you are tracking whether this quarter really moves the story, focus on how the payout ratio and free cash flow coverage look in the next couple of earnings updates, once the Bruton fleet integration, LR1 deliveries and vessel sale gains settle into a more normalised run rate.
The question many International Seaways headlines skip
Quarterly updates tell you what International Seaways just earned, but a full model of future cash generation can also be used to estimate what the whole business might be worth compared with today’s share price. Find out exactly what International Seaways is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com