


EN
Frontdoor (FTDR) Could Be Fully Valued On Q3 Beat And $1b Buyback
Frontdoor (FTDR) just paired a strong third quarter earnings report with a fresh US$1b three year buyback plan, raised full year guidance, and evidence of steady membership and non warranty revenue momentum.
Frontdoor’s recent Q3 beat, higher guidance and fresh buyback have landed on a stock that already had strong momentum, with a 30 day share price return of 24.78% and a year to date share price gain of 70.21%.
Scan how Frontdoor’s earnings beat and buyback story compares with other companies on the move by reviewing our hand picked 19 high quality undiscovered gems across the market.
Frontdoor now trades close to analyst targets after a near doubling over the past year, supported by rising earnings and a US$1b buyback. Does that setup still reward new risk takers at this price?
Most Popular Narrative: 30% Undervalued
Frontdoor’s most followed narrative pins fair value at $97.40, almost exactly where the stock last closed at $97.09, yet still sees upside through cash generation and buybacks when looking out over several years using a 7.4% discount rate.
Expansion of non warranty offerings, with the HVAC upgrade program scaling from US$13 million to an expected US$170 million of annual revenue in four years and non warranty revenue growing more than 19% year over year in early 2026, gives Frontdoor a template to add further trades and increase total revenue and EBITDA.
See why 8 investors see Frontdoor as 0% undervalued.
Result: Fair Value of $97.40 (UNDERVALUED)
Still, the Frontdoor thesis leans on housing activity and discount heavy direct to consumer offers, so weaker sales or thinner pricing could quickly test that 30% undervalued narrative.
Find out about the key risks to this Frontdoor narrative.
Another View: Frontdoor On Earnings Multiples
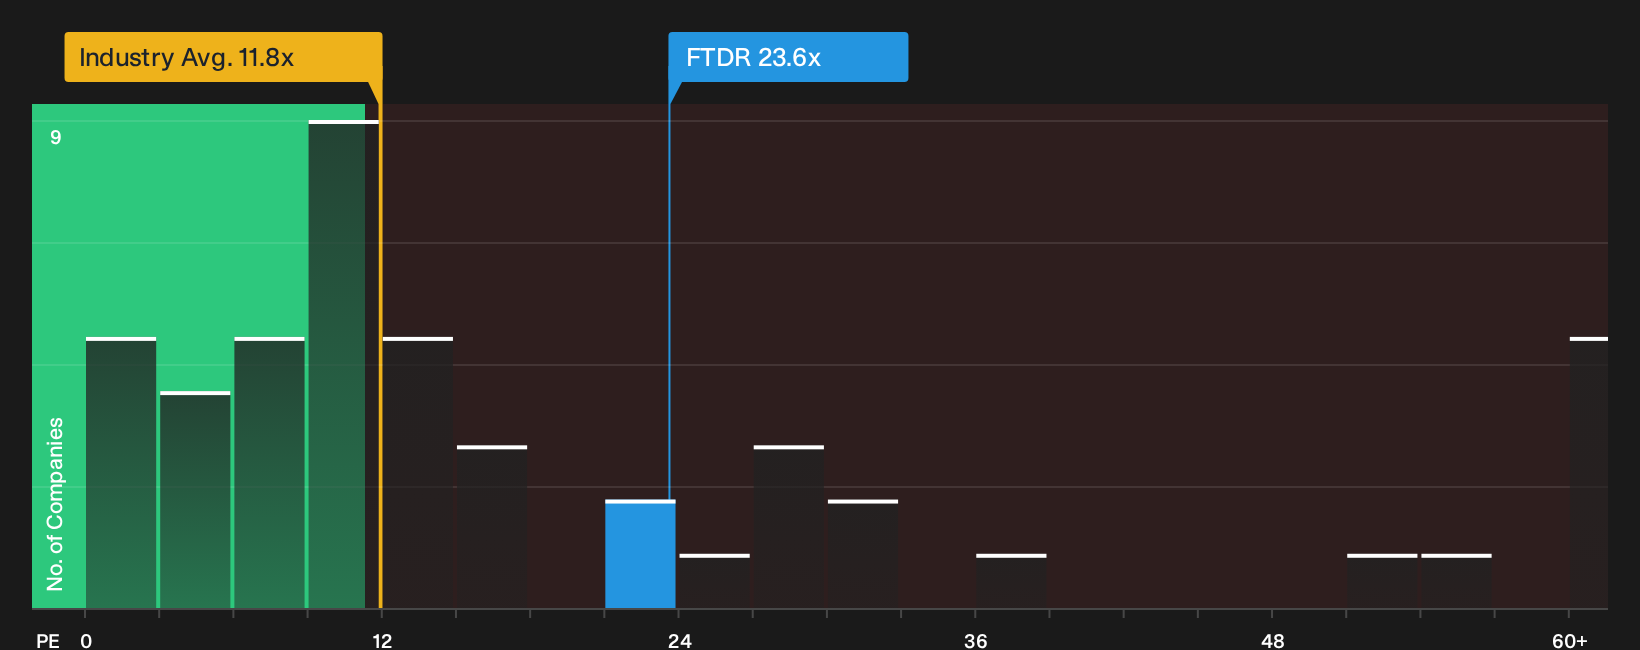
Frontdoor might look cheap on cash flow screens, trading about 44.1% below one estimate of future cash flow value, but its current P/E of 23.6x tells a different story. That is rich against the US Consumer Services industry at 11.6x, peers at 18.7x, and a fair ratio of 19.9x. Is the premium simply paying upfront for that narrative, or does it narrow the margin for error if growth underdelivers?
For a closer look at how this pricing gap could matter over time, and what the numbers imply for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Frontdoor’s setup, with both risks and rewards in play, mean the next move is yours. Pressure test the thesis yourself, then weigh up the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Frontdoor?
Frontdoor’s story can sharpen your thinking, but your next opportunity might be elsewhere. Use this momentum to broaden your watchlist with fresh candidates.
- Hunt for mispriced quality by scanning the market for companies that look cheap on fundamentals using our curated 39 high quality undervalued stocks.
- Build a more resilient portfolio by focusing on businesses that pair solid finances with staying power through the 29 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking emerging opportunities that many investors may overlook with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com