


EN
Acadia Healthcare (ACHC) Stock Trades Below Fair Value On Sales
Acadia Healthcare Company has surged in 2026, and with the stock up sharply, the key issue for you now is how well its current share price lines up with the sales the business is generating. The question is whether the recent move is grounded in the top line or is asking investors to pay a richer price for each dollar of revenue.
- The stock has returned about 158.9% year to date, which puts a lot of weight on whether the valuation tied to its sales can support that kind of move.
- Recent reports of higher revenue, added beds, and a shift toward expanding existing facilities may support expectations for future sales and cash generation, which feeds directly into how much investors might be prepared to pay for the company’s revenue base.
- The analysts covering Acadia Healthcare Company have run their own numbers. See what analysts think Acadia Healthcare Company's shares could be worth.
The issue now is whether Acadia Healthcare Company’s current share price is appropriately anchored to its sales, given the recent run and the latest business developments.
If you want to stress test this same sales based valuation question across a wider field of opportunities, compare Acadia Healthcare Company with 39 high quality undervalued stocks
Is Acadia Healthcare Company a Bargain on Sales?
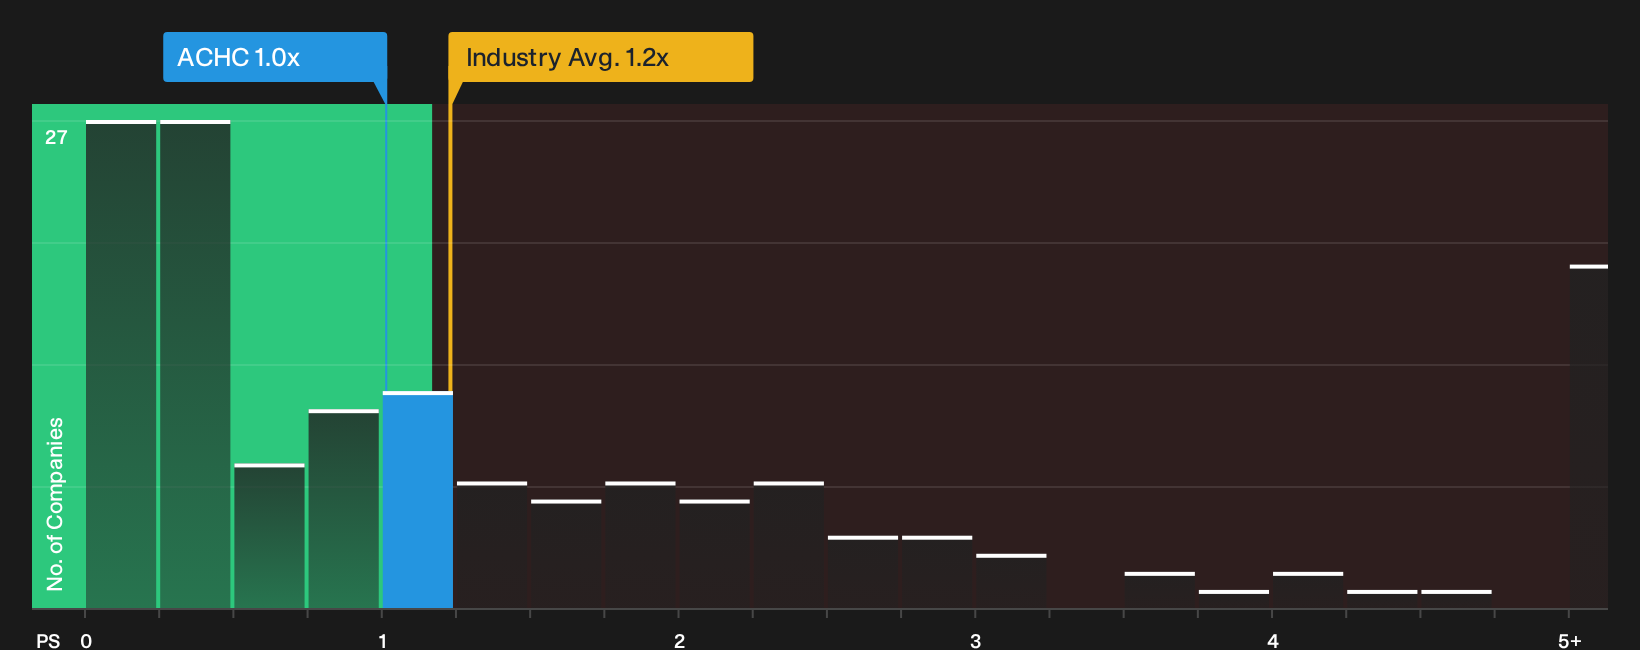
P/S suits Acadia Healthcare Company because investors often focus on how much they are paying for each dollar of revenue in healthcare services. On that score, the shares trade on a P/S of about 1.0x, which is very close to both the stated peer average of roughly 1.0x and the wider Healthcare industry level of about 1.2x. That keeps the revenue multiple in the same ballpark as comparable operators rather than at a dramatic premium.
The fair multiple our model would expect for Acadia Healthcare Company, based on its mix of growth prospects, margins, scale and risks, is higher than where the stock currently trades, so the current P/S screens as undervalued on this framework. Because management has raised 2026 guidance after reporting Q3 revenue of about $3.44b to $3.46b, this lower P/S tag comes despite fresher numbers that point to a larger sales base being valued at roughly the same revenue multiple as peers. Explore the numbers behind Acadia Healthcare Company's P/S valuation.
The Acadia Healthcare Company Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S puzzle for Acadia Healthcare Company leaves off. They spell out which paths for growth, profitability and earnings would need to play out for the current share price to look either conservative or stretched, and each view pins its number on a clear stance about where expansion, margins and risk move next. This gives you something concrete to revisit as fresh information comes through.
Community views on Acadia Healthcare Company are split between those focused on near term earnings power and those concerned about operational and regulatory strain.
Bull case: 10% undervalued
"Operational turnaround work under CEO Debbie Osteen, including portfolio reorganization, leadership changes, measurement based care, dashboards and early AI use in the revenue cycle…"
Discover why this Narrative puts Acadia Healthcare Company at 10% undervalued.
Bear case: 210% overvalued
"The biggest risk for Acadia is not demand, it’s execution. Behavioral healthcare is labor intensive, highly regulated, and dependent on skilled clinicians…"
Explore why this Narrative puts Acadia Healthcare Company at 210% overvalued.
Acadia Healthcare Company’s valuation still hinges on who is at the wheel
Before you stop at the multiple, you also need to know who is setting priorities inside Acadia Healthcare Company, how their incentives are structured, and whether those rewards truly line up with your interests. See who runs Acadia Healthcare Company and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com