


EN
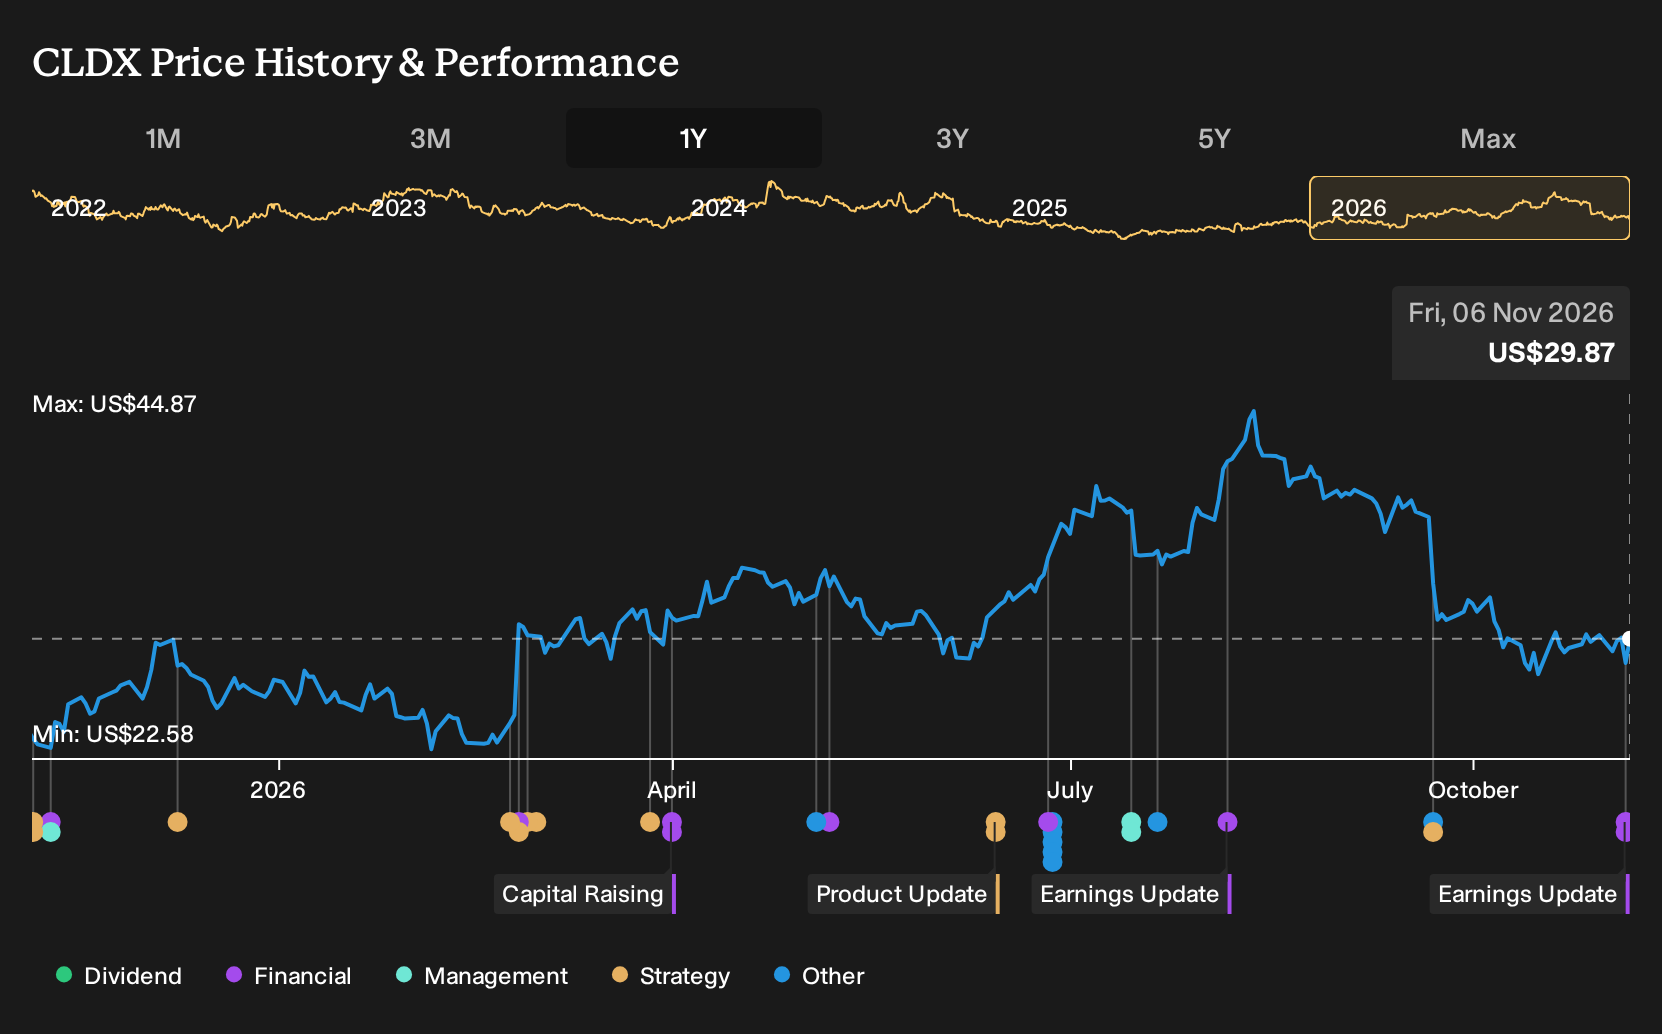
Why Celldex Therapeutics (CLDX) Is Up 5.7% And What's Next
- Celldex Therapeutics reported a wider quarterly and year to date loss but slightly lower loss per share, alongside very limited revenue, while also putting a universal shelf registration in place that covers common stock, preferred stock, warrants, depositary shares and units.
- During the same period, Celldex Therapeutics highlighted best-in-disease Phase 3 results for barzolvolimab in chronic spontaneous urticaria and indicated plans for a future BLA filing, reflecting a business that is absorbing heavy development costs today while positioning its mast cell portfolio for potential future commercialization.
- The next focus is how Celldex Therapeutics’ investment narrative may evolve as strong barzolvolimab data coincides with newly available shelf registration capacity.
Scan beyond Celldex Therapeutics and compare its risk and reward profile with hand-picked biotech peers using our 19 high quality undiscovered gems as a starting universe for further research.
Celldex Therapeutics Investment Narrative Recap
For a shareholder in Celldex Therapeutics, the core belief is that heavy current spending on barzolvolimab and the broader mast cell portfolio eventually supports a larger commercial business. The latest quarter underlines how far away that is in pure financial terms. Net loss widened to US$75.56 million in Q3 and US$227.75 million for the first nine months, against very limited revenue.
In the short term, the key catalyst still sits with regulatory progress and execution around barzolvolimab in chronic spontaneous urticaria. The earnings release and wider loss do not change that focus, but they sharpen the funding question. The combination of large ongoing losses and minimal top line keeps dilution and balance sheet strength as the biggest near term risk.
The universal shelf registration that Celldex Therapeutics filed is the announcement to watch in this context. It gives the business flexibility to issue common stock, preferred stock, warrants, depositary shares and units. That toolkit matters for a company running sizeable quarterly losses while preparing for a potential commercial build out.
For you as an investor, the shelf ties directly into the catalyst and risk mix. It supports continued investment in barzolvolimab trials and future launch work, which is central to the story, yet it also raises the ongoing possibility of additional equity issuance and ownership dilution. The trade off is between funding pipeline execution and the impact on each existing share.
Celldex Therapeutics’ analyst narrative assumes revenues of $311.0 million and earnings of $53.6 million by 2029, based on an implied very large yearly revenue growth rate of 1,153.2% and an earnings change of roughly $354 million from a loss of $300.5 million today to positive earnings in the forecast period.
Uncover why Celldex Therapeutics' fair value indicates a 111% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Celldex Therapeutics focuses on barzolvolimab’s potential to support longer treatment courses, rather than just one-time symptom control. The most optimistic analysts were modeling about US$383.1 million of revenue and US$65.9 million of earnings by 2029, far above consensus. Those projections predate this earnings and shelf news, so your own view may shift as new information lands.
Explore 3 other Celldex Therapeutics fair value estimates, including one that suggests as much as 255% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Celldex Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Celldex Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celldex Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Celldex Therapeutics?
If you want to put Celldex Therapeutics in context, it helps to scan a wider field of opportunities. Use the Simply Wall St Screener to line up companies by quality, risk level, and balance sheet strength, then dig deeper into the ones that fit your own approach.
- If capital preservation is a priority, start with sturdier businesses that may handle shocks better by reviewing our 29 resilient stocks with low risk scores.
- If you care most about financial resilience, compare Celldex Therapeutics with companies that have stronger cash and debt positions through this list of solid balance sheet and fundamentals (24 results).
- If you want to get ahead of the crowd, scan a focused universe of under followed opportunities with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com