


EN
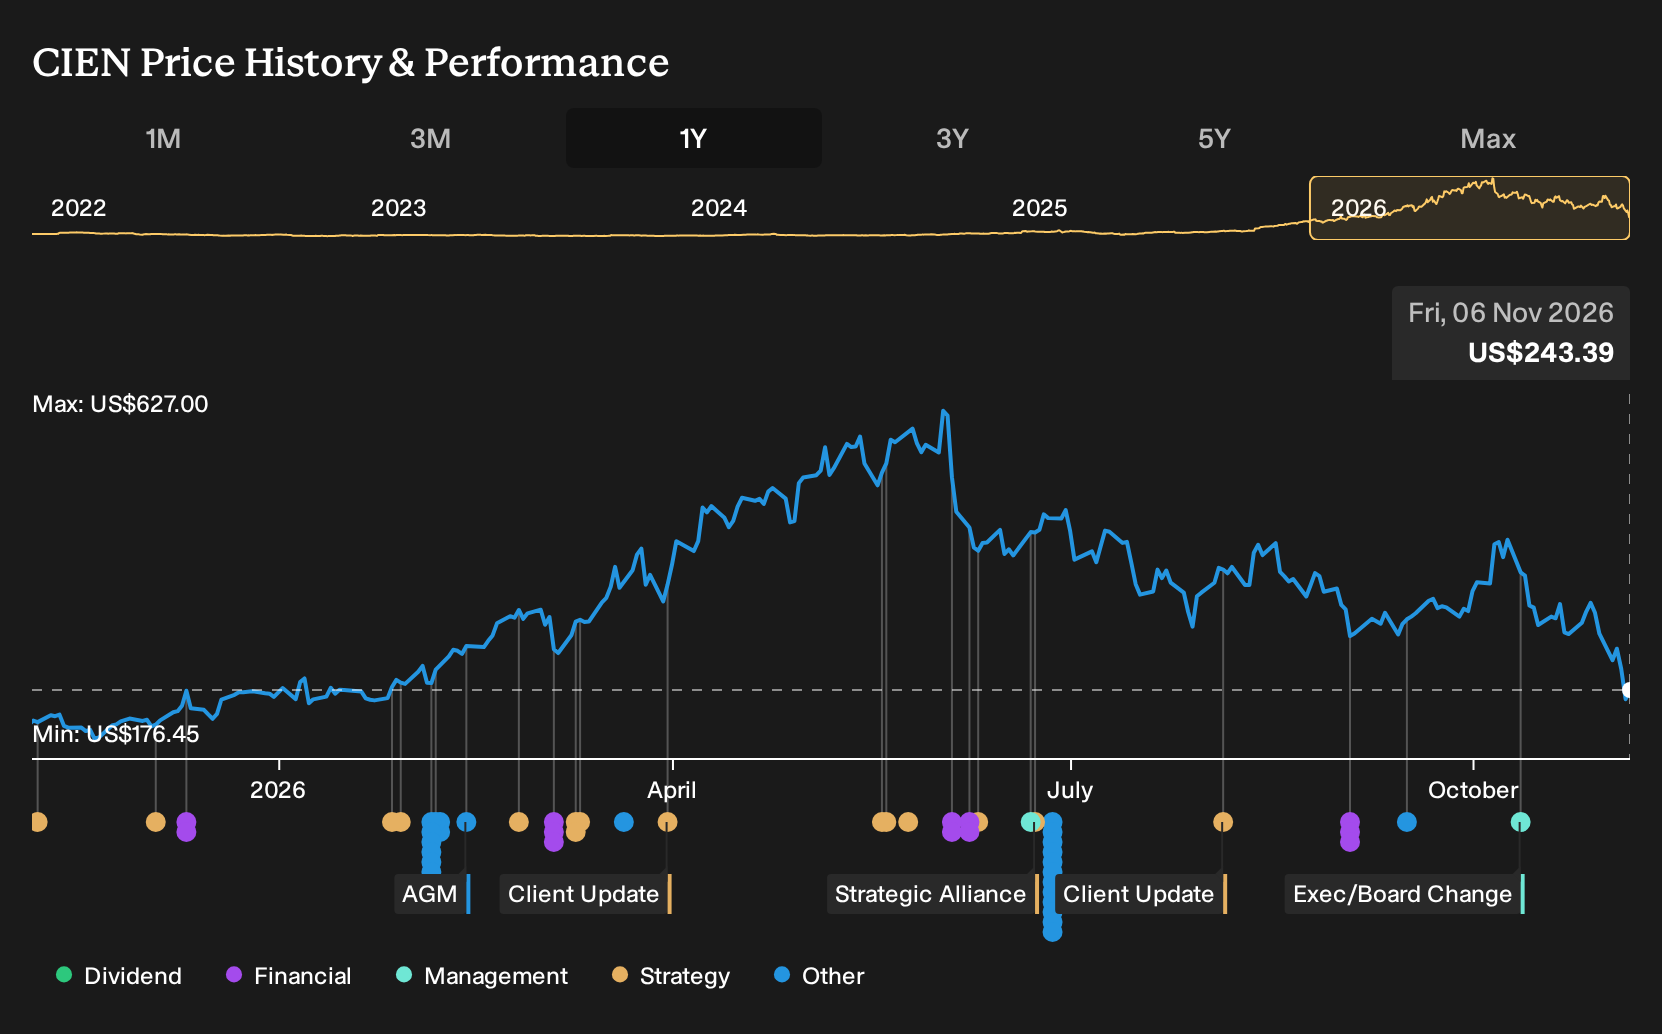
Ciena Stock Revenue Growth Meets A Bigger Backlog Test
- Ciena recently reported strong revenue performance alongside a sizable increase in backlog for its optical networking solutions, with earnings still feeling the impact of supply constraints and margin pressure.
- The combination of solid demand, expanding backlog, and stressed profitability puts execution on component supply and margin recovery at the center of Ciena’s operating story.
- We will look at how Ciena's investment narrative is shaped by strong backlog growth while profitability remains pressured by component supply limits.
Scan how Ciena’s supply constraints and backlog story compares with other infrastructure plays by checking out hand picked 52 AI infrastructure stocks shaping the next phase of network capacity upgrades.
Ciena Investment Narrative Recap
Ciena attracts shareholders who buy into a simple idea. Strong demand from hyperscalers and carriers feeds a large optical backlog, and the real test is turning that order book into cleaner earnings and cash. The recent update reinforces that demand is there, while reminding you that component availability still sets the ceiling.
In the near term, the main catalyst is progress on supply agreements and manufacturing throughput so more of that backlog ships at healthier margins. The biggest risk is that supply constraints linger or key hyperscaler customers trim spend, which would keep profitability under strain even with a full pipeline.
With no fresh company announcements tied directly to this update, the most relevant context is still Ciena’s push around its optical platforms and automation portfolio. The backlog commentary sits on top of that, because these are the systems large cloud providers are already standardising on for high capacity, low latency links.
For investors, the operational question is straightforward. Can Ciena keep winning hyperscaler projects and AI data center interconnect work, and then deliver those systems at the margin levels management has discussed? Execution on supply, pricing, and cost control will influence how today’s order book converts into steadier earnings.
Ciena's current analyst blueprint points to forecast revenue of US$13.0b and earnings of US$3.0b by 2029, based on assumptions of 29.4% yearly top line growth. Earnings are expected to rise from US$654.4m today to US$3.0b, which is roughly a 4.6x increase.
Uncover why Ciena's fair value indicates a 111% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Ciena emphasizes the risk that AI related optical demand cools faster than expected. Those lowest analysts were pencilling in revenue of about US$10.5b and earnings of US$1.6b by 2029, far below consensus. That is a much more cautious story. Opinions clearly span a wide range, so explore both perspectives before deciding how this fresh backlog news might reshape your own narrative.
Explore 4 other Ciena fair value estimates, including one that suggests it could be worth just $347.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Ciena research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ciena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ciena's overall financial health at a glance.
Looking For More Ideas Beyond Ciena?
If this Ciena story has sharpened your thinking about demand, backlog, and execution risk, it can help to set it alongside other situations where the numbers and balance sheets look very different. The Simply Wall St Screener lets you scan for companies that match the kind of risk, quality, or income profile you want to research next.
- If you want potential upside with stricter quality filters, sort for higher quality businesses trading on what may be more modest valuations using 39 high quality undervalued stocks.
- For readers who care most about resilience and capital preservation, narrow your search to companies with steadier fundamentals through 29 resilient stocks with low risk scores.
- If you prefer stronger balance sheets and cleaner fundamentals to support your own research, start with a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com