


EN
ERAMET (ENXTPA:ERA) Dropped, So What Is Driving Attention Now?
ERAMET (ENXTPA:ERA) just put fresh production numbers on the table, with lithium carbonate volumes jumping while mineral sands, ilmenite, and zircon output moved the other way in the latest quarterly update.
Despite the fresh lithium update, ERAMET’s share price has been under pressure, with the stock down 18.1% over the past 30 days and 39.6% year to date. The 1 year total shareholder return has fallen 29.9%, pointing to fading momentum as investors reassess both growth potential and operational risk.
Scan other materials producers that are facing similar cross-currents in volumes and sentiment with a curated set of 33 best rare earth metal stocks that share some of ERAMET’s exposure to critical resources.
ERAMET now trades at a discount to analyst targets even as the business reports a loss and mixed production trends. Is the market simply too cautious, or are investors pricing the risk correctly?
Price-to-Sales of 0.4x: Is It Justified for ERAMET?
On simple sales-based metrics, ERAMET screens as inexpensive, with a P/S ratio of 0.4x at a last close of €37.18 while analysts still see upside from here based on their targets.
The P/S ratio compares the market value of the equity to its annual revenue, so a lower figure means investors are paying less for each euro of turnover. For a producer of manganese, nickel, lithium, and mineral sands with cyclical earnings, using sales rather than profits helps sidestep the current loss of €520.0m and focus on the scale of the underlying operations.
Based on Simply Wall St checks, ERAMET is considered good value on this metric compared both to peers at 1.4x and to the wider European metals and mining group at 1x P/S. That is a large gap. The estimated fair P/S ratio of 1.9x is even higher, which signals a level the market could move towards if sentiment around earnings quality, balance sheet risk, and future profitability improves.
Explore the SWS fair ratio for ERAMET.
Result: Price-to-Sales of 0.4x (UNDERVALUED)
Still, ERAMET faces real pressure if losses persist or if manganese, nickel, and lithium prices weaken further, which could keep investor confidence subdued.
Find out about the key risks to this ERAMET narrative.
Another View on ERAMET’s Valuation
The low P/S of 0.4x paints ERAMET as cheap, yet the SWS DCF model tells a different story. On that framework, the estimated future cash flow value sits at €31.33 per share, while the stock trades at €37.18, which screens as overvalued rather than discounted. So which lens should investors use for a cyclical miner with lumpy earnings and heavy capital needs?
Look into how the SWS DCF model arrives at its fair value.
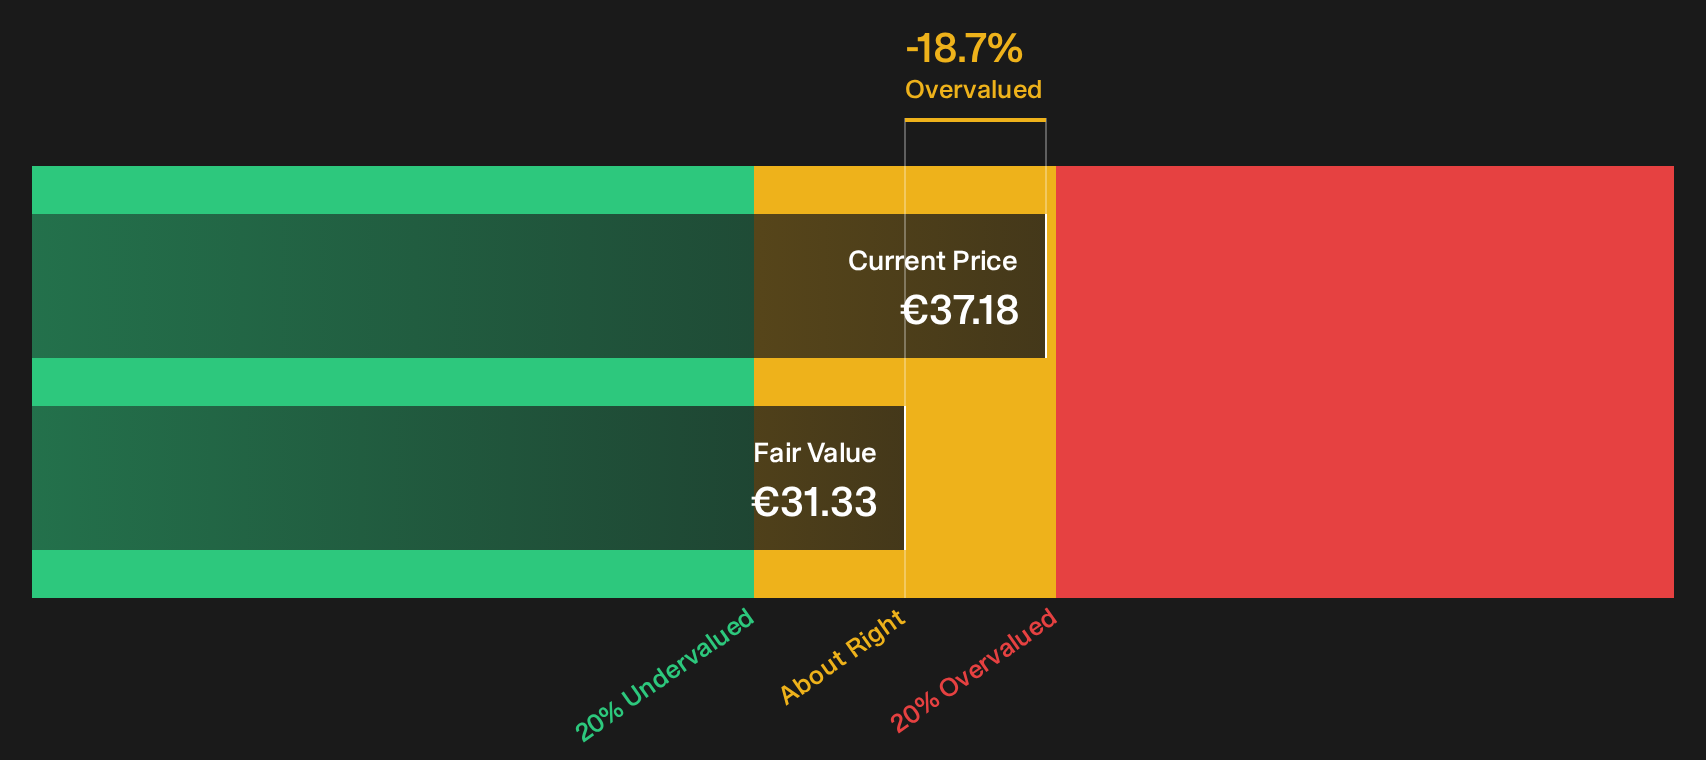
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ERAMET for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 224 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ERAMET can make the situation seem unclear. Act promptly, review the underlying data, and weigh both the potential upsides and the clear pressure points using the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond ERAMET?
If ERAMET has sharpened your focus on value and risk, use that momentum to uncover fresh ideas that fit your own approach before the next opportunity passes by.
- Target quality at a discount and review a curated 224 high quality undervalued stocks that balances pricing with business strength.
- Prioritise stability and assess a 212 resilient stocks with low risk scores that focuses on companies with more resilient profiles.
- Spot potential early and scan a 588 high quality undiscovered gems that highlights stocks with strong fundamentals that fewer investors are watching.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com