


EN
Chemed (CHE) Stock May Be 28% Undervalued Despite VITAS Billing Questions
Chemed has delivered a 24.6% gain year to date, even as fresh headlines around its VITAS hospice unit and recent profit performance keep investors focused on what really supports the share price: its cash flows. With the stock now trading near US$528, the question is whether the current market value lines up with what the underlying businesses are expected to generate in cash.
- The 24.6% year to date rise puts real weight on whether Chemed's current share price can be explained by its future cash generation rather than momentum alone.
- Recent reports on hospice enrollment practices at VITAS and profit contributions from both VITAS and Roto-Rooter may affect how durable and predictable Chemed's cash inflows look to investors.
- If you'd rather focus on earnings, this one's for you. See why Chemed's 24.2x P/E tells a different valuation story.
The issue now is whether Chemed's current valuation is justified by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
To pressure test whether Chemed's cash flow profile still stacks up cleanly against others after this kind of headline risk, it can help to line it up beside 29 resilient stocks with low risk scores.
Does Chemed Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach used here projects what Chemed could return to shareholders in cash over time and then discounts it back to today. In this model, Chemed is treated as a business with established, positive free cash generation rather than a high risk turnaround story.
The latest twelve month free cash flow is about $301.5 million, with the DCF using a path of gradually growing cash flows through the next decade before moving into a steadier phase. That profile, combined with the current share price of $528.05, leads the model to an estimated intrinsic value that is meaningfully above where the stock trades. The recent investigation into VITAS enrollment and billing practices helps explain why the market might still price Chemed below what these cash flow projections support. Find out what Chemed could be worth using our Discounted Cash Flow (DCF) estimate.
The Chemed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation gap around Chemed and turn it into clear, explicit assumptions about future growth, profitability and earnings that would need to hold for the stock to be worth materially more or less than it is today on the screen. Each narrative treats Chemed's implied fair value as a hypothesis about how the business might perform that can be revisited over time, rather than as a one off snapshot.
One of the top community narratives on Chemed: 22% undervalued
"This narrative explores a more optimistic perspective on Chemed compared to the consensus, based on a Fair Value that aligns with the bullish cohort of analysts..."
Discover why this Narrative puts Chemed at 22% undervalued.
One more Chemed signal worth checking before you move on
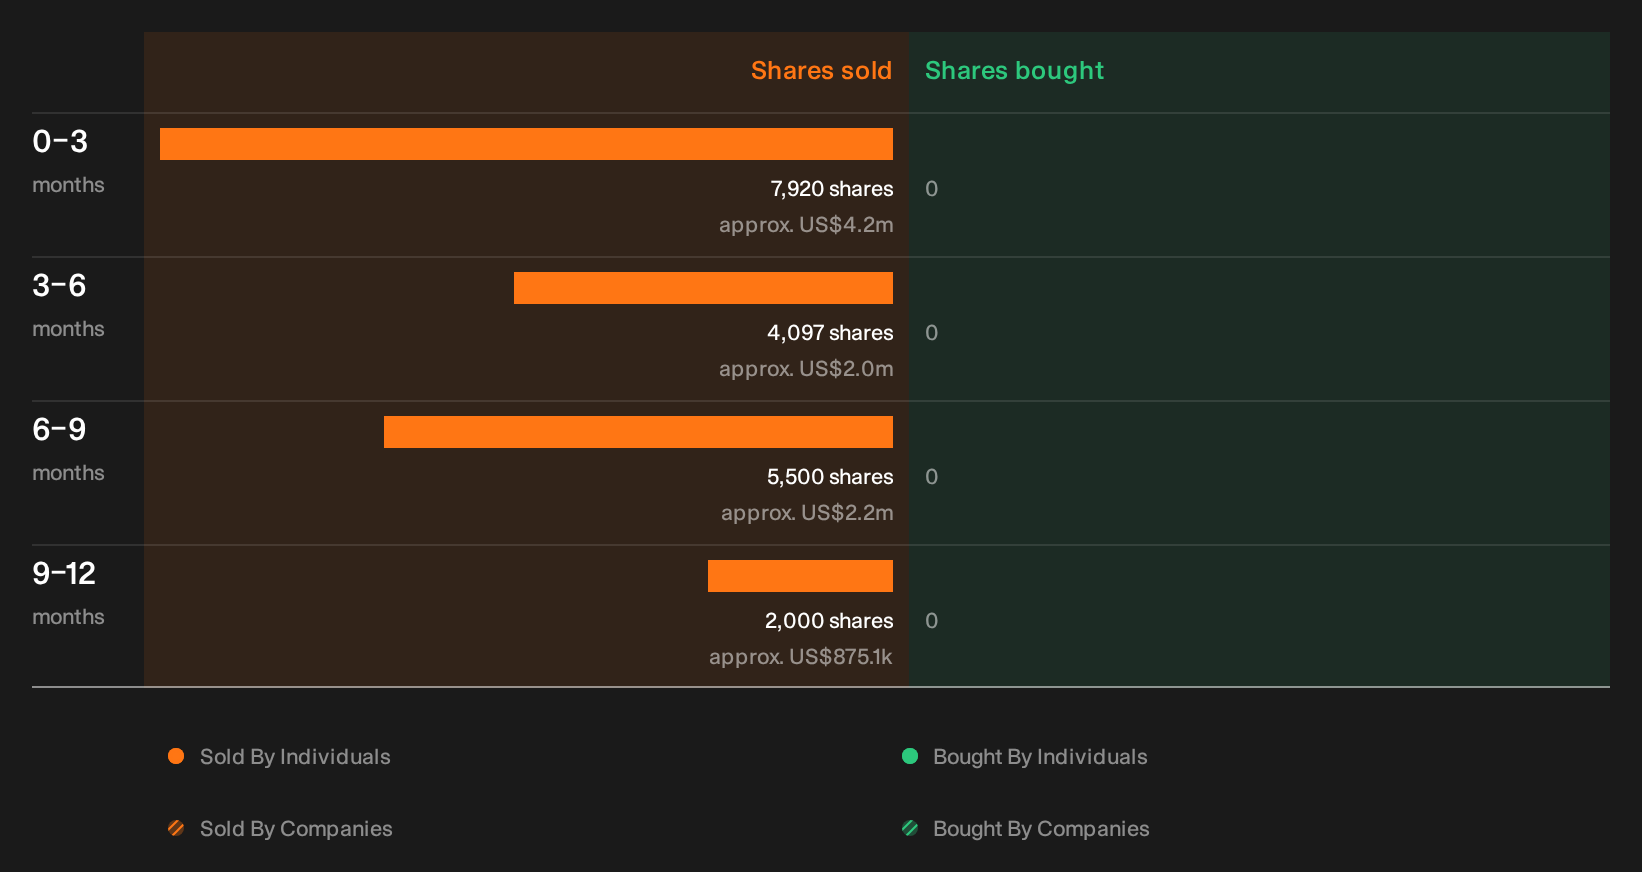
Before you lean too heavily on the cash flow story, it is worth knowing that recent trading by people inside Chemed has been flagged by our checks, with who sold, how much, and what it might suggest still to explore. See the recent insider selling flagged for Chemed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com