


EN
The Call Lincoln Electric Bulls Got Right
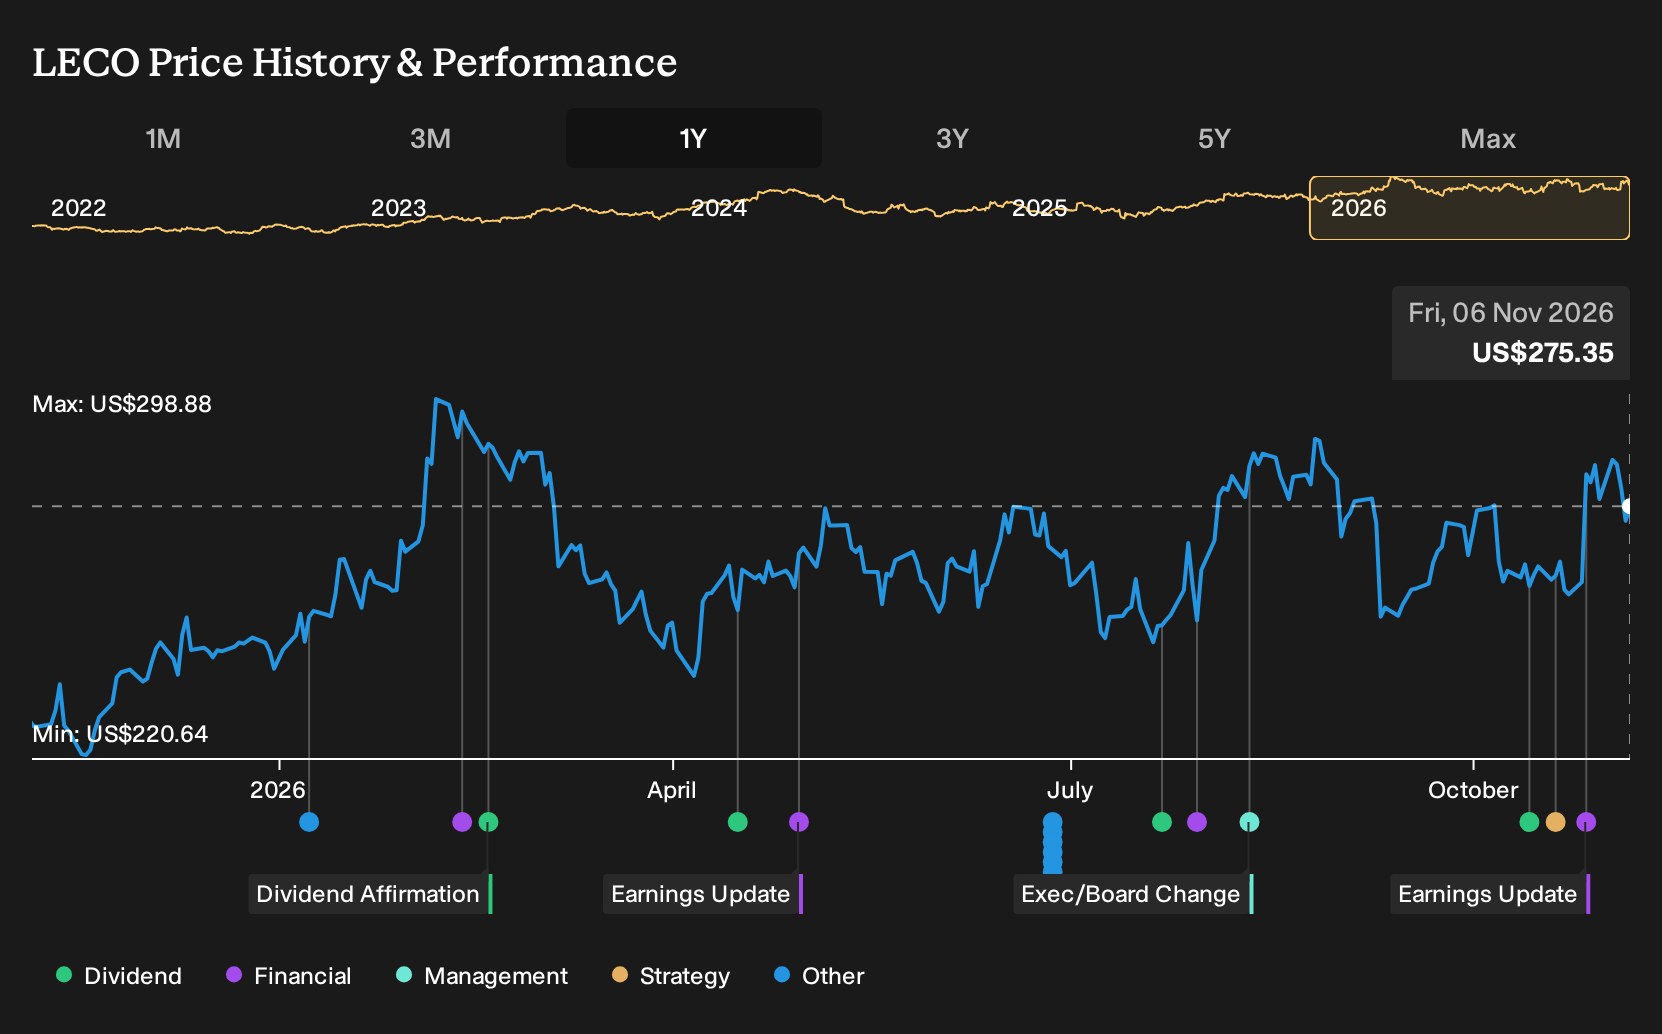
If you only glanced at the headlines, Lincoln Electric looked torn between two stories in late 2025. One bullish report argued accelerating automation and reshoring could justify a higher valuation, while a bearish view warned that legacy welding exposure and cyclicality might cap upside. Holding Lincoln Electric over the past year would have returned 22.9%, including dividends. If you had put capital to work then, what did the available evidence really suggest about that trade off between automation promise and welding cyclicality?
This theme extends beyond Lincoln Electric. See which of 89 robotics and automation stocks may still merit a closer look.
The Two Lincoln Electric Stories Investors Had To Weigh
The shares cost US$227 at the start of the period, and Lincoln Electric sat between two believable stories about what you were really buying.
The bullish view saw a fair value of US$256, based on assumptions that automation demand, 5.4% revenue growth, and a 13.8% profit margin would justify a future P/E of 24.9x over about three years.
The bearish narrative pointed to a fair value of US$185, stressing reliance on traditional welding, exposure to cyclical sectors, and pressure from automation shifts and regulation as key risks to long term margins.
What The Results Changed For Lincoln Electric
Record Q1 2026 sales of US$1.12b and later Q3 2026 revenue of US$1,221.3m, with profit rising to US$144.3m and net margin edging up to 11.8%, gave Lincoln Electric fresh support for the automation led bullish case. Evidence of overvaluation worries and insider selling meant the period still cut both ways rather than settling the debate.
The key assumption investors needed to test was whether automation and new platforms like XpertLINC could offset welding cyclicality. For a different stock with a similar story, it may help to track segment level automation revenue, reported margins, and any guidance tied specifically to automation rather than relying on headlines or analyst targets.
What Lincoln Electric’s Price Already Demands
Today Lincoln Electric trades at US$275 after returning 22.9% over the past year, and the selected Narrative’s Fair Value sits below that quote rather than above it.
The Narrative hinges on how much of the welding and automation story is already embedded in the valuation. A buyer at today’s level would need confidence that execution on RISE, automation adoption, and Asia expansion offsets any pressure from industrial slowdowns and inflation.
"The current valuation implies that Lincoln Electric shares already price in continued mid single to high single digit organic growth, high 20s incremental margins, and successful bolt on M&A execution, which leaves limited room for disappointment if these ambitions are not fully achieved."
One Narrative disagrees with today's price. → See where this Narrative says Lincoln Electric should trade
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 48% below our estimate - uses a digital lending platform and business checking tools to deepen small business relationships.
- Company 2 - 20% below our estimate - supplies engineered power equipment that grid, data center and offshore projects now require for electrification builds.
- Company 3 - 23% below our estimate - builds capacity for incretin therapies while adding oncology and neuroscience drugs as extra revenue pillars.
Three companies from the same screener. Open the full list of 39 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com