


EN
Selective Insurance Group (SIGI) Stock Looks Reasonably Priced On Earnings Support
Selective Insurance Group has quietly turned in a solid run, and that puts a spotlight on whether the current share price lines up with what its earnings can realistically support. With the stock still near recent highs, the question is how much of that move is grounded in the underlying profit engine of the business.
- Over the past 5 years the stock has returned 34.0%, which raises the question of whether earnings power has kept pace with investor enthusiasm built into the price.
- The insurer’s business model relies heavily on underwriting discipline and investment income, so any shift in claim trends or portfolio yields can materially change how much earnings support the current valuation.
- The analysts covering Selective Insurance Group have run their own numbers. See what analysts think Selective Insurance Group's shares could be worth.
For investors, the debate is whether Selective Insurance Group’s current share price is fully supported by the earnings it generates today and is expected to produce over time.
If you are weighing whether Selective Insurance Group’s recent 34.0% five year return is well grounded in its earnings, it can help to compare it with 29 resilient stocks with low risk scores.
Where Does Selective Insurance Group Sit on Earnings?
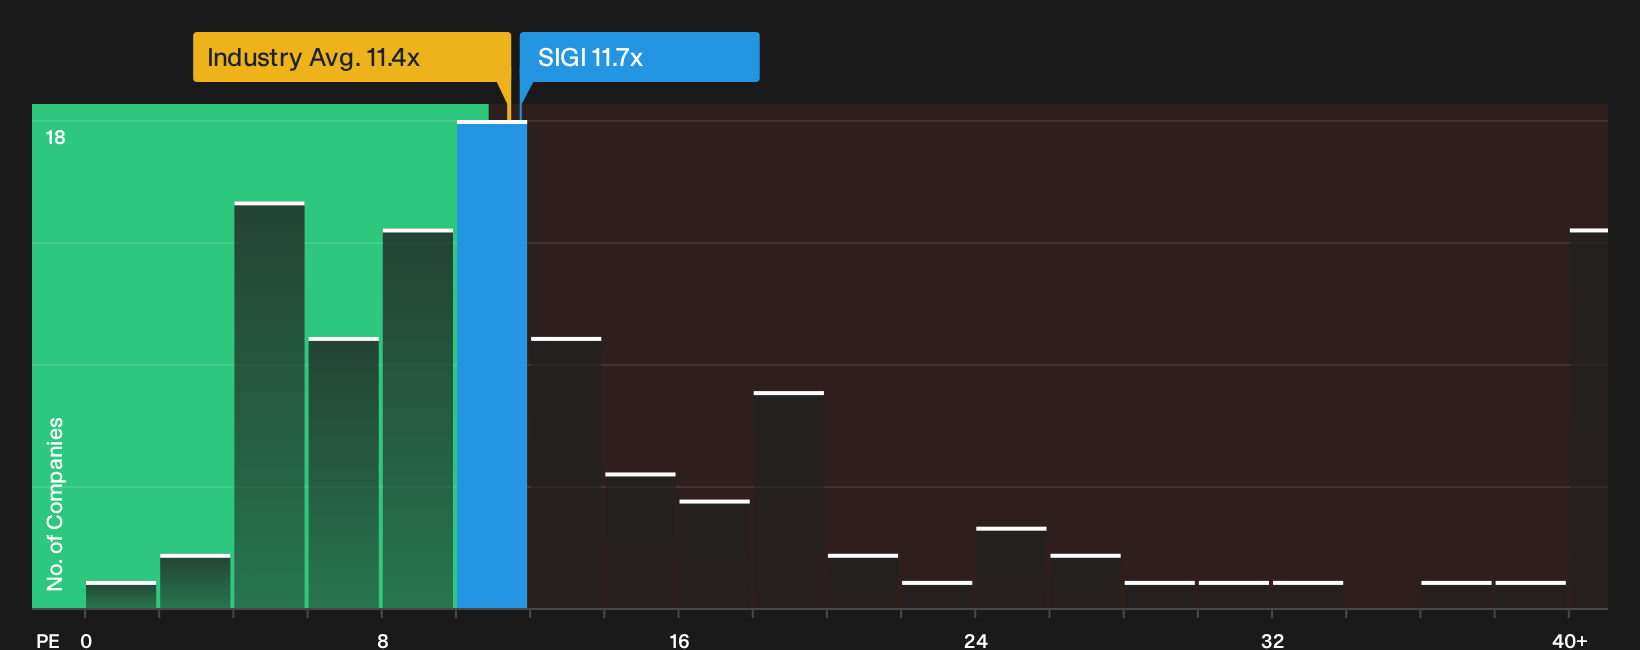
The P/E ratio fits Selective Insurance Group well because earnings quality and underwriting discipline usually sit at the center of how insurers are judged. On this measure, the stock trades on roughly 11.7x earnings, which is close to both the Insurance sector average of about 11.4x and the peer group around 9.5x. That cluster suggests the market is not assigning a dramatic premium or discount solely on headline earnings.
The valuation model that blends the company’s return on equity, book value base and analyst earnings expectations points to a fair multiple that is close to where Selective Insurance Group trades today. The current P/E sits only slightly away from that tailored reference point, so the share price appears largely in line with what the model suggests for a business with this profitability profile and risk level. For anyone weighing an entry or exit, the key question is whether the earnings stream that underpins that 11.7x remains as resilient as the model assumes. Explore the numbers behind Selective Insurance Group's P/E valuation.
The Selective Insurance Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Selective Insurance Group and spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on the Community page. Where a single ratio or valuation model offers one number, Narratives unpack the future conditions that number relies on so you can watch how closely real outcomes track those assumptions.
One of the top community narratives on Selective Insurance Group: roughly fairly valued
"The main thing that has to go right is that Selective Insurance Group continues to successfully re underwrite weaker books, manage social inflation…"
Discover why this Narrative puts Selective Insurance Group at roughly fairly valued.
Before acting on Selective Insurance Group’s valuation, there is one more factor to check
The people steering Selective Insurance Group and the way their pay packets are structured can either reinforce or undermine the earnings story that supports the current share price. See who runs Selective Insurance Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com