


EN
FirstEnergy (FE) Stock May Be Near Fair Value Following Strong Q3 Earnings
FirstEnergy has delivered a solid multi year share price run, and with fresh investment plans and grid projects in the headlines, the real question for you now is whether the current valuation still lines up with its earnings power.
- Over the past 3 years, FirstEnergy has returned 48.8%, which puts the spotlight squarely on whether that gain is fully backed by the profits the utility is generating today.
- Recent transmission and data center related investment plans can support expectations for future earnings, but they also point to higher capital needs that matter for how you judge the stock on an earnings basis.
- There is a second opinion on FirstEnergy worth weighing. See what analysts think FirstEnergy's shares could be worth.
The issue now is whether FirstEnergy's share price around US$46 reflects an earnings profile that still looks justified when set against what the business is producing today.
If you want a broader watchlist alongside FirstEnergy while you think through this earnings question, a focused screen of 42 power grid technology and infrastructure stocks.
Where Does FirstEnergy Sit on Earnings?
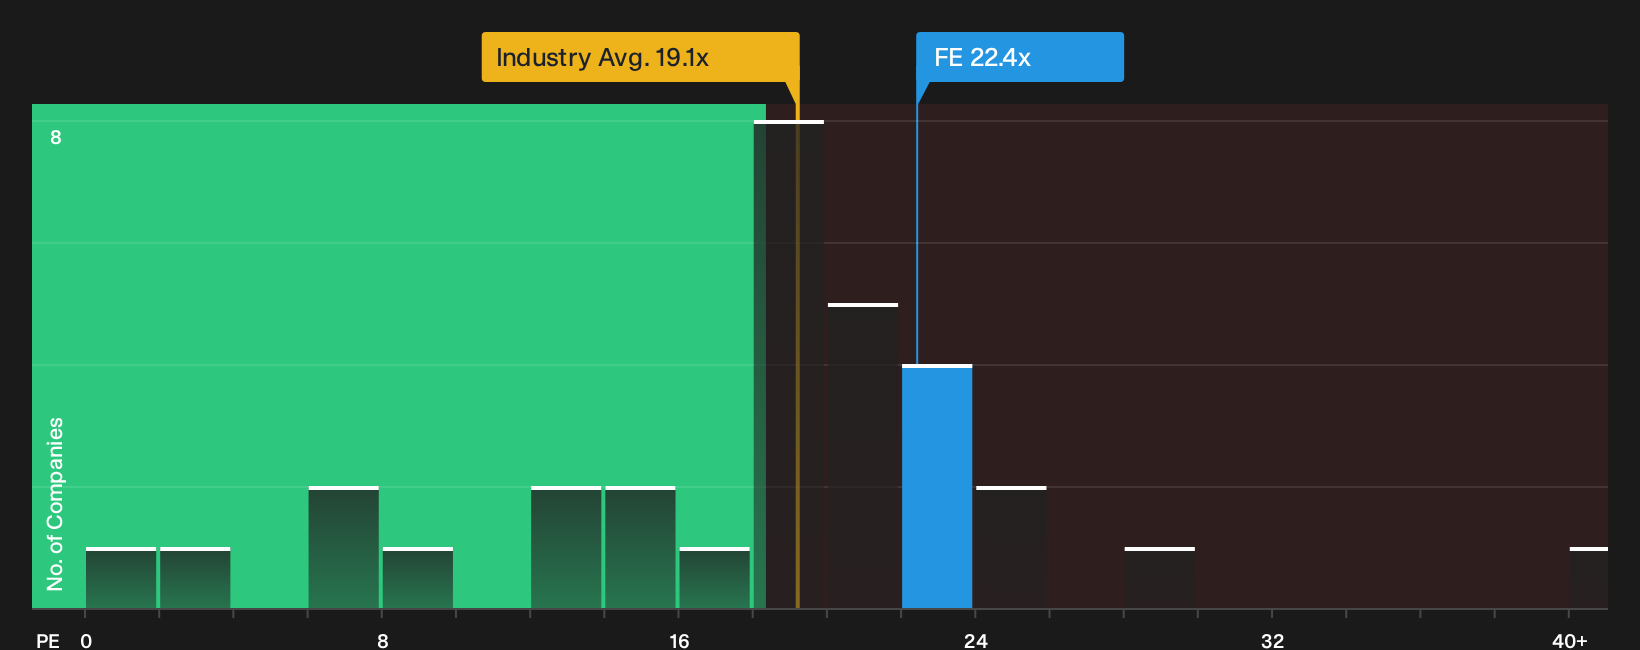
The P/E ratio is a useful anchor for a regulated utility like FirstEnergy because earnings often track the allowed returns on its asset base. At around 22.4x, FirstEnergy trades above the Electric Utilities group, which sits near 19.1x, and also above the peer average of roughly 13.7x. That points to investors paying a premium earnings multiple compared with many other listed power providers.
The gap looks more measured once you compare it with the tailored fair multiple that blends FirstEnergy’s growth profile, margins, size, and risk, where the current P/E lands close to that reference point. Recent Q3 2026 results, with earnings ahead of expectations and a reinforced capital plan tied to data center demand and transmission upgrades, help explain why the market is comfortable keeping the stock on this kind of footing. For you as a shareholder or potential buyer, the key question is whether those planned projects and regulated returns continue to justify paying a mid 20s earnings multiple for FirstEnergy. Explore the numbers behind FirstEnergy's P/E valuation.
The FirstEnergy Narrative: What Would Justify Today's Price?
Narratives for FirstEnergy pick up where the valuation question leaves off by spelling out which future paths for growth, profitability, and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today on Simply Wall St's Community page. Each one presents FirstEnergy's implied fair value as a specific thesis about the business that you can monitor over time as new information arrives.
One of the top community narratives on FirstEnergy: 10% undervalued
"The current valuation implies investors are not fully pricing in the earnings contribution from the planned US$36b capital program and the incremental opportunities tied to rising data center demand..."
Discover why this Narrative puts FirstEnergy at 10% undervalued.
One more piece of the FirstEnergy puzzle to check
Before you get too comfortable with how FirstEnergy is priced on earnings alone, it is worth seeing what the broader fundamental checks have flagged about the business and why those signals could matter for your risk view. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com