


EN
Did Return To Profit Just Shift Equitable Holdings (EQH) Investment Narrative?
- Equitable Holdings reported third quarter 2026 revenue of US$3,881 million compared with US$1,450 million a year earlier and moved from a net loss of US$1,309 million to net income of US$1,121 million, with nine month revenue of US$9,769 million and net income of US$1,289 million replacing a prior loss of US$1,595 million.
- The swing from losses to profit across both the quarter and year-to-date period points to meaningful changes in Equitable Holdings' earnings drivers, including how its product mix, investment results and costs are feeding through to reported performance.
- We will now look at how this return to profitability at Equitable Holdings could shape the longer-term investment narrative around the business.
Scan how Equitable Holdings’ earnings shift compares with other insurers turning recent results into fresh momentum by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Equitable Holdings Investment Narrative Recap
To own Equitable Holdings, you need to believe the business can turn its recent return to profit into something consistent while managing product mix, costs and investment returns. The latest quarter, with revenue of US$3,881 million and net income of US$1,121 million, supports that case but does not settle it. In the short term, integration of new products and the balance between fee based and spread driven lines looks like the key swing factor.
The biggest near term risk sits in the same place. If the shift away from higher margin legacy products and toward alternatives or newer annuity designs leads to thinner economics, earnings could prove less resilient than this quarter suggests. Investors are essentially weighing whether this profitability is repeatable or unusually strong.
The most relevant recent development is the sustained move back into the black over the first nine months of 2026. Equitable Holdings reported US$9,769 million of revenue for the period and net income of US$1,289 million. That change in profitability matters because the broader thesis already hinges on fee heavy retirement, wealth and asset management earnings doing more of the heavy lifting.
This shift in results now needs to be seen against known risks around legacy RILA runoff, alternatives performance and past GAAP revenue pressure in early 2026. Any wobble in alternative asset returns or slower individual life and retirement flows would test how much cushion the new earnings mix really provides. Execution on cost control and capital allocation will likely decide whether the recent numbers become a base or a high watermark.
Equitable Holdings' narrative projects US$18.3b revenue and US$2.3b earnings by 2029. This implies revenue growth of 19.8% per year and requires an earnings increase of about US$3.3b from earnings today of a US$982.0m loss.
Uncover why Equitable Holdings' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
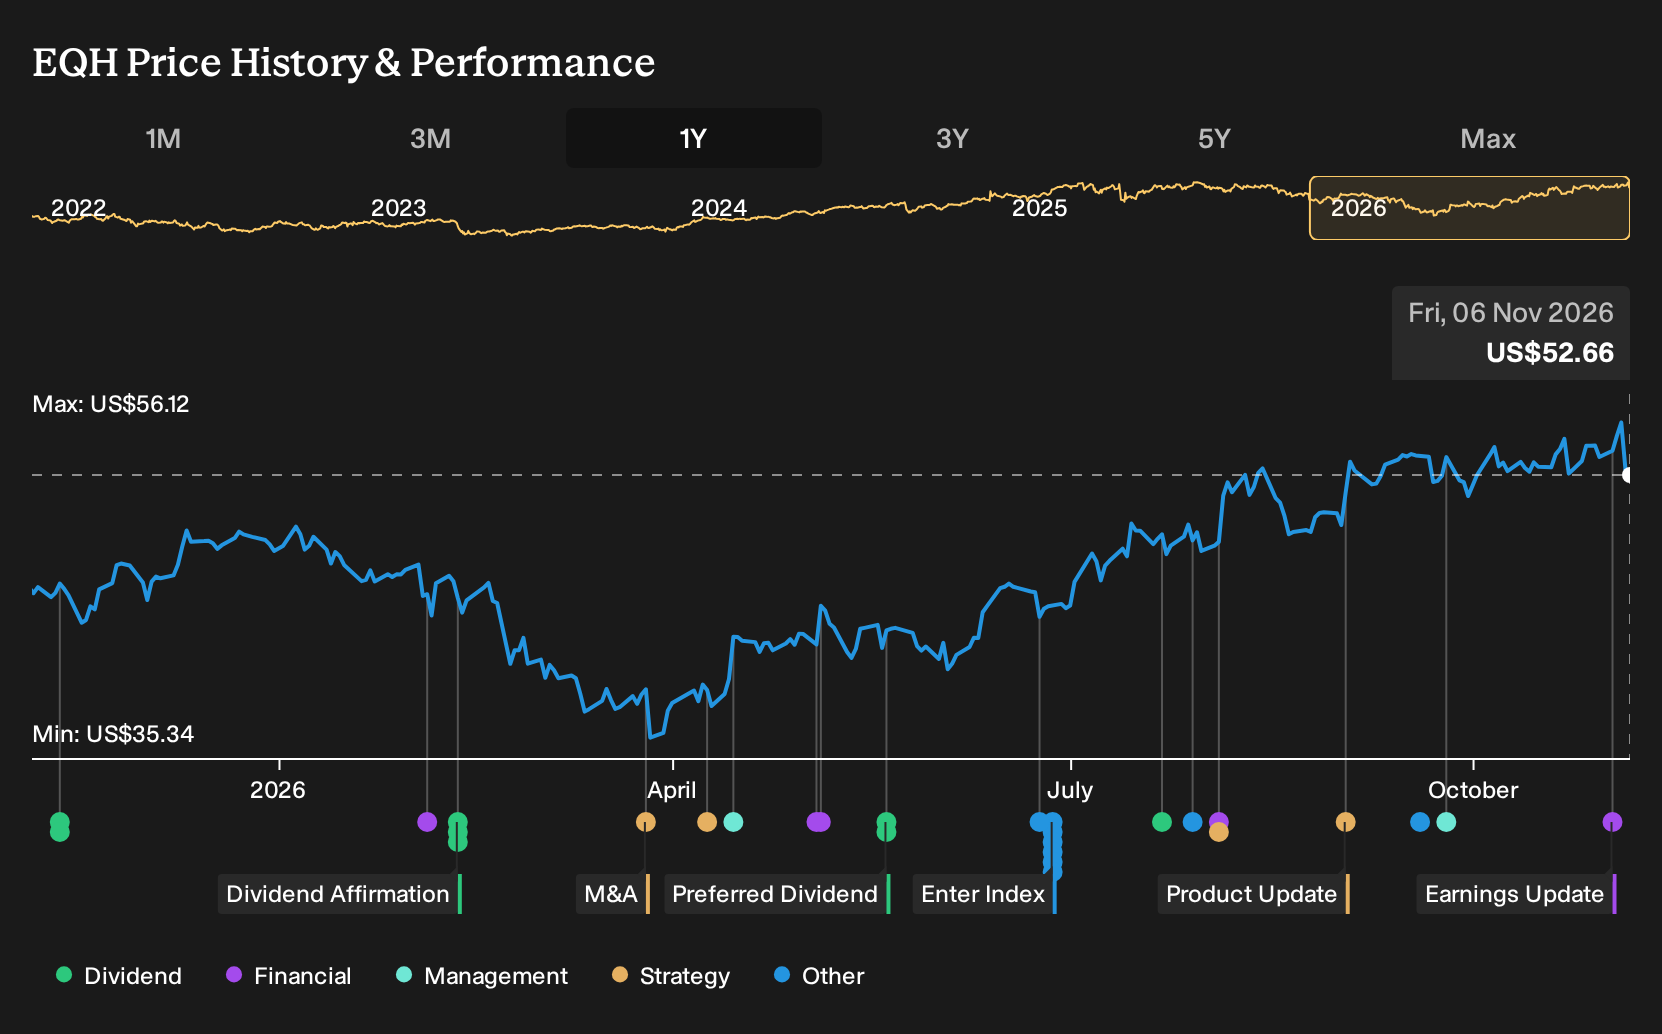
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from about 63.9 to more than 358,000, which signals just how far apart views on Equitable Holdings can be. Those opinions do not yet reflect the latest earnings, so you may want to weigh them against merger execution risk and retirement demand as you form your own view.
Explore 2 other Equitable Holdings fair value estimates, including one that suggests as much as 679778% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Equitable Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Equitable Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate the overall financial health of Equitable Holdings at a glance.
Looking For More Investment Ideas Beyond Equitable Holdings?
If the Equitable Holdings story has sharpened your sense of what you want in a business, use that filter to scan a broader opportunity set with the Simply Wall St Screener.
- For investors who want current income backed by robust fundamentals, consider starting with 8 dividend fortresses that have both yield and balance sheet support.
- If your focus is on resilient businesses that may hold up better when conditions get choppy, you can narrow the field quickly by reviewing 29 resilient stocks with low risk scores that pass strict risk checks.
- If you prefer to hunt where fewer eyes are looking yet still want strong fundamentals, then cast a wider net across 19 high quality undiscovered gems that pair quality metrics with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com