


EN
Victory Capital Holdings (VCTR) Following Mixed Earnings Is The First Eagle Deal Already Priced In
Victory Capital Holdings (VCTR) just put fresh numbers on the table, with mixed third quarter earnings, record long term inflows, and progress on its pending First Eagle Investments acquisition drawing investor attention.
The latest numbers have arrived alongside a sharp move in the share price, with Victory Capital Holdings posting a 1 day share price return of 6.08% and a year to date share price return of 86.02%. The 1 year total shareholder return of 99.75% and 3 year total shareholder return of more than 3x indicate that momentum has been building as investors respond to record inflows, capital returns, and the planned First Eagle acquisition.
Capitalize on Victory Capital Holdings’ momentum and see how it compares to other asset managers showing strong inflows and fundamentals in our curated 19 high quality undiscovered gems.After a near 100% total return over the past year and a fresh pop on the earnings print, Victory Capital Holdings is no longer a quiet backwater. The real tension now is simple: pay up today for that momentum, or wait for a cooler entry and risk watching the valuation gap close without you.
Most Popular Narrative: 1% Undervalued
On the numbers, the most followed narrative pegs fair value for Victory Capital Holdings around $120.17, almost exactly in line with the latest $119.24 close. That tiny gap puts the focus less on a large discount and more on whether the business can deliver on the growth and leverage assumptions included in that fair value.
Analysts expect Victory Capital Holdings to continue using acquisitions such as First Eagle, ETFs, and international partnerships to expand its client reach and earnings base over time.
The main execution risk is whether Victory Capital Holdings successfully integrates First Eagle, delivers the planned US$280 million of net expense synergies, and manages higher leverage while maintaining its high-margin operating model.
See why 50 investors see Victory Capital Holdings as 1% undervalued.
Result: Fair Value of $120.17 (ABOUT RIGHT)
Still, higher net debt near 3.2x EBITDA and any shortfall on the planned US$280 million First Eagle cost synergies could quickly challenge that Victory Capital Holdings optimism.
Find out about the key risks to this Victory Capital Holdings narrative.
Another Angle On Victory Capital Holdings’ Valuation
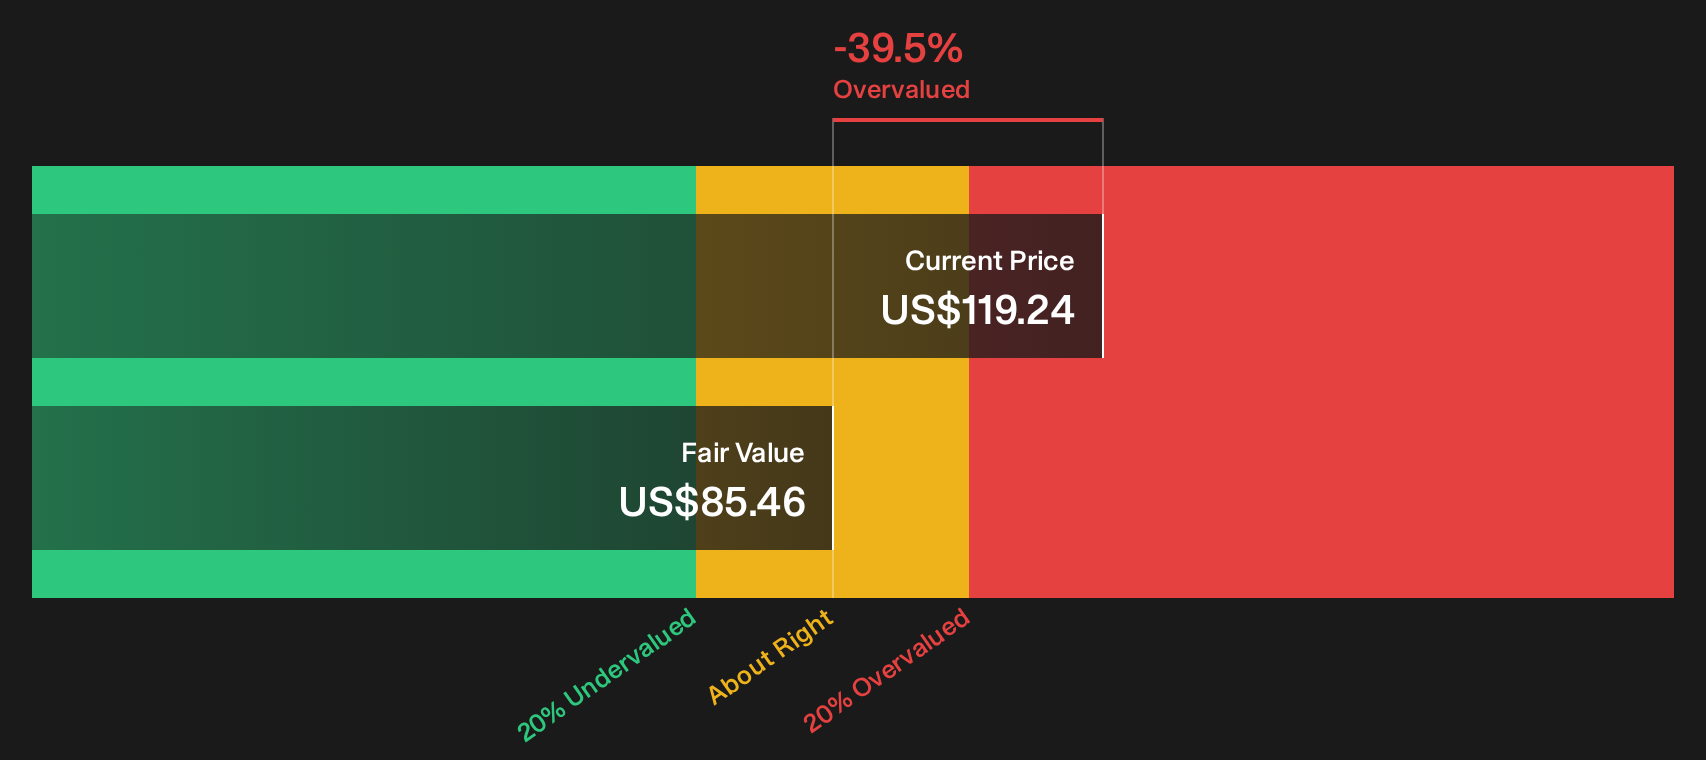
The SWS DCF model paints a different picture for Victory Capital Holdings. On that framework, the shares around $119.24 screen as expensive versus an estimated future cash flow value of $85.46, implying the market price is running ahead of those cash based assumptions. That gap leaves you weighing momentum against cash flow discipline.
For a closer look at how this cash flow view is built and what would need to change for the story to line up with the current share price, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Feeling the mixed signals around Victory Capital Holdings and its fair value story? Act quickly, review the underlying data for yourself, and pressure test the optimism by examining the 3 key rewards.
Looking for more investment ideas beyond Victory Capital Holdings?
Do not stop at one opportunity. Use the Simply Wall Street Screener to compare Victory Capital Holdings with other stocks that match your risk, return, and income goals.
- Target resilient potential by focusing on capital preservation and steadier journeys with the 29 resilient stocks with low risk scores.
- Sharpen your hunt for value by zeroing in on companies that look overlooked on quality and pricing through the 39 high quality undervalued stocks.
- Build a portfolio that works while you sleep by scanning for income focused opportunities using the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com