


EN
Trip.com Group (TCOM) Stock May Be A Bargain Following Margin Strength
Trip.com Group has delivered a 44.1% share price gain over the past 5 years, yet more recent weakness means many holders are now asking whether the current US$44.37 price is still supported by the company’s earnings power. With sentiment pulled in different directions by short term moves and fresh headlines, the key issue is how the profit profile lines up against what the market is paying today.
- The 44.1% return over 5 years puts real weight on the question of whether Trip.com Group’s earnings justify locking in at today’s valuation after that journey.
- Recent revenue growth of 5.5% and a net margin of 36.9% show a business currently turning a meaningful share of its sales into profit, which can matter a lot when you judge the earnings multiple.
- There is a second opinion on Trip.com Group worth weighing. See what analysts think Trip.com Group's shares could be worth.
The issue now is whether the stock’s current price fairly reflects Trip.com Group’s earnings profile once you set it against the Fair Ratio benchmark.
If you want to pressure test this same earnings question beyond Trip.com Group, compare it with a wider set of 39 high quality undervalued stocks.
Is Trip.com Group a Bargain on Earnings?
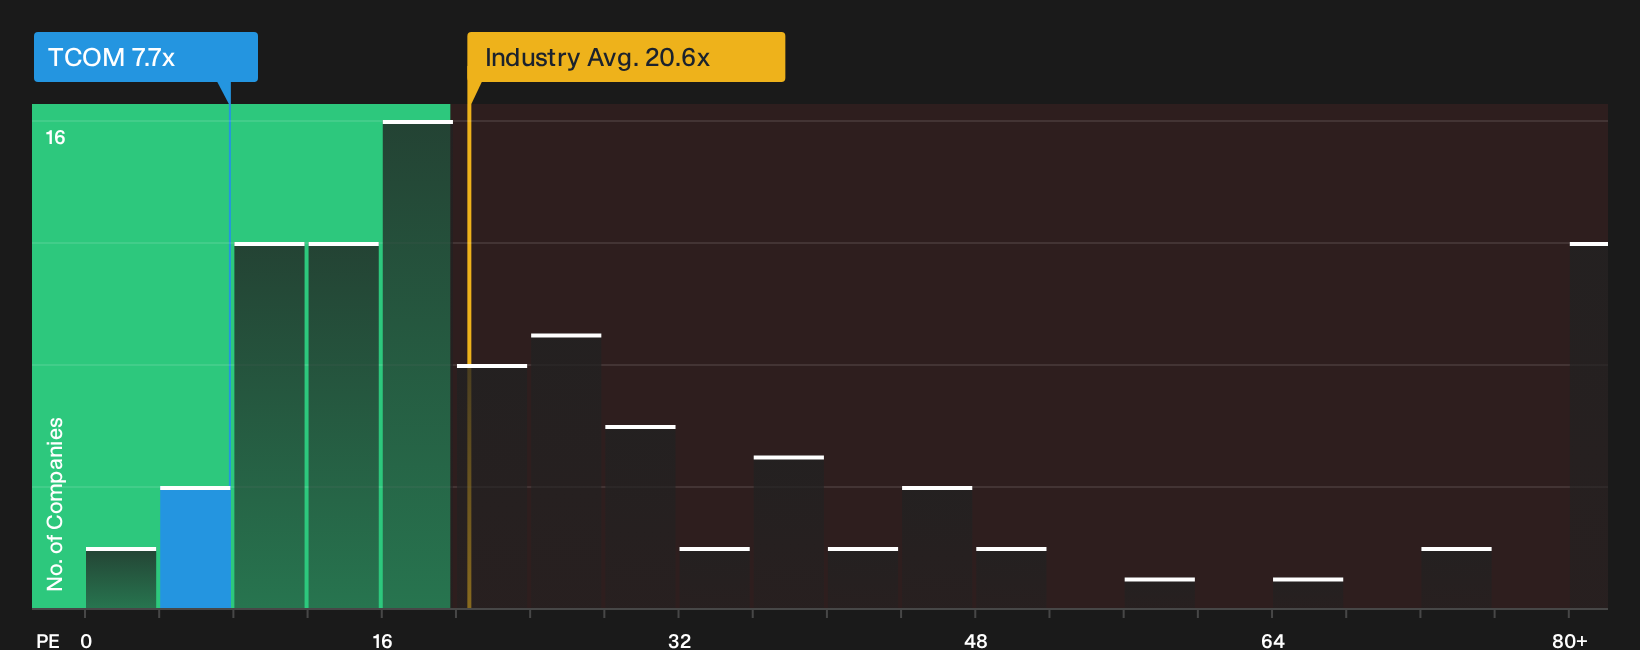
The P/E ratio is a clean way to compare what you pay for each unit of Trip.com Group earnings with other listed travel businesses. At around 7.7x, the stock trades well below both the Hospitality sector average of roughly 20.6x and the peer group on about 19.3x, which means the market is currently attaching a lower price tag to each dollar of Trip.com Group profit than to many rivals.
Because the Fair Ratio model blends growth, margin profile, size and risk into a tailored benchmark, the current P/E sits below what that framework would imply and screens as undervalued on this metric. Despite the recent report pointing to a 36.9% net margin and revenue growth of 5.5%, the multiple is still at a discount to wider Hospitality stocks, so anyone looking at Trip.com Group through an earnings lens is being asked to weigh whether that gap reflects risk or opportunity. Explore the numbers behind Trip.com Group's P/E valuation.
The Trip.com Group Narrative: What Would Justify Today's Price?
Trip.com Group’s valuation puzzle only really becomes clear once you can see which future paths would justify a much higher or much lower price from here, and that is exactly what Simply Wall St Narratives on the Community page aim to unpack. Rather than relying on a single P/E or one model output, each scenario lays out the growth, margin and earnings assumptions behind its view of fair value so you can compare those expectations with how Trip.com Group's actual results evolve over time.
One of the top community narratives on Trip.com Group: 5% undervalued
"The AI search initiative also delivers on schedule, paired with usage data that didn’t exist before, with TripGenie interactions increasingly booking-related..."
Discover why this Narrative puts Trip.com Group at 5% undervalued.
Before acting on Trip.com Group’s valuation, there is one more factor to weigh
Numbers only tell part of the story, because the people steering Trip.com Group and the way they are rewarded can strongly shape how that story develops. See who runs Trip.com Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com