


EN
What Eldorado Gold Holders Saw Early
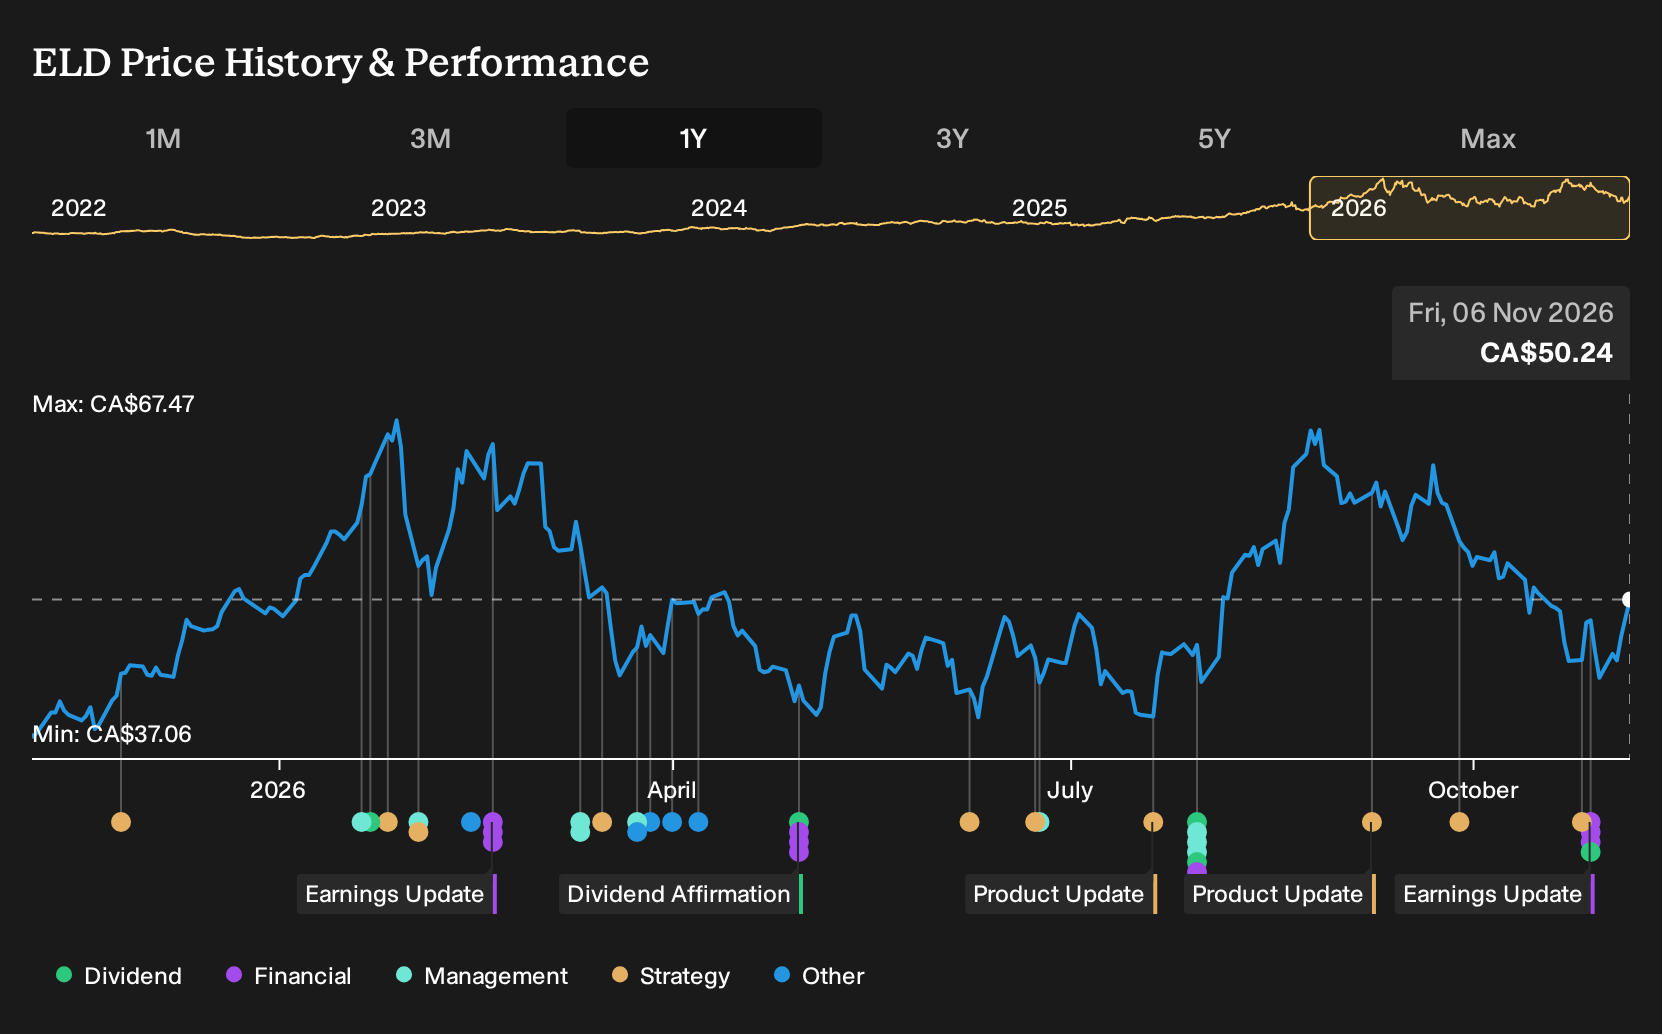
Holding Eldorado Gold over the past year would have returned 34.5%, including dividends. If you had been weighing a position back on 6 November 2025, you were facing clashing stories about Skouries and Olympias, aggressive buybacks, rising ESG scrutiny, and a wide analyst gap between a bullish CA$40.86 view and a bearish CA$28.46 stance. Which part of Eldorado Gold’s evolving mix of Greek, Turkish, and Canadian projects truly deserved your confidence then?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Eldorado Gold. See which of 33 elite gold producer stocks may still merit a closer look.
The Argument Eldorado Gold Investors Faced Back Then
The shares cost CA$37.06 at the start of the period, and Eldorado Gold sat between two very different stories about its future.
On the optimistic side, the bull Narrative put Fair Value at CA$40.86, assuming Skouries would ramp up ahead of schedule and that Olympias could keep cash costs falling after a 35% quarterly decline.
The bearish view set Fair Value at CA$28.46 and treated rising ESG pressure plus higher all in sustaining costs of US$1,520 per ounce as serious threats to future margins.
What The Results Changed For Eldorado Gold
The key fact is that Eldorado Gold’s Q3 2026 update showed revenue of US$511.86 million and net income of US$117.95 million, compared with US$434.73 million and US$56.54 million in Q3 2025. Net margin moved from 13.0% to 23.0%. That combination leaned toward the optimistic case that argued improving profitability, although rising costs at Skouries and project delays meant the cautious argument was not fully sidelined.
The lesson is simple. When a thesis hangs on better margins, do not just track production headlines. Watch whether net income and net margin, not only revenue, actually move in the direction the original story relied on.
What Eldorado Gold’s Price Now Asks You To Believe
Eldorado Gold trades at CA$50.24 today, and the selected bullish Narrative places its Fair Value above that level rather than below it. The core case now leans on copper rich growth, not just gold output.
This Narrative argues the current price still underplays what a successful Skouries and McIlvenna Bay ramp could mean for future cash generation.
"Together, these assets are intended to support higher production, a more diversified revenue mix, and improved cost efficiency as low to negative cost assets contribute more of the portfolio. The key requirement is a smooth commercial ramp-up of Skouries and McIlvenna Bay on the updated capital and schedule."
One Narrative disagrees with today's price. → See where this Narrative says Eldorado Gold should trade
Looking Beyond Eldorado Gold
Eldorado Gold leans heavily on copper rich expansion. Your thesis probably now hinges on that metal.
Step one away and the same copper need appears again. Another miner is reaching further into that market, plus aluminum and lithium.
Rather than just chasing new ounces, this business links its pitch to long term electrification and urban build out demand.
It is advancing large copper developments and battery material projects aiming to lift volumes and trim unit costs.
If those plans hold together, your copper focused watchlist might deserve a closer second look.
One Narrative has already put a figure on it. → Uncover the company trading 17% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com