


EN
Marcus & Millichap (MMI) Returned To Profit, Is The Stock Still Cheap?
Marcus & Millichap (MMI) just posted third quarter earnings, reporting US$208.37 million in revenue and US$1.01 million in net income, or US$0.03 in basic and diluted earnings per share.
At a US$27.75 share price, Marcus & Millichap has seen short term share price momentum cool, with the 1 day move down 3.18% and the 90 day share price return down 11.85%. The year to date share price return of 2.82% contrasts with a 1 year total shareholder return that is down 3.50%, reflecting the drag from a weaker 5 year total shareholder return that is down 36.60%.
Scan how Marcus & Millichap compares with other real estate and capital-market focused businesses by reviewing a curated 39 high quality undervalued stocks that highlights stocks with quality fundamentals and compressed expectations.Marcus & Millichap now shows higher revenue and a small profit, yet the share price has pulled back and long-term returns are weak. Is the business quality being offered at a reasonable valuation today?
Most Popular Narrative: 90% Undervalued
Marcus & Millichap last closed at $27.75 while the most followed narrative anchors fair value at $28.00, pointing to only a small gap between price and that specific target but a much larger gap relative to a $59.97 future cash flow estimate.
The analysts have a consensus price target of $28.0 for Marcus & Millichap based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $1.1 billion, earnings will come to $81.3 million, and it would be trading on a PE ratio of 15.1x, assuming you use a discount rate of 8.4%.
See why 1 investors see Marcus & Millichap as 1% undervalued.
Result: Fair Value of $28 (UNDERVALUED)
Still, the narrative around Marcus & Millichap can change quickly if commercial real estate transaction volumes slump again or if fee pressure further erodes commission economics.
Find out about the key risks to this Marcus & Millichap narrative.
Another Way To Look At Marcus & Millichap
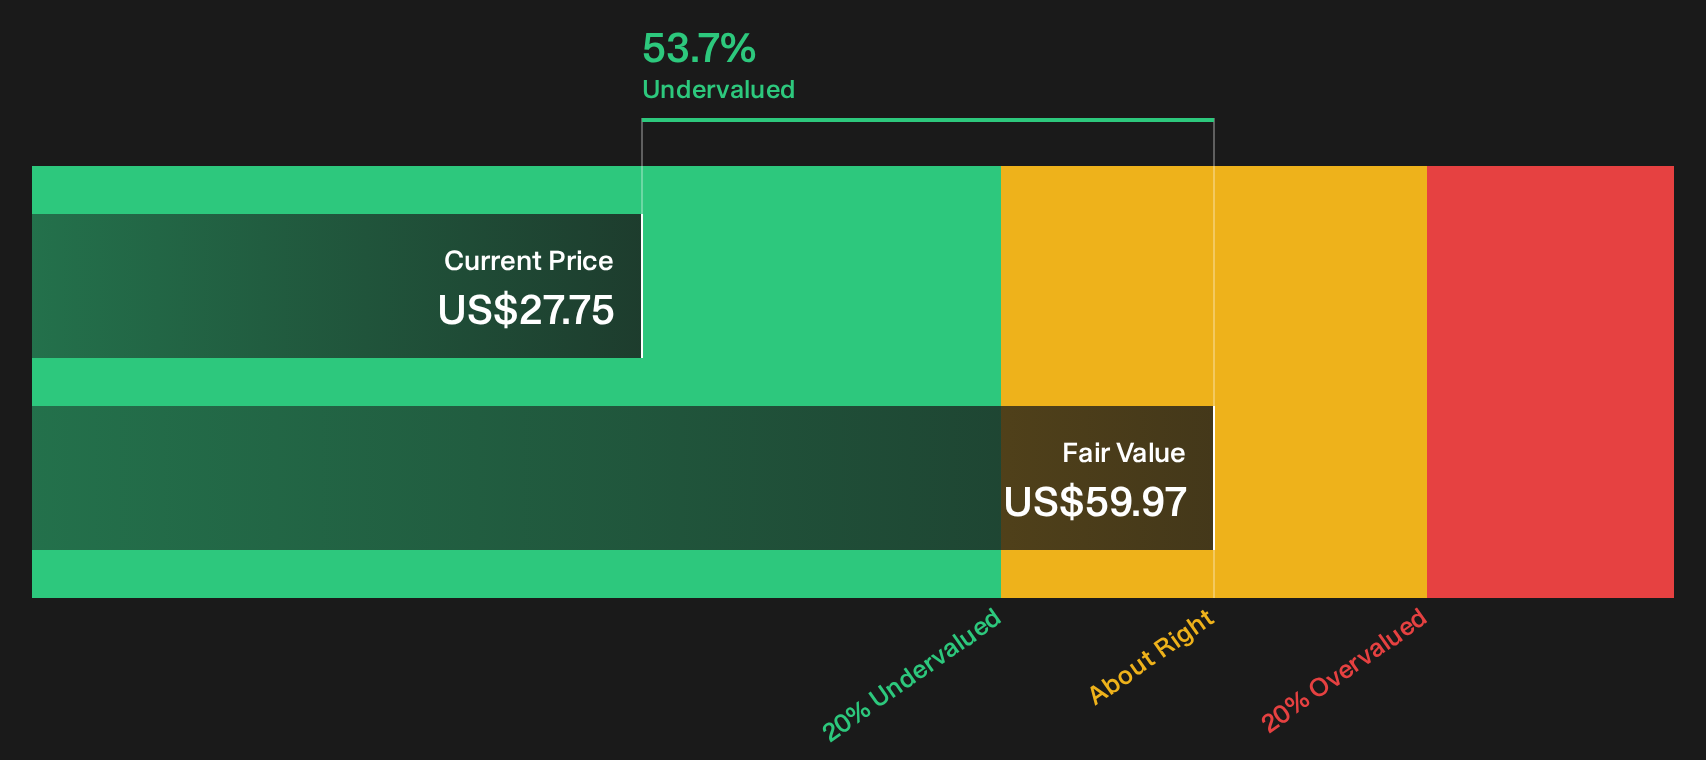
The SWS DCF model points to a very different picture for Marcus & Millichap. On that view, the shares at $27.75 trade at a 53.7% discount to an estimated future cash flow value of $59.97, which implies upside rather than the tight range suggested by the $28.00 fair value. Which signal matters more for you?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals can feel frustrating, especially when Marcus & Millichap shows both pressure points and brighter spots in the same set of numbers. Move quickly from headline impressions to your own thesis by weighing the 3 key rewards and 1 important warning sign.
Want More Ideas Beyond Marcus & Millichap?
If Marcus & Millichap has you thinking more broadly about where to put fresh capital, take the next step and widen your opportunity set today.
- Target potential mispricings by scanning a curated 39 high quality undervalued stocks that focuses on strong fundamentals paired with subdued expectations.
- Prioritize stability first and hunt through a 29 resilient stocks with low risk scores that filters for resilient businesses with more measured risk profiles.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems that points to quality fundamentals hiding outside the usual watchlists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com