


EN
Is Election Driven Housing Optimism Altering The Investment Case For Home Depot Shares?
- Home Depot recently featured in several developments, including ETF trading flows around the US midterm elections and a Canadian Innovation Awards program highlighting products aimed at faster, higher quality renovation work for both DIY and professional customers.
- The election driven shift toward housing friendly policy expectations intersects with Home Depot's push deeper into complex Pro projects, where better financing conditions and improved housing turnover could influence demand for large delivered orders.
- We will examine how Home Depot's investment narrative relates to election driven optimism around housing policy and potential borrowing cost relief.
Scan how Home Depot's post election momentum compares with other housing sensitive retailers by reviewing the hand picked 39 high quality undervalued stocks that may also be drawing interest from ETF flows.
Home Depot Investment Narrative Recap
To own Home Depot, you need to believe its push into Pro and complex projects, plus faster fulfillment and AI driven productivity, can matter more than weak big ticket demand and low housing turnover. The key near term catalyst is management execution on Pro ecosystems and specialty distribution while keeping gross margins from eroding further.
The biggest immediate risk is that mix toward lower margin Pro categories, tariff refund roll off, and higher fuel and product costs squeeze profitability just as housing activity remains subdued. Recent post election optimism and ETF interest do not change that operational equation in a material way right now.
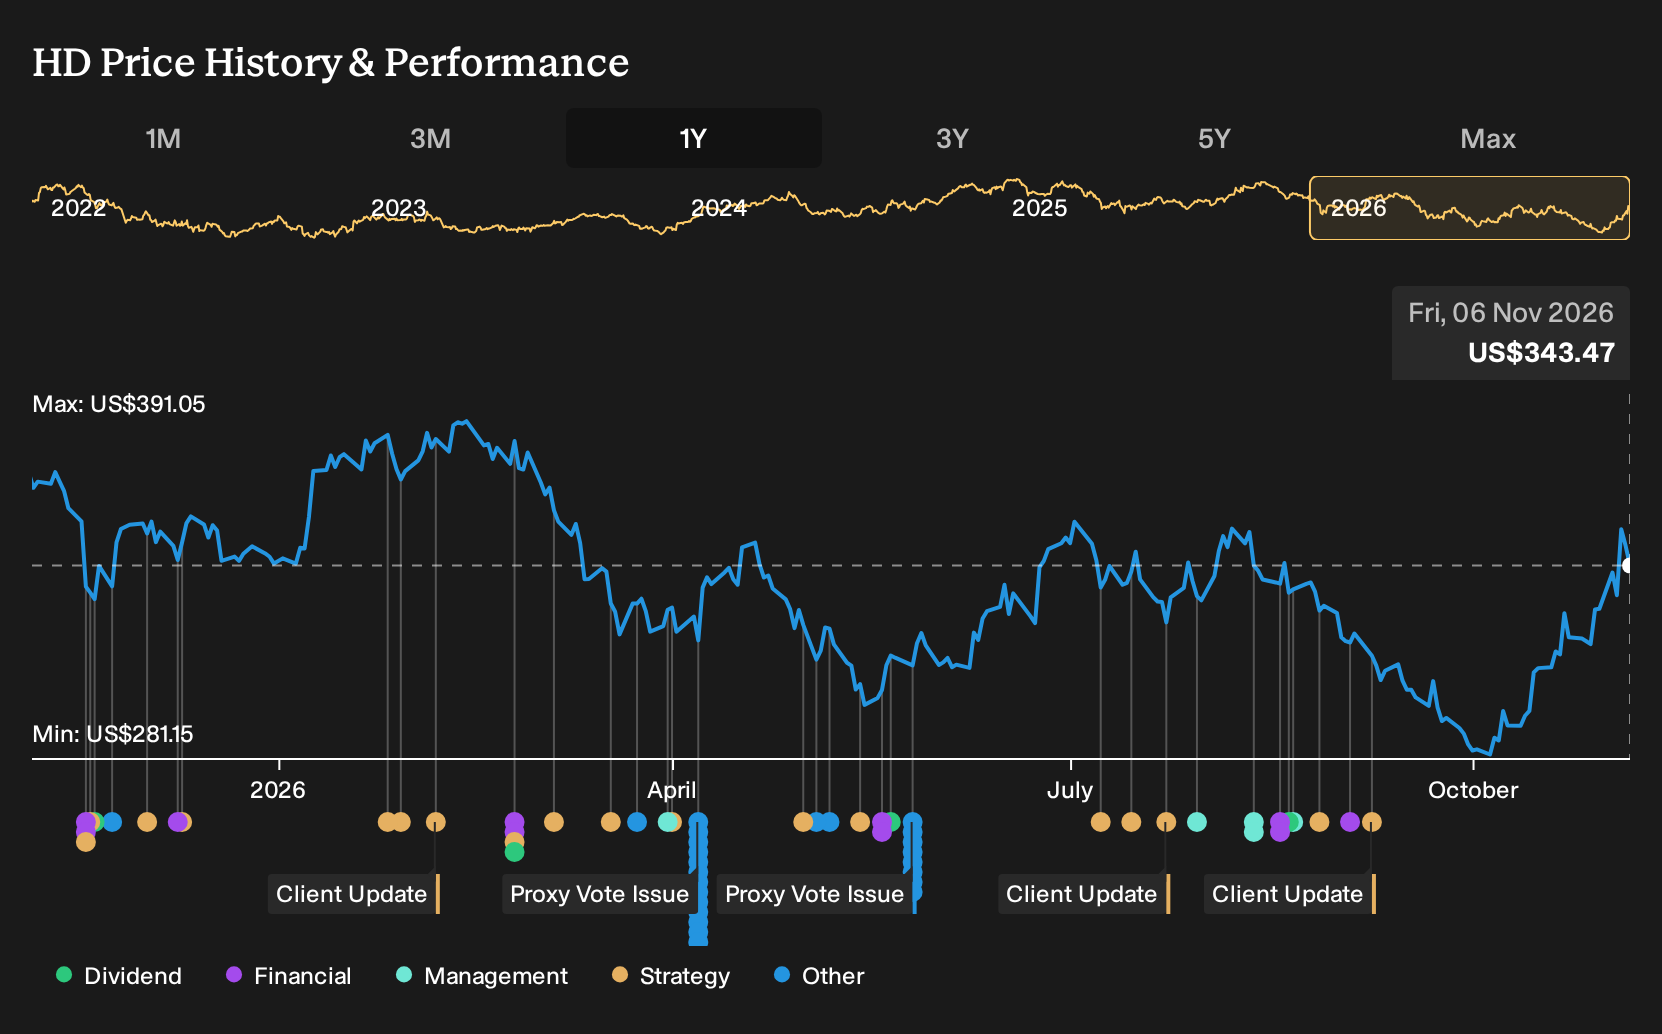
The most relevant recent development is the concentrated ETF buying in Home Depot, led by DIA, XLY and IYC, over the past week. That flow sits on top of a 12% share price move following the elections, which pulled the stock closer to the current analyst price target and shrank the discount implied by some fair value models.
For you as a shareholder, the question is whether that renewed ETF demand is anticipating a real turn in housing sensitive categories that feed complex Pro orders. If the expected housing policy support or borrowing cost relief disappoints, the risk is that revenue from larger projects stays capped while margin pressures from Pro investments and higher input costs persist.
Home Depot's narrative projects US$188.7b revenue and US$17.4b earnings by 2029. This implies 3.7% yearly revenue growth and an earnings increase of about US$3.2b from US$14.2b today.
Uncover why Home Depot's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$275.9 to US$385, so you are seeing a wide band of opinion around Home Depot. ETF flows that flipped from broad XLY selling to concentrated buying, plus ongoing margin and housing turnover risks, give you reasons to compare several community viewpoints before leaning on any single one.
Explore 3 other Home Depot fair value estimates, including an estimate that indicates up to 12% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Home Depot research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Home Depot. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Home Depot's overall financial health at a glance.
Looking for more investment ideas beyond Home Depot?
Once you have a view on Home Depot, it often helps to benchmark that thinking against other opportunities that share similar risk, income, or balance sheet profiles. The Simply Wall St Screener can give you a curated starting point so you spend more time assessing quality and less time trawling through tickers.
- If you want income to do more of the heavy lifting in your portfolio, scan through a set of potential yield candidates in the 8 dividend fortresses that pair higher payouts with detailed fundamentals.
- If capital preservation ranks high on your priority list, narrow your search to companies in the 29 resilient stocks with low risk scores and compare how their risk profiles stack up against Home Depot.
- If you prefer strong financial foundations before anything else, start with the list of solid balance sheet and fundamentals (24 results) and look for businesses whose debt and liquidity metrics match your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com