


EN
Kymera Therapeutics (KYMR) Advances KT 579 And KT 621, Is It Still 6% Undervalued?
Kymera Therapeutics (KYMR) is back in focus after reporting a third quarter net loss of US$132 million and a nine month net loss of US$262.44 million, even as interest around KT-579 and KT-621 remains strong.
Kymera Therapeutics’ latest net loss figures land against a backdrop of strong price gains, with the share price at US$131.73 after a 30 day share price return of 21.58% and an 81.05% share price return year to date. The 1 year total shareholder return of 124.57% and very large 3 year total shareholder return above 7x suggest momentum has been building as investors weigh the KT-579 and KT-621 clinical updates against a valuation that already prices in a lot of future execution risk.
Spot 19 high quality undiscovered gems that, like Kymera Therapeutics, pair early-stage clinical momentum with strong fundamentals and may still be flying under most investors’ radar.After a move like Kymera Therapeutics just posted, the dilemma is simple enough. Step in after a sharp run, or wait and risk watching the valuation run further without you as the numbers get picked apart next.
Most Popular Narrative: 6% Undervalued
Kymera Therapeutics last closed at $131.73, just under a narrative fair value estimate of $139.83 that assumes meaningful progress from KT-621 and KT-579 over the next few years.
The main requirement for this thesis is successful late-stage development and regulatory progression of KT-621 in atopic dermatitis and asthma, alongside KT-579 in lupus, while managing rising R&D and G&A spending within the current cash runway that is guided into 2029.
See why 6 investors see Kymera Therapeutics as 6% undervalued.
Result: Fair Value of $139.83 (UNDERVALUED)
Still, Kymera Therapeutics carries real execution risk if heavy quarterly R&D and G&A spending strains the cash runway, or if shareholder investigations dampen market confidence.
Find out about the key risks to this Kymera Therapeutics narrative.
Another View: What Kymera Therapeutics’ Valuation Ratio Says
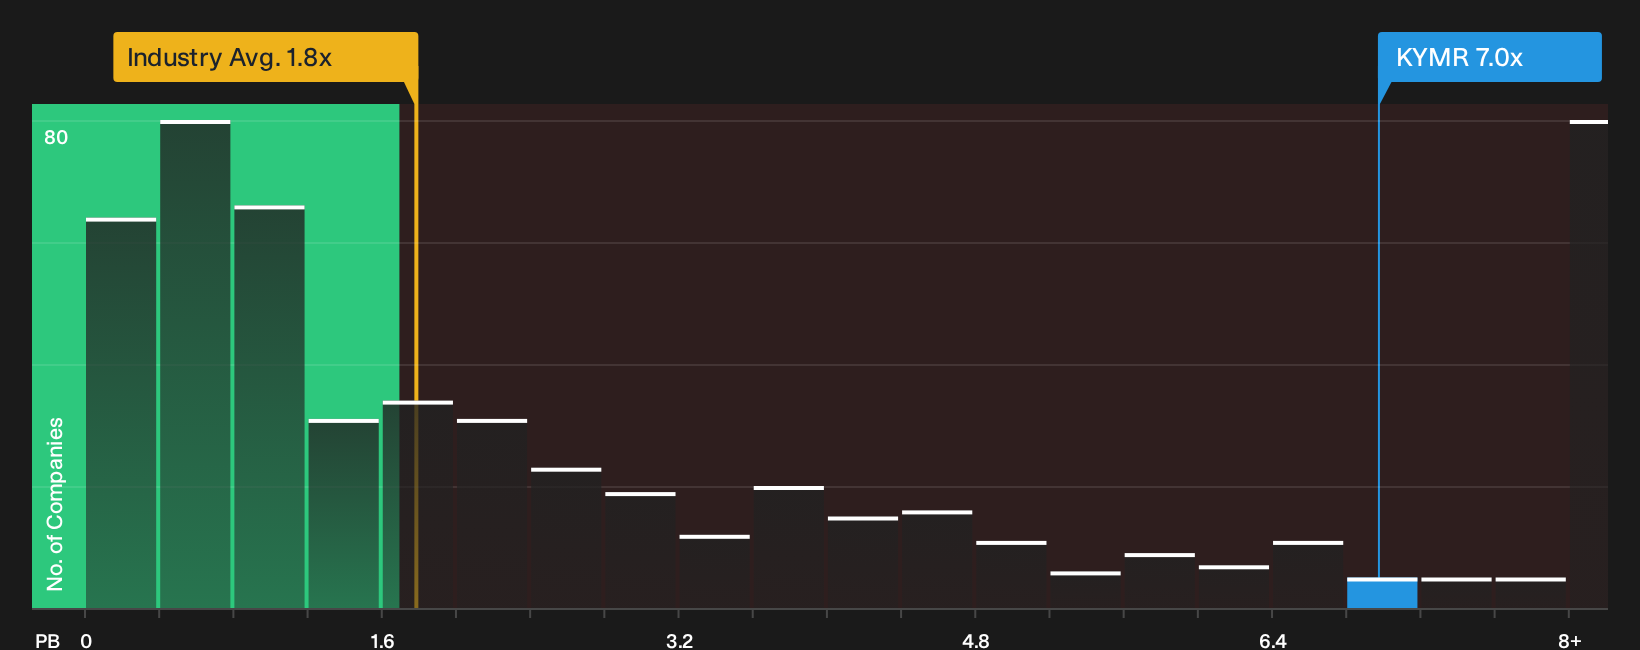
The fair value story for Kymera Therapeutics leans on analyst targets and long range earnings assumptions. A simple P/B check tells a very different story. The stock trades around 7x book value, compared with about 1.7x for the US Biotechs industry and roughly 5.7x for peers, which points to a rich premium rather than a cheap entry point. If that gap closed, how much of the current narrative would still hold up for you as a shareholder?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Kymera Therapeutics story points in different directions, which is exactly why the next move should be yours and yours alone. Weigh both the concern around downside risk and the optimism around potential upside by reviewing the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Kymera Therapeutics?
If Kymera Therapeutics has your attention, do not stop there. Broader opportunity often comes from scanning multiple angles before committing fresh capital.
- Spot potential mispricings early by reviewing companies filtered as 39 high quality undervalued stocks that align with strong business quality and more reasonable expectations.
- Prioritise resilience by scanning a 29 resilient stocks with low risk scores that focuses on businesses with steadier profiles when market sentiment turns jumpy.
- Target stronger financial foundations by working through a list of solid balance sheet and fundamentals (24 results) that highlights firms with healthier debt levels and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com