


EN
What Veolia Environnement Holders Got Right
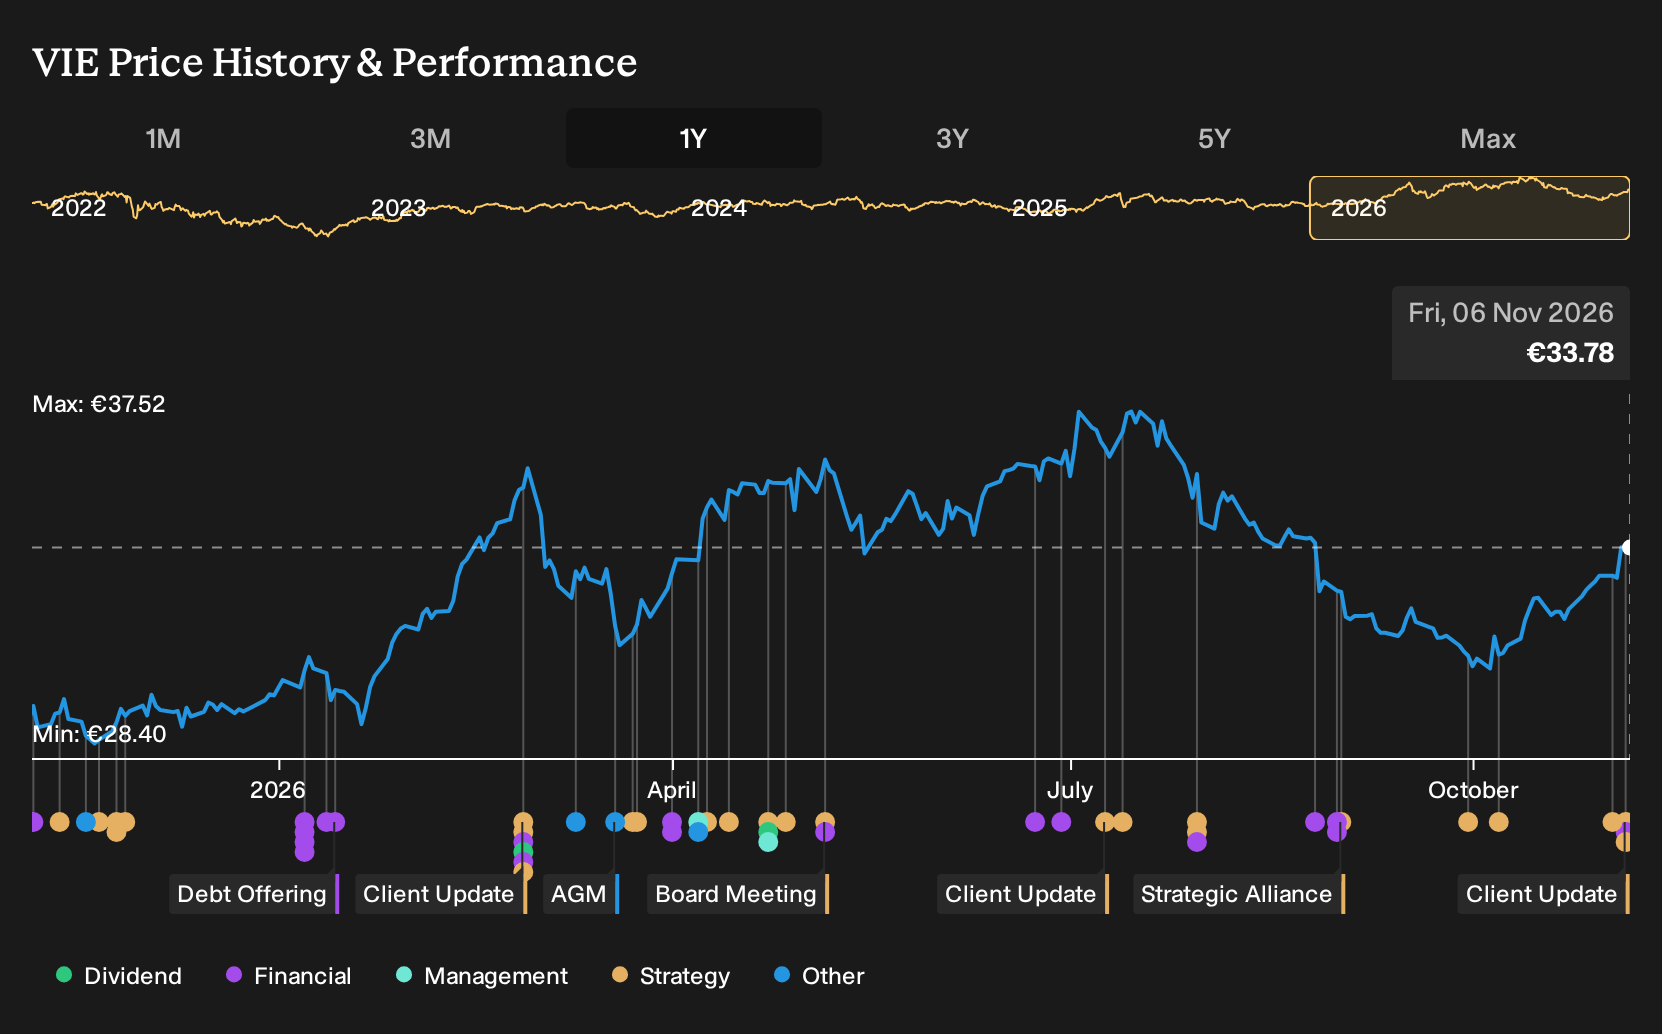
If you had been weighing Veolia Environnement in November 2025, you were looking at a utilities group trying to blend big-ticket water and waste projects with higher value technology services, while also carrying sizeable debt and ongoing M&A. Investors who held Veolia Environnement over the past year are up 22.2%, including dividends. The real question now is which of those early trade offs between growth projects, leverage and contract visibility appeared most convincing at the time.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Veolia Environnement has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument You Would Have Been Weighing On Veolia Environnement
The shares cost €29.43 at the start of the period, and Veolia Environnement sat between two very different stories about how its water and waste projects might play out.
The bullish narrative put Fair Value at €35.23 and leaned on rising global environmental rules and demand for advanced water and hazardous waste solutions, as well as expected synergies from deals such as Suez and the CDPQ Water Technologies stake.
The bearish view pointed to Fair Value of €25.3 and focused on nearly €21b of net financial debt with leverage around 3 times EBITDA, along with pressure from decentralized energy and local recycling solutions on legacy infrastructure contracts.
What The Results Changed In The Veolia Environnement Debate
Veolia Environnement landing a €1b, 25 year drinking water contract in Spain and closing the Clean Earth acquisition tilted the evidence toward the bullish case that focused on long term water and hazardous waste projects. H1 2026 numbers showed revenue of €22,193m and net income of €671m, both slightly above H1 2025, so profitability expectations were not clearly challenged.
The useful takeaway is about testable assumptions. When a story leans on contract visibility and scale, it helps to track the size and duration of new deals, as well as whether revenue and net income actually move in step with that backlog story.
What Today's Veolia Environnement Price Already Assumes
Veolia Environnement now trades at €33.78, with this selected Narrative arguing that its Fair Value sits below the current level. The focus is not on contracts already won, but on how reliably higher margin activities can turn into lasting profitability.
To judge whether today’s price stacks up, you would need to test one core assumption. The business has to convert its mix of water, hazardous waste, bioenergy and digital efficiencies into sustained margin gains that comfortably absorb input cost shocks and integration risks.
"Key Takeaways: Bearish analysts expect Veolia Environnement's push into higher margin international and booster activities to be undermined by rising input costs and geopolitical disruptions, such as the recent Middle East driven squeeze on fuel and chemical costs that weighed on EBITDA in H1 2026. The main thing that has to go right is that Veolia Environnement turns its growing mix of water, hazardous waste, bioenergy and digital efficiencies into sustained margin gains and earnings growth that offset integration risks from acquisitions like Clean Earth and higher leverage."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Veolia Environnement And Reliable Power
Looking at Veolia Environnement, you focus on pipes, contracts and physical waste. One step away sits a quieter question. Where does firm, steady electricity come from for energy heavy users?
Some developers are working on compact fission units that run continuously. They aim to build, own and operate these assets, then sell long term power.
Alongside that, they are trying to recycle used nuclear material into fresh fuel. The goal is a more controlled fuel supply and clearer future unit costs.
There is even a second business line in high value isotopes for medicine and industry. If those projects reach commercial scale, your map of essential infrastructure suppliers might look very different.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 177% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com