


EN
3 U.S. Bank Stocks Retail Investors Are Screening As Rate Cut Odds Shift
October’s hotter jobs report has thrown fresh fuel on the rate debate, with stronger hiring, lower unemployment and faster wage gains all sharpening the focus on what the Federal Reserve does next. That kind of macro surprise can quickly reshape which large U.S. financial stocks investors pay attention to and which they quietly sidestep. This article walks through three screened U.S. banking and financial companies exposed to this latest data shock and explains how the story might matter for your portfolio.
The three large-cap U.S. banks and financials covered below are only a sample, and the full screen surfaced 32 more domestic franchises with equally developed stories that are not unpacked in this article. To size up the broader field quickly, head straight into the U.S. Large-Cap Domestic Banks and Financials screener to identify, analyze, and filter for the highest conviction ideas that match your own criteria.
Amerant Bancorp (AMTB)
Overview: Amerant Bancorp is a U.S. bank holding company that runs Amerant Bank, offering loans, deposits and wealth services closely tied to interest rate trends.
Operations: Amerant Bancorp generates about US$396 million in revenue from its banking activities, primarily through lending, deposit products and related services.
Market Cap: US$1.15b
Amerant Bancorp matters in this screener because it is a domestically focused lender whose everyday bread and butter is priced directly off short term U.S. interest rates.
"Growth in low cost international deposits, including sub 1% funding from Venezuela, is expected to keep supporting Amerant Bancorp’s net interest margin and help sustain interest income on a larger balance sheet."
What really moves the needle from here is how one quiet shift in its credit and funding mix filters through to those future margins.
That quiet shift is the real story, and the full narrative for Amerant Bancorp shows how funding costs, credit mix and capital decisions could be quietly reshaping Amerant Bancorp’s risk reward profile.

Metropolitan Bank Holding (MCB)
Overview: Metropolitan Bank Holding runs Metropolitan Commercial Bank, a U.S. lender focused on business and consumer banking that earns mainly from interest and fees on domestic loans and deposits.
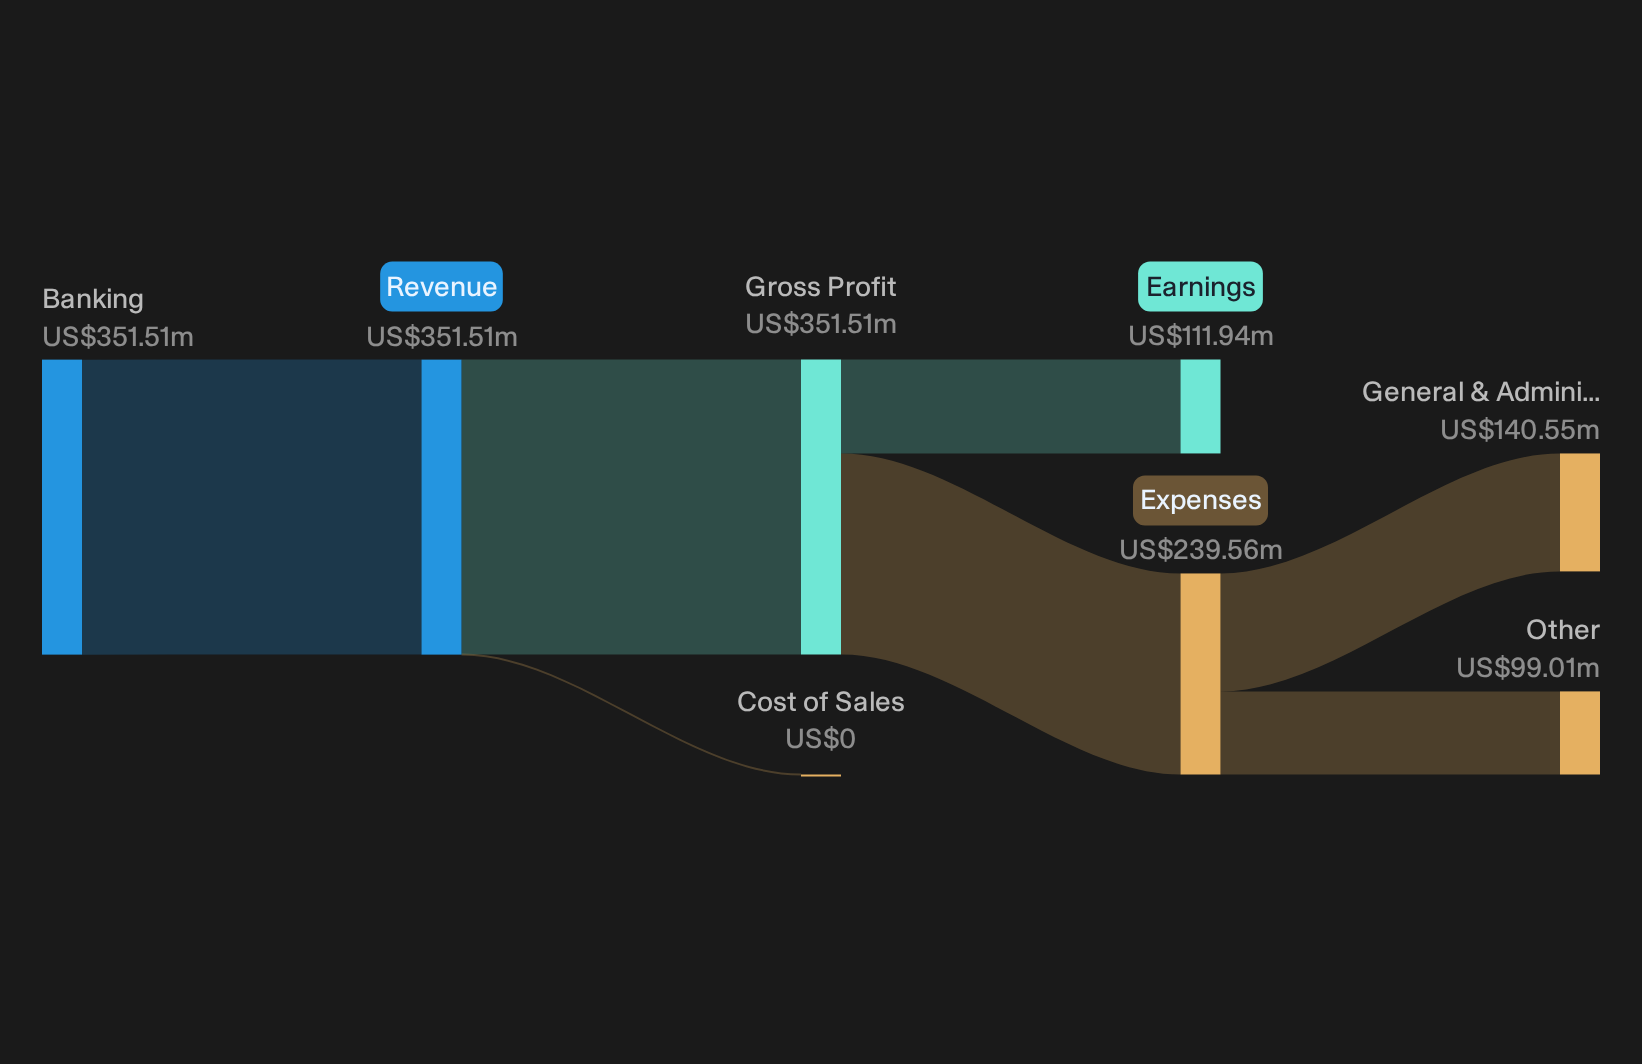
Operations: Metropolitan Bank Holding generates about US$352 million in banking revenue, all from customers in the United States.
Market Cap: US$1.17b
Metropolitan Bank Holding sits in the center of this screener criteria as a large U.S. lender whose core net interest income responds directly to moves in short term rates and the kind of labor market surprise investors just saw.
"The ongoing investment in a new technology stack is now coupled with an "end to end" AI program, with at least seven AI hires or offers by Q2 2026 and a goal to be fully AI enabled within 24 months, which is intended to support higher digital adoption, better operating efficiency and ultimately higher net margins and earnings."
The interaction between that level of technology spending and any unresolved pressure on credit costs and capital returns could be especially important for shareholders.
If that combination of tech spending and credit risk is what you care about, read the full narrative for Metropolitan Bank Holding to see what might be accelerating beneath the surface.
Equity Bancshares (EQBK)
Overview: Equity Bancshares is a Midwest focused U.S. bank holding company whose core Equity Bank franchise earns mainly from interest driven lending and deposit services.
Operations: Equity Bancshares generates about US$313 million in revenue, all from customers in the United States.
Market Cap: US$1.01b
Equity Bancshares matters in this large cap domestic banks screen because its interest income model is directly tied to U.S. rate policy. That connection puts extra weight on how it uses scale, technology and fee income to respond when jobs data nudges market expectations for the Fed.
"The pending acquisition of Lincoln Bancorp, a $1.7b asset community bank with 16 Iowa branches, is expected to expand Equity Bancshares' Midwest footprint and add scale that management projects will be accretive to EPS in 2027, 2028 and 2029, which could support higher long-term earnings power."
What happens to Equity Bancshares' margins and earnings will hinge on one unresolved pressure that could quietly reshape the entire rate benefit story.
That pressure point is where the story gets interesting, and the full narrative for Equity Bancshares shows whether Equity Bancshares' rate upside is being quietly amplified or masked by it.

Seeking Alternatives Before The Crowd Moves
Fresh ideas often move first. By the time everyone sees the breakout, the early entry point can be gone, momentum is flying and spreads are widening. Scan these while it matters and consider acting early.
- Spot sturdy payers that aim to keep income flowing even when prices wobble by scanning a curated group of 8 dividend fortresses.
- Track quiet operators building tomorrow’s automation backbone before the story is fully caught by headlines through a focused set of 89 robotics and automation stocks.
- Hunt for under the radar compounding potential in a hand picked universe of list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com