


EN
What Is Drawing Fresh Attention To Vivmark Residential (VMRK)?
Vivmark Residential (VMRK) is back in focus after management raised its projected merger synergies and reported quarterly earnings and revenue that exceeded consensus estimates, putting the recent AVB EQR integration under closer scrutiny.
Vivmark Residential’s price action has picked up, with a 7 day share price return of 5.83% and a 30 day gain of 10.49% at a last close of $65.51. The 1 year total shareholder return of 14.79% points to momentum rebuilding after a softer 90 day patch.
Compare this earnings surprise and merger synergy story at Vivmark Residential with a curated group of real estate players on our 29 resilient stocks with low risk scores, which screen well for resilience and balance sheet strength.
Given the fresh synergy guidance, solid earnings beat and a 10% move in a month, does Vivmark Residential still offer an appealing skew for new buyers, or has most of the easy valuation upside already been claimed?
Most Popular Narrative: 11.9% Undervalued
Against a last close of $65.51, the most followed valuation storyline for Vivmark Residential anchors on a fair value of $74.40, leaving a modest gap that hinges on how its development and capital recycling plans play out over the next few years.
A US$3.5b development pipeline under construction with projected initial stabilized yields of 6.3% and a funding cost of 4.9% is expected to lift development NOI from US$47 million in 2026 to US$120 million in 2027, which is intended to grow total NOI and future earnings.
See why 2 investors see Vivmark Residential as 12% undervalued.
The prevailing narrative applies a 7.31% discount rate and arrives at a $74.40 fair value. This sits about 11.9% above Vivmark Residential’s current share price and contrasts with an internal future cash flow estimate of $116.61 that implies a materially larger gap. That story also leans on analysts who model revenue of about $3.4b and earnings of $760.1m by 2029, alongside a future P/E of 17.4x that is below today’s 25.0x and below a quoted 35.8x for the wider US Residential REITs group.
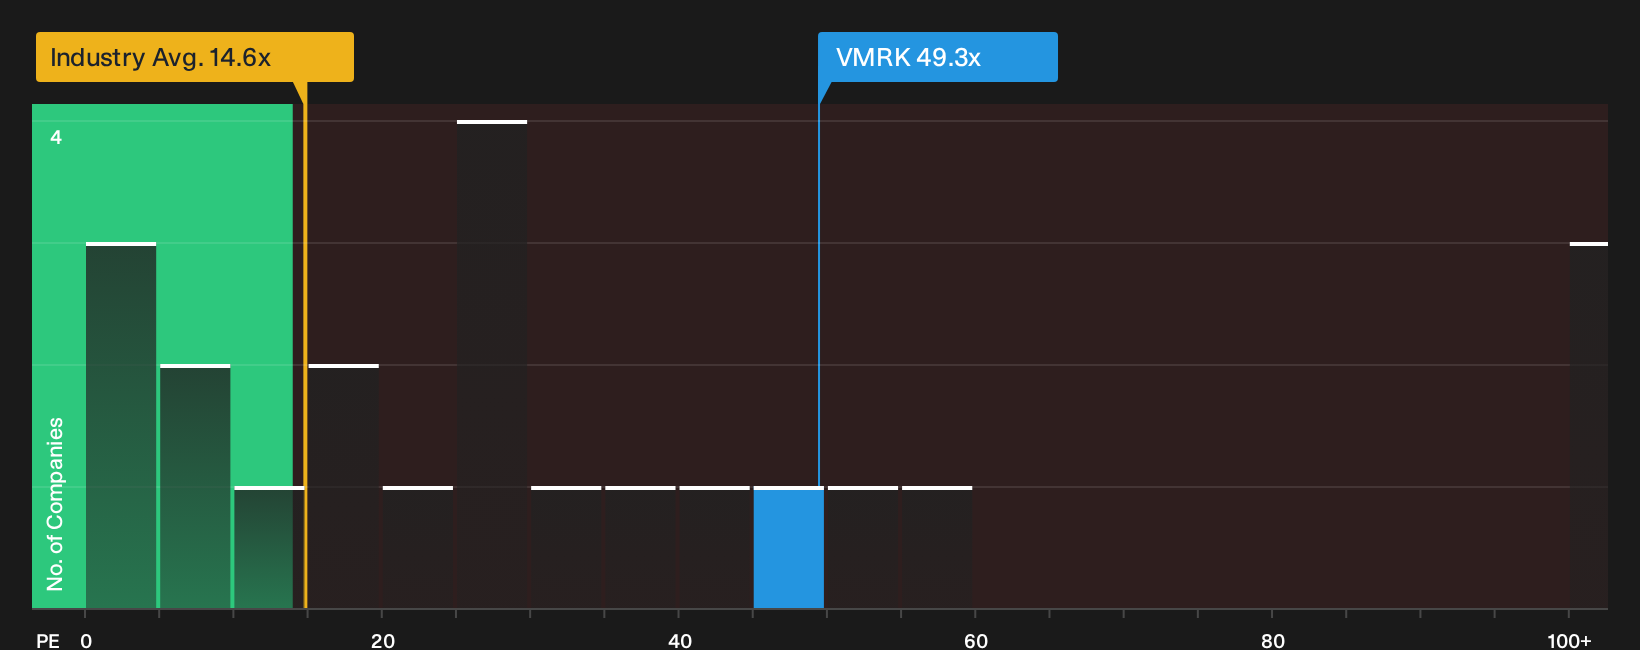
Set against this, several risk markers in the data temper that upside case. These include an earnings forecast that trails broader US market growth, a current P/E of 49.3x that screens as expensive versus both a 36x fair ratio and a 28x peer average, and pressure points such as weaker free cash flow coverage of the 4.29% dividend, higher risk funding, and recent shareholder dilution. Board and management tenure are also very short at 0.3 years, and there has been significant insider selling in the last quarter, which some investors may treat as a signal to monitor alongside the growth and development pipeline story.
Result: Fair Value of $74.40 (UNDERVALUED)
Still, this story can flip quickly if development yields tighten toward funding costs, or if earnings track analysts’ projected decline to US$760.1 million by 2029.
Find out about the key risks to this Vivmark Residential narrative.
Another View On Vivmark Residential’s Valuation
The DCF narrative presents Vivmark Residential as 11.9% undervalued, yet the simple earnings multiple tells a very different story. At a P/E of 49.3x, the stock trades well above a 36x fair ratio, a 28x peer average and a 16.9x wider Residential REITs read across. That kind of premium raises a basic question for you as an investor: Is the DCF upside enough to justify paying well ahead of where the market could eventually drag this valuation multiple?
For a closer look at how this earnings multiple compares with sector norms and the fair ratio, and how that might reset if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of upside and concern around Vivmark Residential feels finely balanced, move quickly to test the numbers yourself and pressure test the story. To see both sides of that picture in one place, review the 2 key rewards and 5 important warning signs
Looking for more investment ideas beyond Vivmark Residential?
If Vivmark Residential has sharpened your focus on quality and valuation, you can use that momentum to widen your watchlist with a few targeted stock ideas.
- Target resilient cash generators that still look overlooked by screening for a curated pool of 39 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that pair robust payouts with staying power through our 8 dividend fortresses.
- Prioritize financial durability by filtering for businesses that carry strong foundations using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com