


EN
Is Sotera Health (SHC) Undervalued Following Its Q3 Beat And Reaffirmed Guidance?
Sotera Health guidance and earnings trigger fresh look at the stock
Sotera Health (SHC) just reaffirmed its 2026 revenue and earnings outlook, reported third quarter results that topped forecasts, and received a Moody's credit upgrade, even as ethylene oxide regulation and litigation remain key risks.
The recent Q3 beat, the reaffirmed 2026 guidance, and Moody's upgrade have not stopped Sotera Health’s share price from sliding. The stock has fallen 11.79% over the past 7 days and is down 15.11% over the past 90 days, even as the 3-year total shareholder return of 23.63% still reflects a much stronger longer-run outcome than the 5-year total shareholder return, which is down 30.57%.
Compare how Sotera Health stacks up against other sterilization and healthcare testing players by scanning a curated group of list of solid balance sheet and fundamentals (24 results)
Sotera Health has kept its outlook and earnings intact while the share price has reset lower. Does that pull the risk reward toward buyers, or are the ethylene oxide and spending pressures still in the driving seat on valuation?
Most Popular Narrative: 30% Undervalued
Against a last close of $16.01, the most followed Sotera Health narrative anchors fair value at $22.72 using a 9.04% discount rate and a detailed earnings path.
The valuation reflects assumptions about a business with high service margins, improving leverage, and elevated 2026 CapEx that is expected to moderate over time. Within this framework, the narrative holds that Sotera Health remains undervalued and that the share price does not fully reflect those cash flow prospects.
See why 1 investors see Sotera Health as 30% undervalued.
Result: Fair Value of $22.72 (UNDERVALUED)
Still, the Sotera Health story rests on two pressure points: ethylene oxide litigation outcomes and heavy 2026 CapEx demands that could strain cash generation and valuation support.
Find out about the key risks to this Sotera Health narrative.
Another View: What SHC’s P/E Says About Value
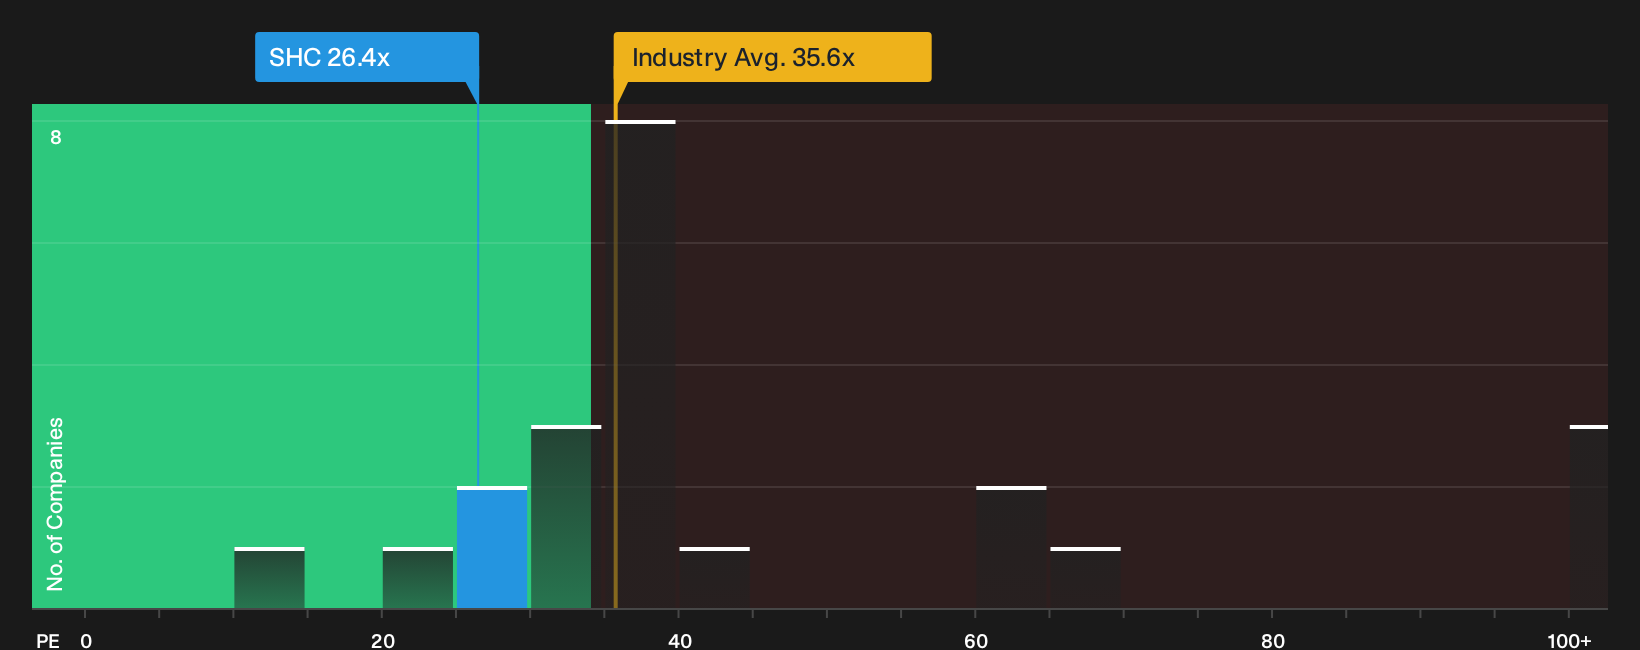
The DCF narrative presents Sotera Health as undervalued, yet the current P/E of 26.4x is above its fair ratio of 21.1x. That represents a clear premium on earnings. It still screens cheaper than peers on 30.9x and the wider Global Life Sciences group on 35.1x, which implies less downside cushion if sentiment turns.
Given those mixed signals, the question is whether you place more weight on the earnings multiple that traders are paying today or on the cash flow path that the narrative is built around.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Sotera Health can be energising or unsettling depending on your risk tolerance, so move fast, go through the data yourself, and balance the 4 key rewards and 2 important warning signs
Looking for more Sotera Health sized ideas?
If Sotera Health has you rethinking your watchlist, do not stop there. Use fresh screens to spot opportunities before they move and pressure test your next idea.
- Target potential mispricings by running through a curated set of 39 high quality undervalued stocks that pair solid fundamentals with appealing entry points.
- Protect your downside first and hunt through a focused group of 29 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Get ahead of the crowd by scanning a hand picked pool of 19 high quality undiscovered gems that most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com