


EN
Enliven Therapeutics (ELVN) On FDA Trial Alignment And The Case For More Upside
Enliven Therapeutics (ELVN) has just cleared a key regulatory hurdle, aligning with the FDA on the final design of its ENABLE-2 pivotal Phase 3 trial for relcobatinib, with initiation targeted before the end of 2026.
Recent trading tells a story of strong momentum for Enliven Therapeutics, with a 1-day share price return of 10.36% and a 30-day share price gain of 19.51%, even though the 90-day share price return declined 18.24%. The 1-year total shareholder return sits at 180.37%, compared with a 3-year total shareholder return of 334.36%.
Scan for other oncology stocks with similar regulatory or trial momentum by focusing on the hand picked 19 high quality undiscovered gems that might be flying under most investors' radars.
Enliven Therapeutics has just sprinted higher on the ENABLE-2 news, which puts you at a crossroads. Is this a sensible entry point after the jump, or does it make more sense to wait for a cooler setup once the valuation dust settles?
Most Popular Narrative: 33% Undervalued
Analysts following Enliven Therapeutics see a fair value well above the last close at $49.43, which puts the ENABLE-2 update into context as part of a much bigger late stage CML story rather than a one day trading spike.
Analysts expect Enliven Therapeutics to build a late stage, well funded CML business around ELVN-001, supported by early clinical data, regulatory alignment on a Phase III design and extended cash runway guidance into 2030.
See why 1 investors see Enliven Therapeutics as 33% undervalued.
Result: Fair Value of $73.90 (UNDERVALUED)
Still, the bullish Enliven Therapeutics story leans heavily on ELVN‑001 hitting pivotal trial goals and on future earnings eventually supporting a very high implied P/E multiple.
Find out about the key risks to this Enliven Therapeutics narrative.
Another View: What Enliven Therapeutics’ P/B Valuation Implies
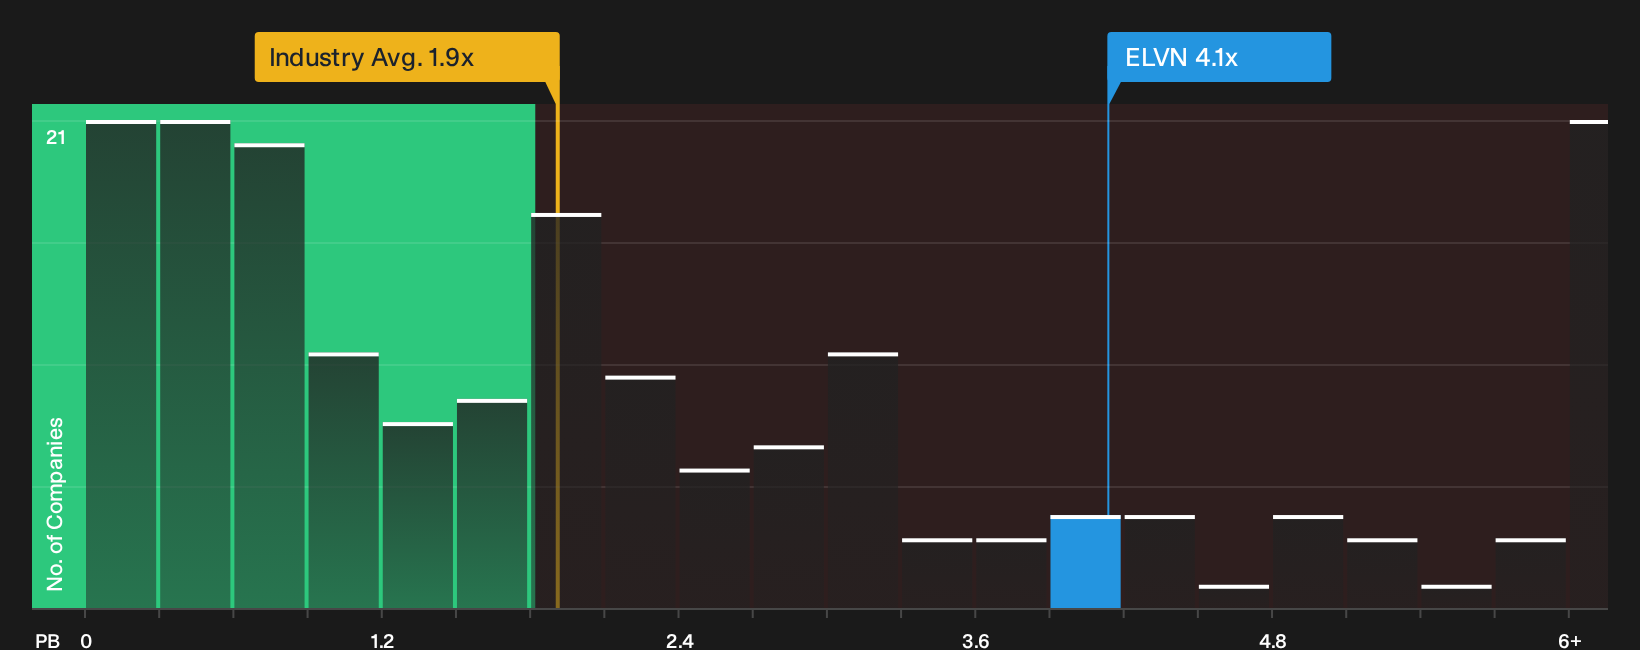
Step away from analyst targets for a moment and look at the simple price to book yardstick. Enliven Therapeutics trades at a P/B of 4.1x, which is more than double the broader US Pharmaceuticals industry at 1.8x, even though it is still loss making with no current revenue.
Compared with closer peers on this same metric, the stock screens cheaper, with the peer average P/B at a very high 59x. That mix, expensive versus the sector but cheaper than a tighter peer set, highlights potential valuation risk if sentiment cools and the ratio drifts toward the wider industry. It also highlights potential upside if specialist investors continue to pay higher multiples for late stage oncology pipelines. Which side of that trade you prioritize will depend on your own time horizon.
For a deeper breakdown of what this pricing gap could mean in practice, including how the current multiples compare with fundamentals and risks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around Enliven Therapeutics feels familiar, treat it as a prompt to move quickly on your homework and compare the upside stories with the caution flags using the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Enliven Therapeutics?
Do not just stop at Enliven Therapeutics. Use these ready made ideas to pressure test your watchlist and avoid missing opportunities other investors overlook.
- Target quality at a discount by scanning a focused pool of potential bargains using the 39 high quality undervalued stocks.
- Prioritize capital preservation and steadier journeys through the market by checking the 29 resilient stocks with low risk scores.
- Strengthen your shortlist with businesses that carry less financial strain by reviewing the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com