


EN
What IGM Financial (TSX:IGM)'s Asset Growth Means For Shareholders
- IGM Financial reported third quarter 2026 revenue of C$1,317.12m and net income of C$487.54m, with higher earnings per share and larger assets under management helped by the Northleaf integration and strong flows across IG Wealth, Mackenzie and affiliates.
- The firm paired record adjusted earnings per share with a declared C$0.62 dividend and rising fee based assets, highlighting how its multi platform wealth, asset management and affiliate model is generating cash that can fund AI investments, product streamlining and ongoing capital returns.
- We will look at how IGM Financial's investment narrative is affected by record adjusted earnings and asset growth after integrating Northleaf.
See how IGM Financial's fee-driven model compares with other wealth and asset managers by reviewing a curated set of 6 high quality undervalued stocks that may be pricing in similar earnings power.
IGM Financial Investment Narrative Recap
To own IGM Financial, you need to believe its fee based wealth and asset management model can keep turning a larger asset base and affiliate network into resilient earnings, even as headline revenue is expected to be broadly flat. The latest quarter, with higher revenue, net income and EPS than a year ago, supports that earnings power story.
The near term swing factor is whether cost savings and AI spending can offset fee pressure while assets from IG Wealth, Mackenzie and Northleaf keep feeding the fee engine. The biggest risk is that guided expense growth and lower fee rates bite into margins faster than efficiency gains or inflows can offset.
The most relevant announcement for this earnings print is IGM Financial’s third quarter 2026 result, which showed revenue of C$1,317.12m and net income of C$487.54m, both higher than a year earlier. Basic EPS from continuing operations reached C$2.12 for the quarter and C$4.45 for the first nine months of 2026.
Those figures give you fresh evidence on how the fee based model is holding up while the group invests in AI tools and integrates Northleaf. Stronger earnings and a C$0.62 dividend highlight current cash generation, but they also raise the bar. Any future slowdown in flows, continued fee compression or expense creep would be more visible against this elevated profitability level.
What The Current Forecasts Assume For IGM Financial
IGM Financial's narrative projects CA$4.5b revenue and CA$1.4b earnings by 2029. This aligns with analyst assumptions that revenue remains broadly flat while profit margins widen, which takes earnings from CA$1.2b today to CA$1.4b, an increase of about CA$200m.
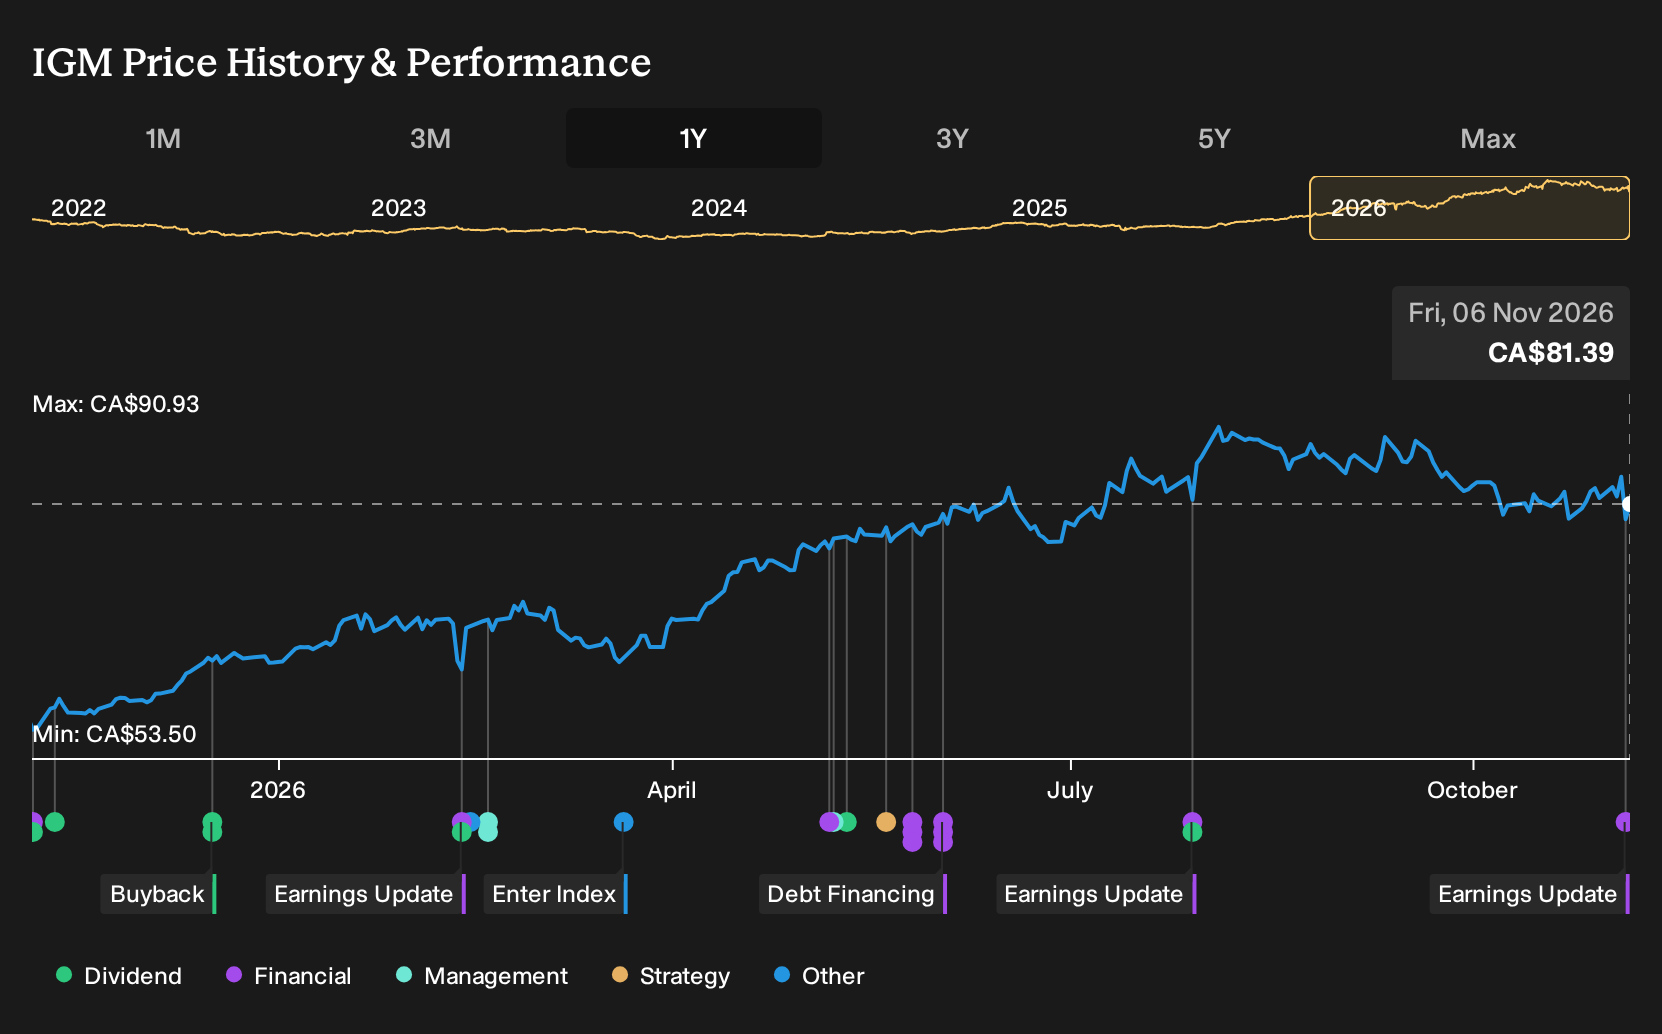
Uncover why IGM Financial's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between C$89.25 and about C$92.71, so a couple of retail investors see IGM Financial trading a little below their models. When you set those views against risks such as fee pressure or higher expenses, you can arrive at very different conclusions on future earnings resilience. Opinions can differ widely, so review multiple Community viewpoints before deciding how these numbers fit your own thesis.
Explore another IGM Financial fair value estimate, including one that suggests it could be worth just CA$89.25.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IGM Financial research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for IGM Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IGM Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond IGM Financial?
If you are weighing IGM Financial against alternatives, it can help to scan a wider field of stocks that share some of the qualities you care about, whether that is resilience, income or balance sheet strength.
- If capital preservation sits high on your list, look through a carefully curated 9 resilient stocks with low risk scores that focuses on companies with more measured risk profiles.
- For investors who want income to play a central role, scan a hand picked set of 3 dividend fortresses that offer higher yields with a focus on consistency.
- When balance sheet quality matters most, review a list of solid balance sheet and fundamentals (5 results) that filters for stronger finances and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com