


EN
What Evergy (EVRG)'s Raised Earnings Guidance Means For Shareholders
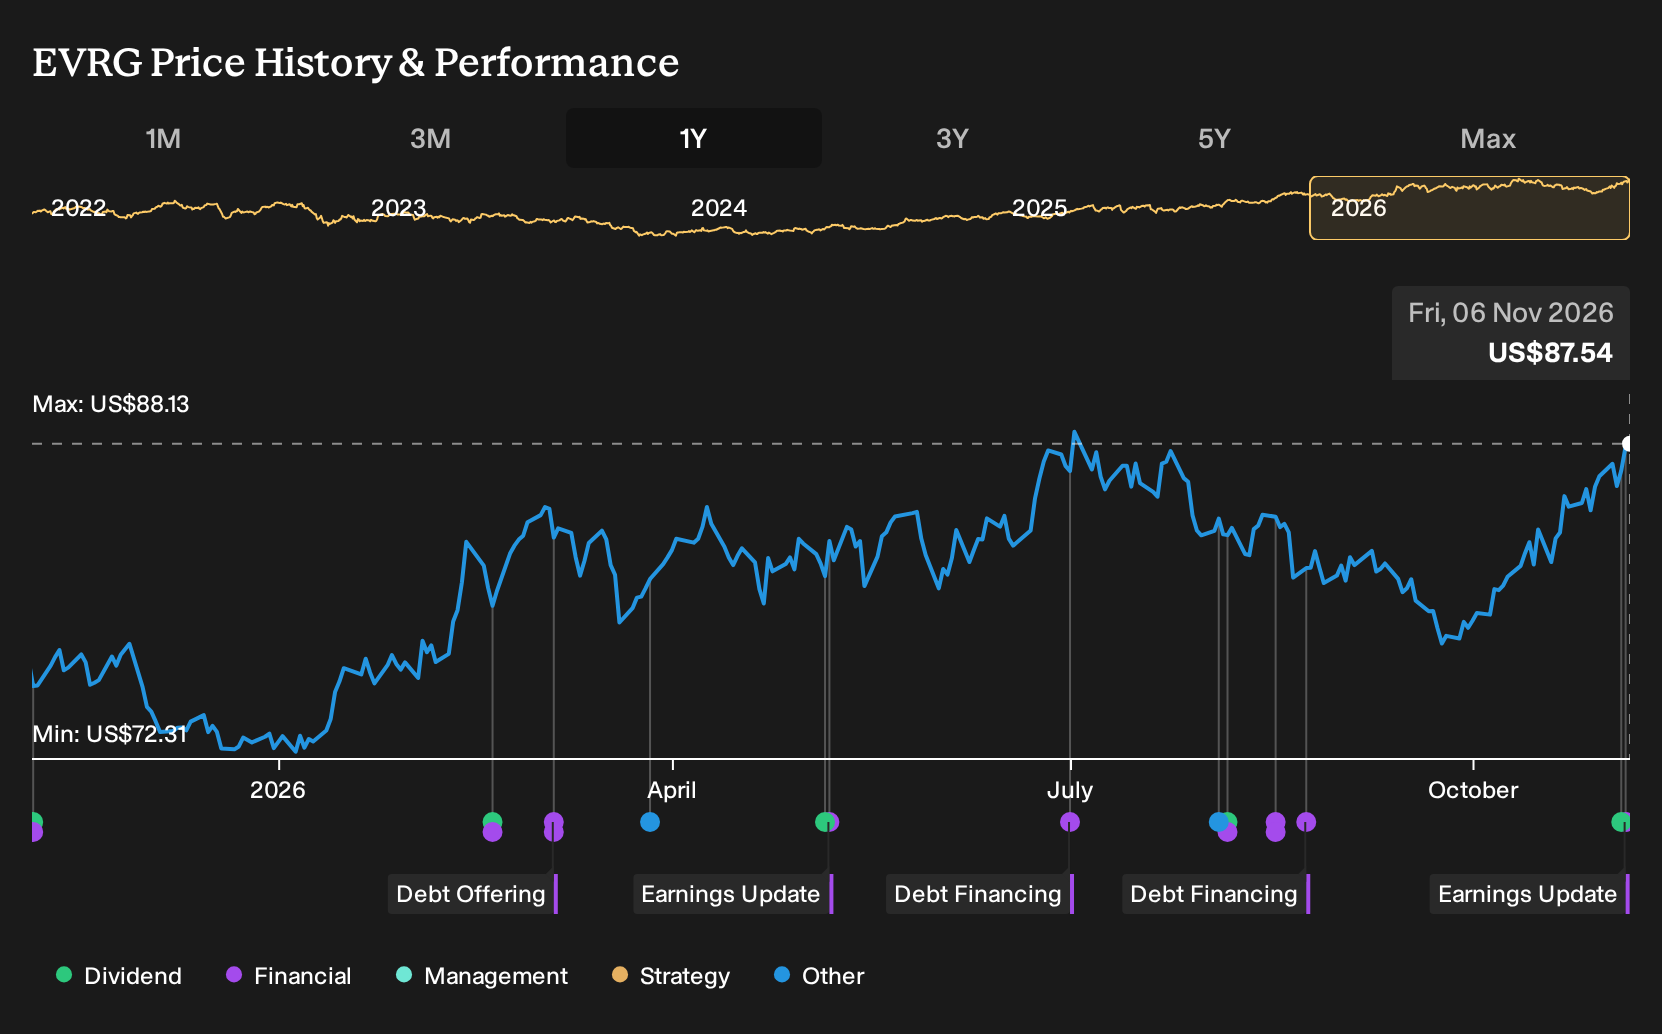
- Evergy reported third quarter 2026 sales of US$2,096.6 million and net income of US$612.9 million, raised full year adjusted earnings guidance to US$4.35 to US$4.50 per share, increased the quarterly dividend to US$0.7225 per share, and outlined a large scale data center expansion with Digital Realty.
- The combination of higher earnings guidance, a 4% dividend uplift and a potential US$4 billion capital program with Digital Realty indicates that Evergy is focusing on large load growth while committing more cash returns to shareholders.
- The next step is to examine how Evergy's raised earnings guidance, supported by expanding data center load, could influence the longer term investment narrative.
Scan 42 power grid technology and infrastructure stocks that could also benefit as data center demand reshapes electricity networks and long-term infrastructure investment themes.
Evergy Investment Narrative Recap
For Evergy, the core view is that large data center and industrial demand, combined with heavy grid and generation investment, can support steady earnings while keeping regulators focused on customer bill impacts. The raised 2026 adjusted EPS guidance to US$4.35 to US$4.50 reflects that view. In the near term, the key swing factor remains execution on new large load contracts and the timing of their usage.
The biggest risk remains on the cost and funding side. Evergy plans high capital spending and already has interest coverage flagged as tight, with dividends not well covered by free cash flow. The latest results do not remove that concern, so the balance among growth spending, financing costs and bill affordability stays central for the next phase.
The most relevant update is the letter of intent with Digital Realty for a potential 1.4 GW project and roughly US$4 billion of capital investment. This is directly tied to Evergy’s data-center-led demand thesis and its plan to grow the regulated rate base through 2030 and beyond. The new agreements that add about 110 MW to existing large load contracts point in the same direction.
This opportunity comes with execution and regulatory risk. Building that much capacity requires Evergy to manage construction costs, interest expense and equity issuance while maintaining acceptable returns. At the same time, regulators will monitor customer affordability and reliability. For you as a shareholder, the key question is whether future earnings from those long-term electric service agreements will comfortably offset the additional capital expenditure and funding burden.
Evergy Forecasts and What Needs To Happen
Evergy's narrative projects US$7.3b revenue and US$1.3b earnings by 2029. This lines up with analysts assuming 6.4% yearly revenue growth and an earnings increase of about US$374m from US$925.8m today.
Uncover why Evergy's fair value indicates a valuation gap that is roughly in line with its current price.
Exploring Other Perspectives
Simply Wall St Community members currently publish just two fair value estimates for Evergy, stretching from about US$61.51 to US$89 per share, so views already span a wide bracket. Those opinions were formed before the latest earnings beat, dividend uplift and data center capital plan, so you may want to review several fresh viewpoints on how these factors could reshape Evergy's risk and return profile.
Explore another Evergy fair value estimate, including one that suggests it could be worth as much as $89.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Evergy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Evergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evergy's overall financial health at a glance.
Looking for more investment ideas beyond Evergy?
If Evergy has sharpened your focus on regulated utilities and steady cash flows, it can help to compare that story with a broader mix of opportunities using the Simply Wall St Screener.
- For investors who want potential upside without stretching on quality, scan a curated 39 high quality undervalued stocks that already screen well on both fundamentals and valuation.
- If capital preservation sits near the top of your priority list, filter for companies in the 29 resilient stocks with low risk scores to see which businesses currently show more resilient risk profiles.
- To broaden your watchlist with lesser known opportunities, track down a 19 high quality undiscovered gems that pair solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com