


EN
Learn Why The Bull Case For RB Global Stock Could Change Following Third Quarter Results
- RB Global is preparing to release its third quarter 2026 results, with expectations for year over year gains in earnings and revenue supported by demand for commercial equipment and its digital marketplace services.
- The upcoming report will test how well RB Global is converting sector wide demand for technology enabled business services into fee based marketplace revenue and operating efficiency.
- We will examine how RB Global's investment narrative is influenced by expectations for third quarter earnings supported by equipment demand.
Scan how RB Global's setup compares with other fee based platforms by reviewing a curated list of 19 high quality undiscovered gems that could be next in line for increased marketplace traction.
RB Global Investment Narrative Recap
To own RB Global, you need to believe its equipment and vehicle marketplaces can keep turning asset volume into fee income while digital tools hold the cost base in check. The upcoming third quarter print matters mainly as a check on that conversion, especially after a year where the stock has lagged broader commercial services benchmarks.
The key near term catalyst remains execution in higher value categories like salvage and agriculture without further erosion in service take rates, which have already been under pressure. The biggest current risk is that higher fuel, yard and technology spending absorb most of the gross transaction value uplift, leaving margins and free cash flow tight.
In the context of the third quarter update, the most relevant backdrop is RB Global's push into sector specific marketplaces such as automotive salvage, government surplus and agriculture through BigIron. This expansion is already embedded in expectations for revenue and earnings growth, so any commentary around vertical scaling will likely be parsed closely by investors.
These same initiatives tie directly into the catalysts around digital tools like Total Loss Predictor, redesigned mobile bidding and AI enabled sales roles. They are intended to support throughput and operating leverage over time, yet they also require heavy capital spending. The tension between that investment load and already pressured take rates remains central to how the story is viewed.
RB Global Forecasts and Analyst Assumptions
RB Global's narrative projects US$6.3b revenue and US$946.3 million earnings by 2029. This profile lines up with analyst assumptions of 9.1% yearly revenue growth and an earnings increase of about US$509.9 million from US$436.4 million today.
Uncover why RB Global's fair value indicates a 38% potential upside to its current price, which could narrow quickly.
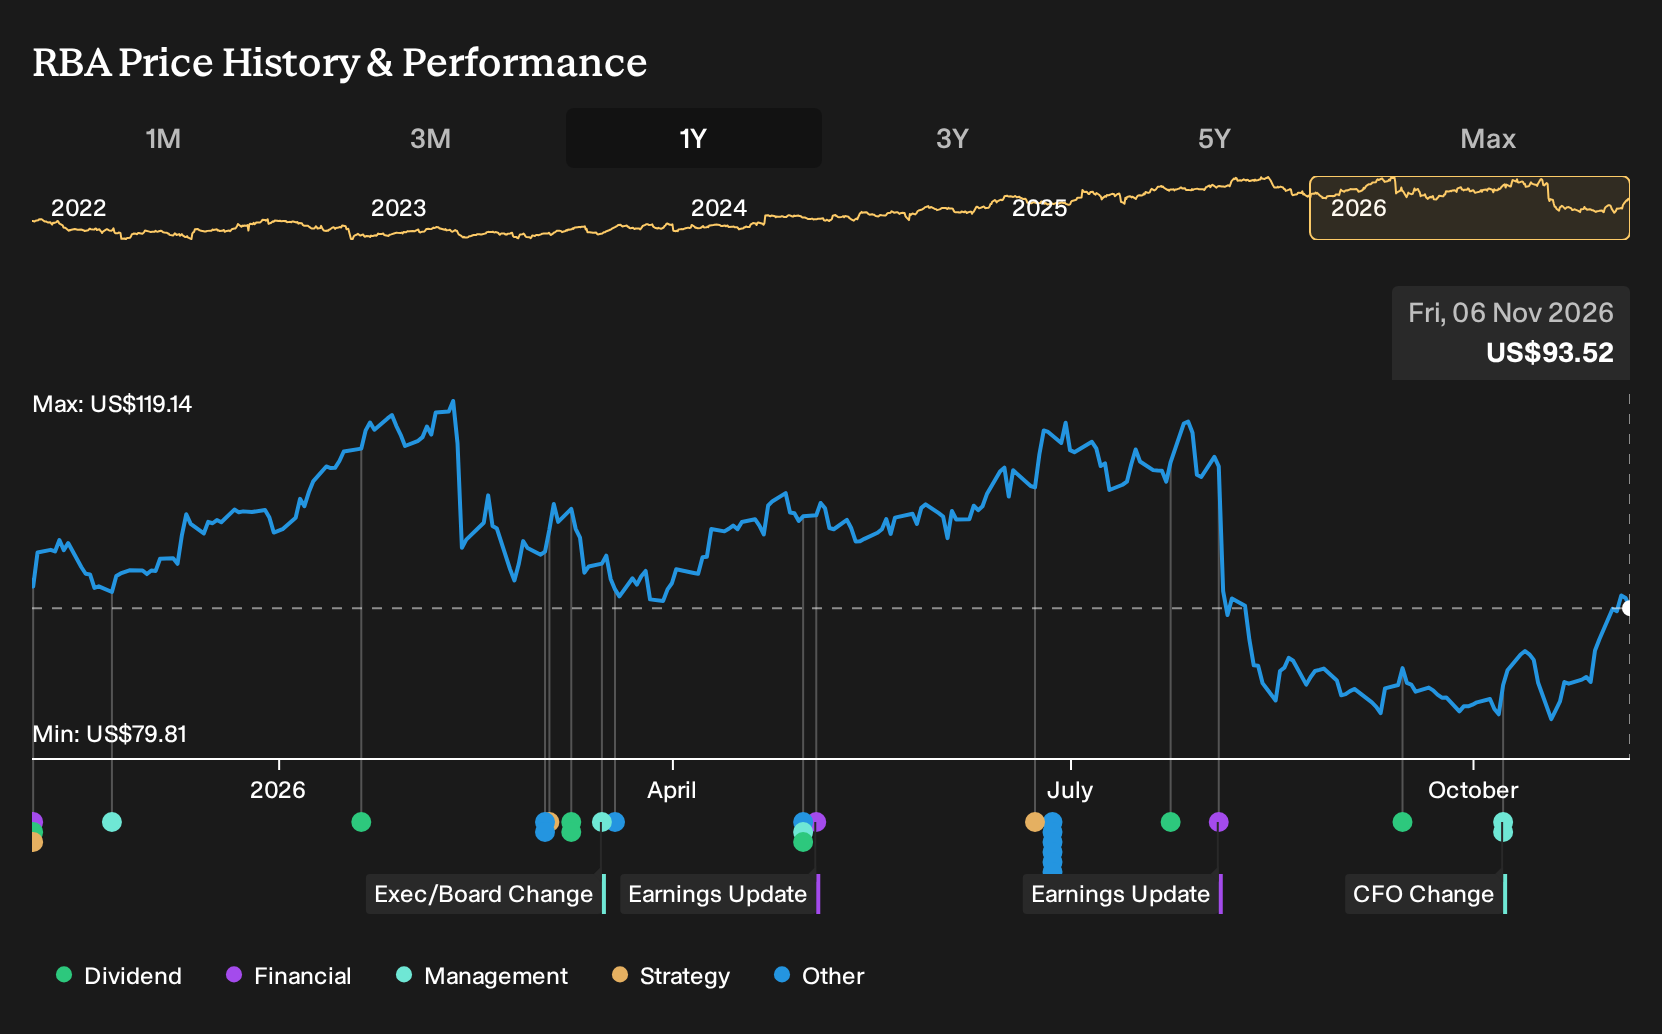
Exploring Other Perspectives
One alternate angle on RB Global focuses on capital returns rather than margin pressure. The most optimistic analysts leaned into the doubled US$1b buyback and higher dividend, arguing that US$6.3b of revenue and about US$980.9 million of earnings by 2029 could justify a richer story. Those forecasts came before this latest earnings update, so treat them as moving pieces and compare several viewpoints before deciding how this new information might shift your own expectations.
Explore 3 other RB Global fair value estimates, including one that suggests as much as 145% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RB Global research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RB Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RB Global's overall financial health at a glance.
Looking For More Ideas Beyond RB Global?
If the RB Global story has you thinking about portfolio gaps or fresh angles, it can help to line it up against other businesses with different strengths and risk profiles using the Simply Wall St Screener.
- For investors who care most about resilient balance sheets and solid fundamentals, scan a focused list of solid balance sheet and fundamentals (24 results) that might complement or contrast with RB Global's risk profile.
- If capital preservation ranks high on your checklist, weigh RB Global against a curated pool of 29 resilient stocks with low risk scores that score well on financial and volatility measures.
- Those hunting for mispriced quality can set RB Global alongside a targeted group of 39 high quality undervalued stocks that combine stronger fundamentals with potentially more attractive entry points.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com