


EN
Can Olin (OLN) Hold Its Undervalued Case After Mixed Results?
Olin Corporation has seen its share price under pressure in recent years, so the key issue now is whether the current US$17.31 level still makes sense when you line that up against the sales the business is producing. With the spotlight back on the stock after fresh earnings and merger plans, the question is how much of the underlying revenue story is already reflected in today's valuation.
- Over the past 5 years the share price has fallen 70.1%, which puts the focus squarely on whether the current market value still reflects what Olin can earn from its sales base.
- Recent profit, revenue shortfall against analyst expectations, and ongoing work toward a merger with Huntsman can all influence how investors think about future sales levels, pricing power, and the timing of cash flows that support the stock.
- The analysts covering Olin have run their own numbers. See what analysts think Olin's shares could be worth.
The stock's next move may depend on whether Olin's current market value is adequately backed by its sales when viewed through this lens.
If you are weighing Olin against other companies where sales and valuation are under the microscope, it can help to line it up beside 39 high quality undervalued stocks.
Is Olin Still Cheap on Sales?
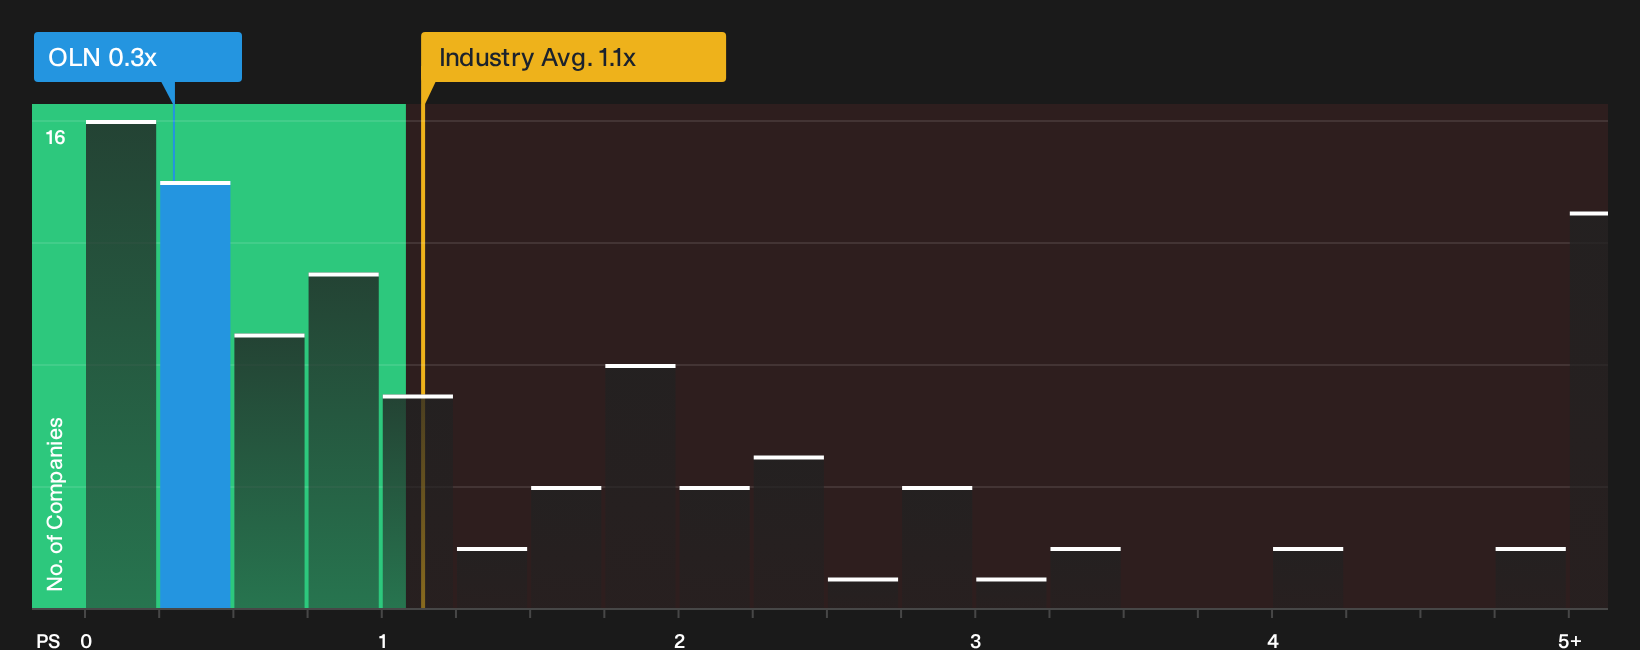
P/S makes sense for Olin because revenue is a cleaner yardstick here than earnings, which can swing around with cycle and merger costs. On this measure, the stock trades on a P/S of 0.3x, which is well below the Chemicals industry average of about 1.1x and also lower than the broader peer group near 1.3x. The fair multiple implied by the valuation model, which blends the company’s growth profile, profitability, size, and risk, sits above the current P/S. As a result, the shares screen undervalued on this framework.
Because the latest quarterly update combined an earnings beat with a revenue shortfall and merger work with Huntsman that is still moving through approvals, the market is pricing Olin’s sales at a discount even as those catalysts reshape how future cash flows could look. For investors, that gap between today’s P/S and the model’s fair range is the key number to weigh against balance sheet strength, merger execution risk, and how comfortable you are with chemicals demand cycles. Explore the numbers behind Olin's P/S valuation.
The Olin Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Olin's low P/S puzzle leaves off. They spell out which future paths for growth, margins, and earnings would need to hold for the stock to be worth much more or meaningfully less than today’s price, and they sit on the Community page. Each scenario anchors a fair value to a clearly defined mix of potential catalysts and risks so you can track which version of Olin's story is actually unfolding over time.
Community views on Olin are split between cost and merger upside on one side and concern about leverage, outages, and chlor alkali pressure on the other.
Bull case: 31% undervalued
"The Beyond250 program and related segment initiatives that are tracking ahead of the original US$250 million cumulative target by 2028 open scope for additional fixed cost takeout…"
Discover why this Narrative puts Olin at 31% undervalued.
Bear case: 15% overvalued
"Bearish analysts expect Olin to face sustained pressure on profitability if chlor alkali fundamentals soften further, litigation cash outflows keep leverage elevated, and outage related disruptions continue to drag on earnings…"
Explore why this Narrative puts Olin at 15% overvalued.
One more Olin check that sits beyond the share price math
Price ratios only tell you what the market is willing to pay, not who is steering Olin or how their rewards line up with your interests. See who runs Olin and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com