


EN
Is Raised 2026 Guidance Altering The Investment Case For Benchmark Electronics (BHE)?
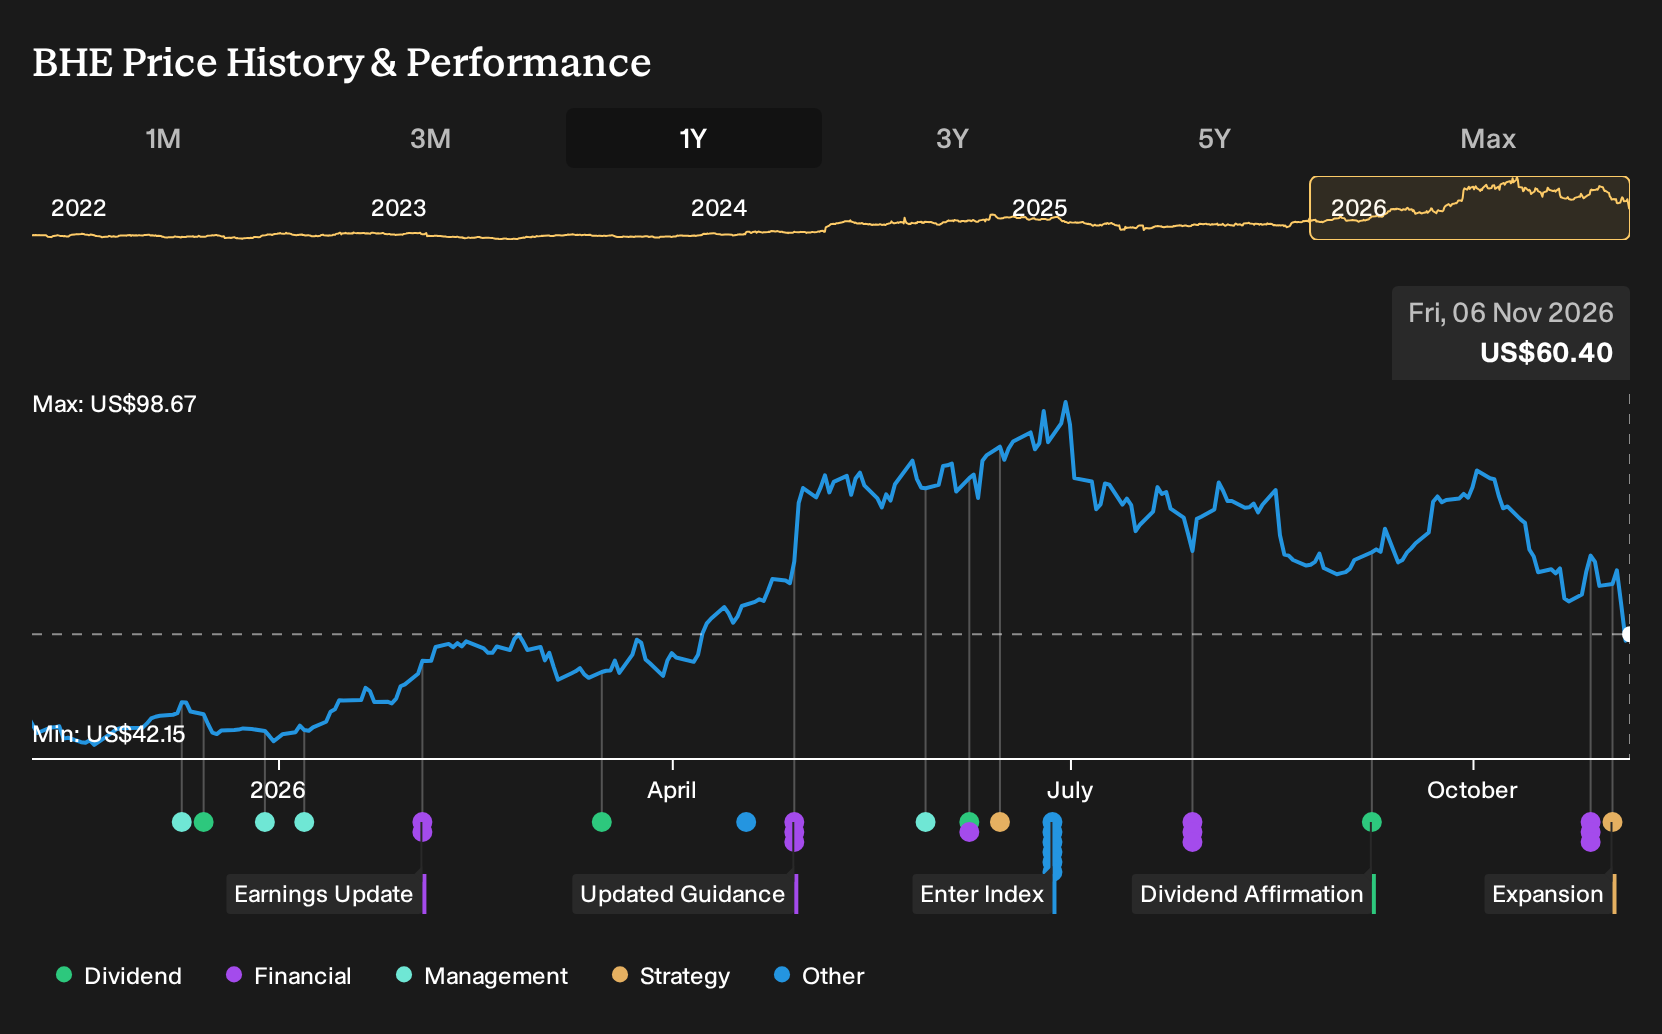
- Benchmark Electronics recently reported record third quarter 2026 results, issued fourth quarter guidance of US$815 million to US$855 million in revenue and US$0.58 to US$0.64 in diluted GAAP EPS, and raised its full year 2026 outlook.
- The expanded U.S. manufacturing footprint for Oxide Computer Company highlights Benchmark Electronics' role in complex on premises cloud and AI infrastructure builds, where supply chain control and close engineering collaboration matter.
- We will now assess how Benchmark Electronics' raised 2026 guidance tied to advanced computing demand could reshape the existing investment narrative.
Scan beyond Benchmark Electronics and see how other on premises cloud and AI hardware partners stack up across 52 AI infrastructure stocks.
Benchmark Electronics Investment Narrative Recap
For Benchmark Electronics, the core belief is that advanced computing, AI infrastructure and medical programs can keep filling its expanded capacity and offset bumps in other end markets. The near term swing factor is whether the current wave of AI centric design wins and on premises cloud projects, including Oxide, translate into steady orders across 2027.
The biggest near term risk is that tight component supply, long lead times and a rich P/E combine with any slowdown in bookings to pressure earnings quality. The Oxide production expansion and higher 2026 guidance do not remove that risk, but they do support the case that current demand is real rather than purely narrative.
The raised full year 2026 outlook is the announcement that matters most here. Management now expects about 16% revenue growth and has guided fourth quarter sales to US$815 million to US$855 million with diluted GAAP EPS of US$0.58 to US$0.64. That sits alongside record third quarter revenue and earnings growing nearly twice the rate of sales.
For you as an investor, the question is whether this guidance bump, supported by the Oxide expansion, is enough to justify a higher than peer P/E and recent insider selling. If Benchmark Electronics can keep converting AI, Semi Cap and medical opportunities into booked programs while managing component constraints, the raised guidance could be an early proof point rather than a peak.
Benchmark Electronics is tied to analyst models that point to US$3.7b in revenue and US$145.3 million in earnings by 2029, assuming annual revenue growth of 9.1% and an earnings increase of roughly US$92 million from US$53.1 million today.
Uncover how Benchmark Electronics' fair value indicates a potential upside of 42% to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate view focuses on utilization risk for Benchmark Electronics. The most cautious analysts worried that new capacity like Penang 4 could sit underused and had pencilled in 7.1% annual revenue growth and US$119.9 million in 2029 earnings before this Oxide expansion news. That shows how sharply opinions can differ, and why it helps to compare several narratives.
Explore another Benchmark Electronics fair value estimate, including one that suggests there could be as much as 16% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Benchmark Electronics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Benchmark Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Benchmark Electronics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Benchmark Electronics?
If you want to round out your watchlist around Benchmark Electronics, it can help to scan a wider set of businesses that share some of the qualities you are looking for, whether that is resilience, income or untapped potential.
- For investors who want a margin of safety and quality together, start with companies that screen as attractively priced on fundamentals using the 39 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than chasing every spike, consider stocks that pass the 29 resilient stocks with low risk scores to see which businesses score well on resilience.
- Those who like the idea of finding tomorrow's leaders before the crowd can use the 19 high quality undiscovered gems to focus on under-the-radar companies with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com