


EN
Parsons (PSN) Dropped, What Is Behind the Latest Attention?
Parsons stock reacts to earnings and guidance update
Parsons (PSN) drew fresh attention after its third quarter 2026 earnings report, which combined softer profitability with slightly higher sales and a reaffirmed full year revenue outlook that helped anchor expectations.
Recent trading tells a mixed story for Parsons. The stock has pulled back with a 1-day share price return of 2.86% and a 7-day return of 3.53%, even after a strong 30-day share price gain of 16.37% following earnings and the Riyadh Metro contract update. Over the longer term, the total shareholder return is down 43.09% over one year and 21.88% over three years, but up 32.95% over five years, suggesting that shorter term momentum is improving against a weaker recent track record.
Scan how Parsons compares with other contractors that are focusing on long-term infrastructure and defense work by reviewing our hand picked 42 power grid technology and infrastructure stocks alongside this earnings reaction.
Parsons now trades well below its recent highs yet has just logged a sharp 30 day rebound. Does that set up a better entry now or a case for patience until the next pullback as valuation comes into focus?
Most Popular Narrative: 18% Undervalued
Parsons closed at $48.90 against a widely followed fair value estimate of $59.64. This frames the recent pullback as a valuation debate rather than a simple sentiment swing.
The main thing that has to go right is Parsons successfully executing its portfolio mix shift toward higher margin, product and AI driven federal work while continuing to wind down and exit lower return or higher risk construction and advisory contracts without further large charges.
The current valuation implies the share price reflects concern about guidance cuts and recent one off losses more than the size and duration of Parsons’ backlog, product programs and identified long runway in infrastructure and environmental remediation.
See why 13 investors see Parsons as 18% undervalued.
Result: Fair Value of $59.64 (UNDERVALUED)
Still, the Parsons narrative can break if contract exits trigger more one-off losses, or if U.S. federal funding shifts again and pressures future guidance.
Find out about the key risks to this Parsons narrative.
Another View: Parsons looks expensive on earnings multiples
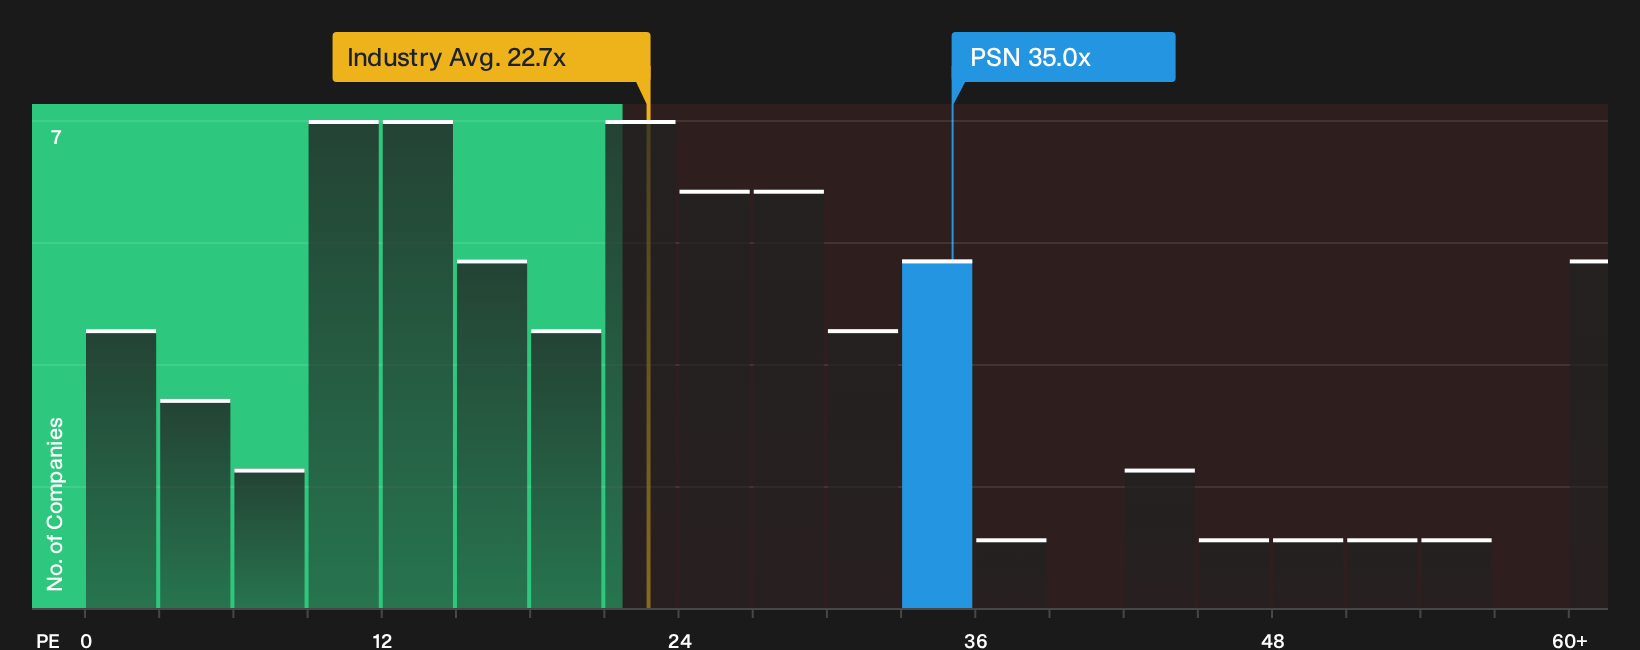
The fair value estimate of $59.64 suggests Parsons is undervalued on future cash flows. On simple earnings, the picture is much tougher. The stock trades on a P/E of 35x compared with 22.9x for the US Professional Services group and a fair ratio of 30.6x, which points to a richer price tag that could limit upside if sentiment cools.
That kind of gap can matter in practice because investors are paying a higher price today for each dollar of current earnings than both peers and the fair ratio imply, even while the share price already reflects a long runway of expected profit growth. Is this a valuation setup that rewards patience, or one that depends heavily on everything going right?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Parsons so far. Act quickly by checking the underlying data, weighing both the upside and the setbacks, then drill into the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Parsons?
If Parsons has your attention, do not stop here. Use focused screens to surface other opportunities that match your risk tolerance and return goals.
- Target stability first and stress test your portfolio against shocks by running a 29 resilient stocks with low risk scores.
- Look for quality at a sensible entry point with a 39 high quality undervalued stocks that filters for fundamentals, not hype.
- Identify potential early movers before the market pays attention by scanning a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com