


EN
Is Sterling Infrastructure (STRL) Fully Priced Despite Its 7x Run?
Sterling Infrastructure has seen its share price swing sharply in recent years, and the latest pullback puts the focus squarely on whether the current valuation still lines up with the company’s earnings power. With the stock resetting after a strong long term run, the question now is how much of its profit story is already embedded in today’s price.
- Over the past 5 years, Sterling Infrastructure has delivered a gain of roughly 7x, which puts a lot of long term expectation into the earnings case that investors are now rethinking.
- Recent coverage highlights a large and growing backlog tied to complex data center and mission critical projects, which can influence how durable future earnings and cash flows may be as the order book converts into revenue.
- Your read on Sterling Infrastructure is one view; the desks covering it have another. See what analysts think Sterling Infrastructure's shares could be worth.
The issue now is whether Sterling Infrastructure’s recent share price, after a period of sharp gains and a more recent slide, is justified by the earnings it is generating today and is reasonably expected to produce over time.
If you are weighing Sterling Infrastructure against other ways to play this theme, it can help to compare it with 52 AI infrastructure stocks.
Is Sterling Infrastructure a Bargain on Earnings?
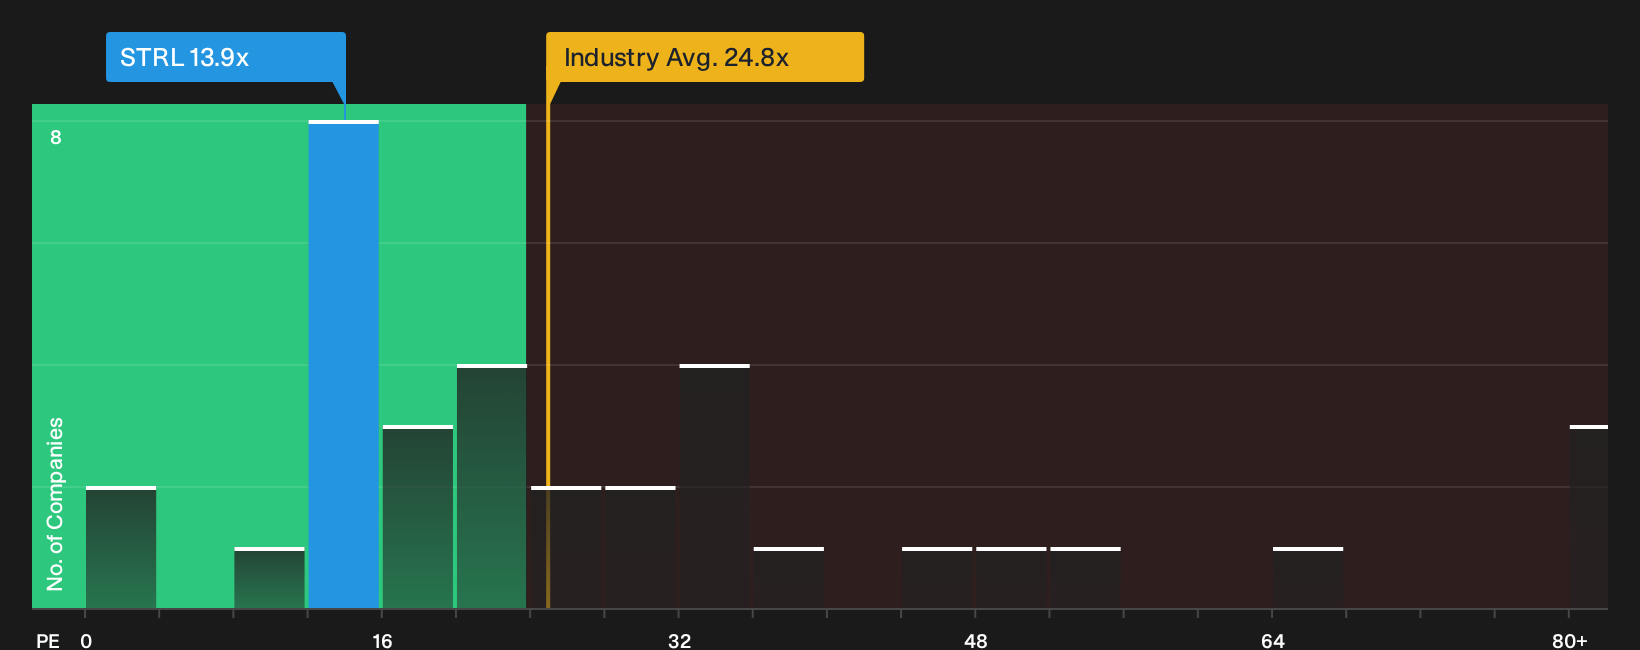
P/E works well for Sterling Infrastructure because the story is very much about what investors are willing to pay for each dollar of earnings. The stock trades on a P/E of about 13.9x, which is well below the broader construction sector average of roughly 24.8x and also under the peer group at about 21.1x. Based on a fair multiple that blends the company’s growth profile, profitability, risk and size, the current P/E screens on the cheap side rather than rich.
Because the recent AI data center headlines point to a large backlog and multi year project visibility, the discount in Sterling Infrastructure’s P/E ratio suggests the market is pricing those earnings streams cautiously relative to sector and peer benchmarks. That gap invites you to weigh whether the backlog and cash generation potential justify a re rating or whether the lower multiple is a reasonable buffer for execution and cycle risk on complex infrastructure work. Explore the numbers behind Sterling Infrastructure's P/E valuation.
The Sterling Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the Sterling Infrastructure valuation puzzle leaves off by spelling out in plain terms what trajectory for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today on the Community page. Each Narrative sets out Sterling Infrastructure's implied fair value as a thesis about how the business performs over time, so you can watch how that idea holds up as new information arrives.
One of the top community narratives on Sterling Infrastructure: 68% undervalued
Extremely long duration hyperscaler data center campuses, with management citing projects spanning 8 to 12 years of construction plus additional electrical work…
Discover why this Narrative puts Sterling Infrastructure at 68% undervalued.
One more piece of the Sterling Infrastructure story investors should not skip
Sterling Infrastructure’s valuation only tells part of the story, because our checks have also picked up specific risk signals that could change how you weigh everything you have just read. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com