


EN
Top 3 Canadian Undervalued Stocks To Watch In November 2026
Central banks are tightening policy to tackle inflation, and that has pushed borrowing costs higher across global markets. When money is no longer cheap, investors often pay closer attention to companies that already generate solid cash and trade below what detailed cash flow models suggest they are worth. This article looks at three Canadian stocks that screens flag as discounted on this basis and explains why cash flow matters.
The three examples that follow are only a sample of what shows up on this cash flow valuation theme, and the full screen surfaces 0 more companies with similar stories that are not covered below. To see the wider opportunity set, head straight into the Undervalued Stocks Based On Cash Flows screener to identify candidates, analyze their cash generation, and focus on the highest conviction ideas.
Stantec (TSX:STN)
Overview: Stantec provides planning, design, and consulting services for infrastructure and sustainable water, wastewater, and stormwater projects that generate fee-based cash flows.
Operations: Stantec generates about CA$1.6b in Canada, CA$3.6b in the United States, and CA$1.7b from global operations across multiple regions.
Market Cap: CA$11.9b
Stantec matters on this cash flow screen because its water focused infrastructure work produces long term fee streams that are relatively visible and contract based, which makes discounted cash flow models a practical way to judge whether the current share price reflects those projects.
"Recent large acquisitions such as Page, Cosgroves and Ryan Hanley have significantly expanded Stantec's presence in the U.S., New Zealand and Ireland. Demand for infrastructure upgrades, water and wastewater treatment, energy transition and climate adaptation projects remains very strong globally."
What happens to Stantec’s valuation hinges on how one quiet shift in its margin profile interacts with that expanding, multi year backlog.
That margin shift is the real hinge, and the full narrative for Stantec explains how cash flow strength, capital discipline, and contract mix could be separating from headline earnings volatility.
OceanaGold (TSX:OGC)
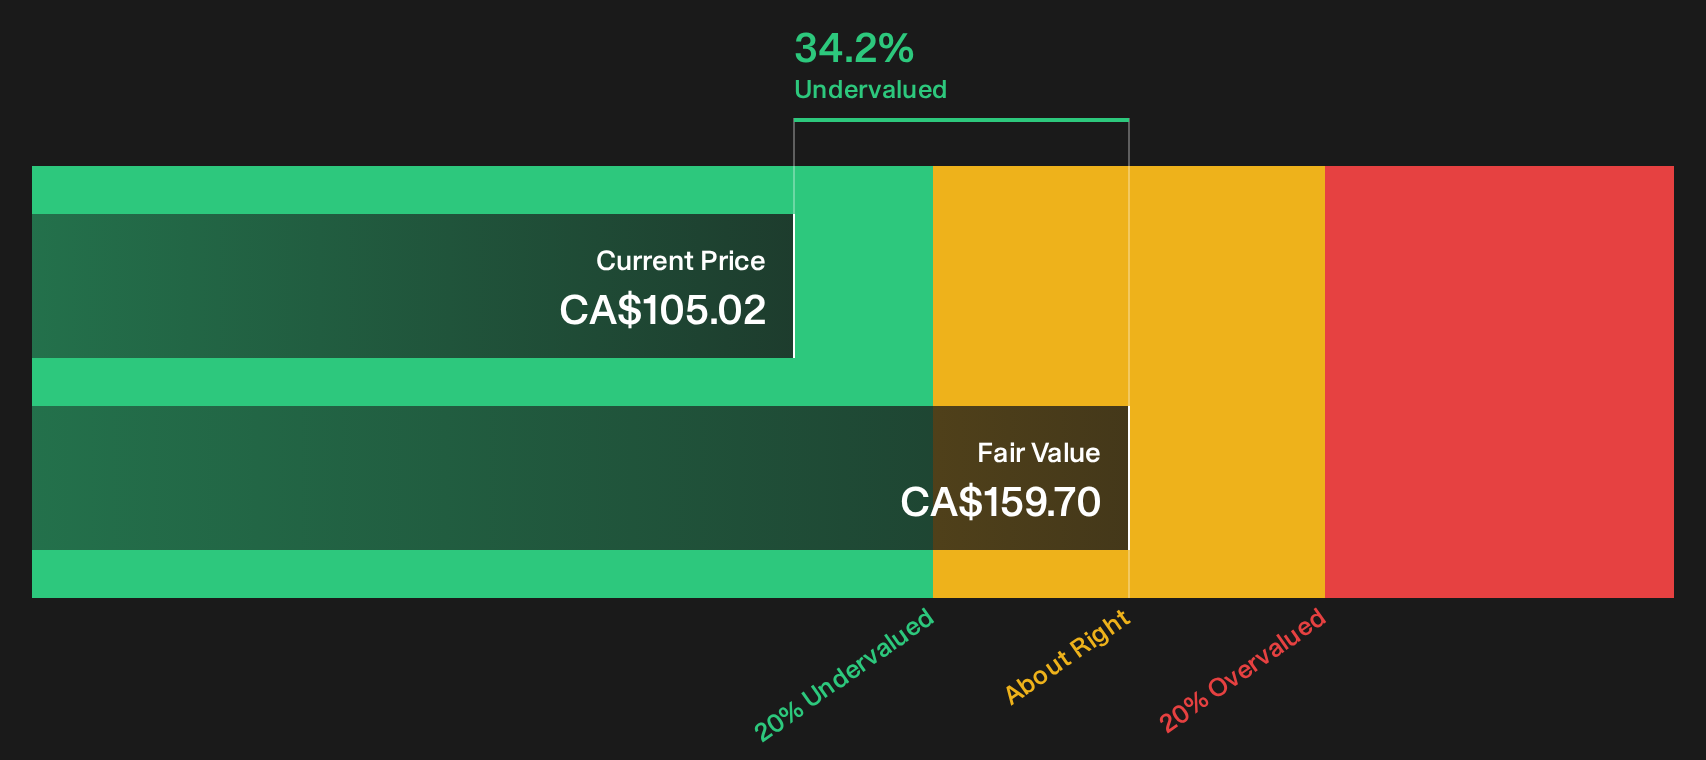
Overview: OceanaGold runs producing gold and gold copper mines, mainly Haile, Didipio, and Macraes. These operations anchor the cash flows used in its DCF valuation.
Market Cap: CA$8.5b
OceanaGold draws attention in this cash flow focused screen because active mines feed a steady stream of production that can be modelled in detail. This level of detail matters when you are judging whether the current share price lines up with long term cash generation.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
A key consideration is what happens if one crucial assumption about how long high grade ore remains available starts to shift just as OceanaGold leans more heavily on it.
If that ore story is the real swing factor, you need the full narrative for OceanaGold to see how OceanaGold’s cash flows could accelerate or stall from here.
AGF Management (TSX:AGF.B)
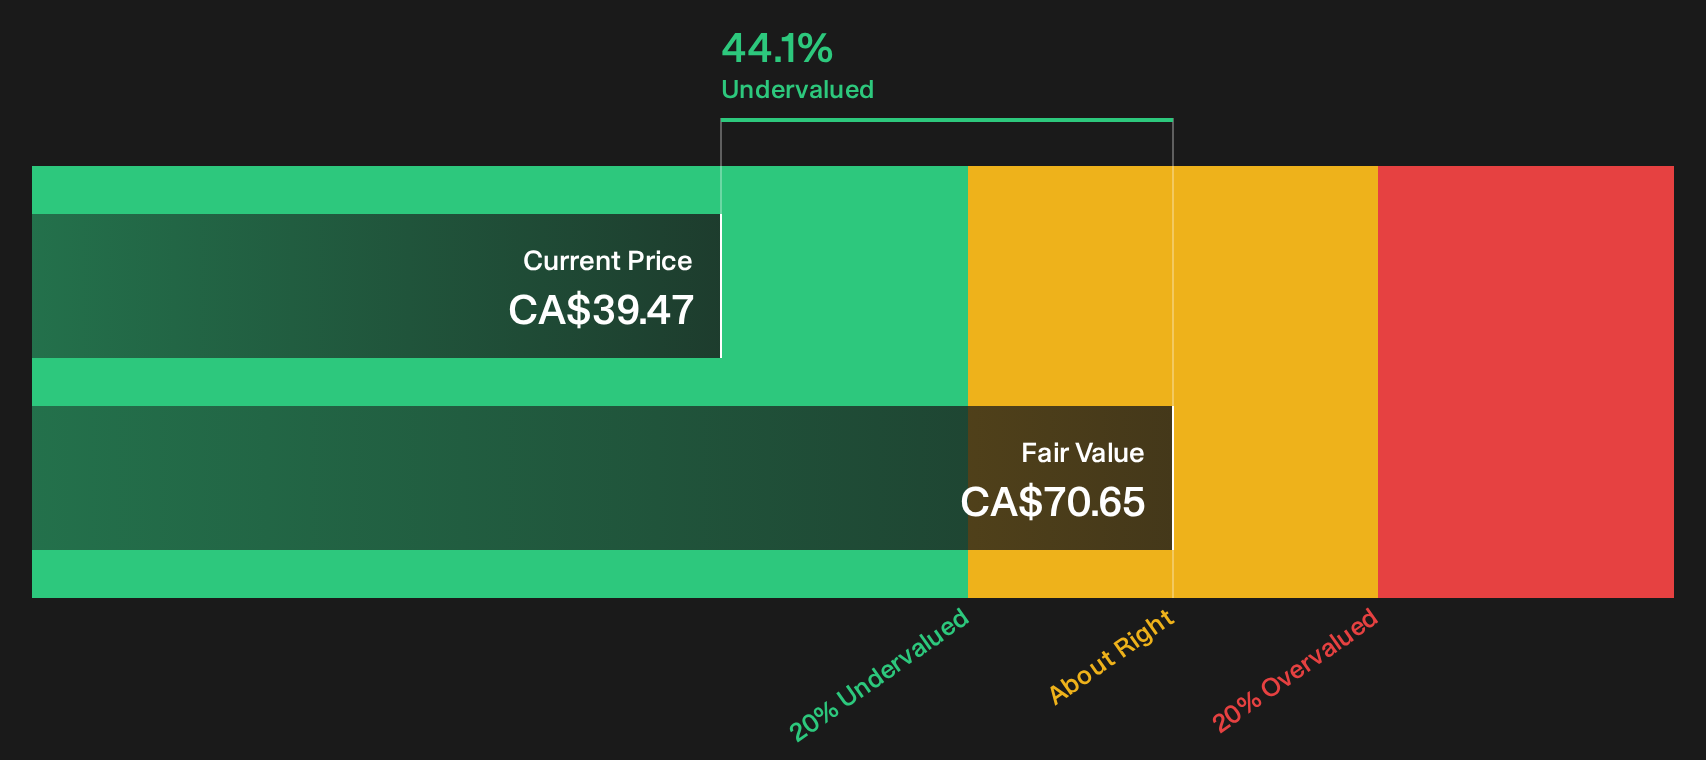
Overview: AGF Management runs mutual funds, portfolios and other investment products that generate recurring fee income from managing client assets.
Operations: AGF Management generates about CA$612 million in revenue from its asset management segment, anchored in fee based investment services.
Market Cap: CA$939 million
AGF Management matters for a cash flow based screen because its mutual funds and wealth programs collect ongoing fees that can be modelled with more visibility than one off transaction income.
"The build out of AGF Capital Partners, including the increased 50% economic interest in New Holland Capital and the multi strategy alternatives platform of approximately $15.7b in AUM and fee earning assets, is designed to shift the mix toward fee related earnings and carried interest that can add to overall earnings and diversify revenue."
What those fee streams ultimately mean for valuation rests on how pressure on profitability and client flows is resolved over the next few years.
If that tension is what you are watching, read the full narrative for AGF Management to see how fee streams, carried interest and capital allocation could be quietly accelerating value.

Curious About Alternative Stock Paths?
Fresh ideas move first. Screens already flag shares building breakout momentum while they stay under the radar for now. Do not get caught watching from the sidelines; consider acting while opportunities are still developing.
- Scan for resilient companies quietly compounding while others hesitate by running the 9 resilient stocks with low risk scores before the crowd starts chasing stability and valuations adjust.
- Target cash rich businesses with room to surprise as sentiment shifts by reviewing the 7 high quality undiscovered gems while they are still flying below most radars.
- Explore long term demand for critical materials by checking the 16 top copper producer stocks before capital rotates and these opportunities move off many investors’ bargain lists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com