


EN
Is Shake Shack (SHAK) Undervalued On Its Earnings Beat And Expansion Push?
Shake Shack (SHAK) is back in focus after third quarter 2026 results, with adjusted earnings topping analyst forecasts, same Shack sales turning positive again, and a record wave of new company operated openings.
At a share price of US$71.89, Shake Shack has enjoyed a 12.03% 1 month share price return and a 2.96% gain over the last day, yet the year to date share price return is still down 13.87% and the 1 year total shareholder return is down 21.10%. The 3 year total shareholder return of 30.64% suggests that the recent earnings beat and steady expansion are being weighed against earlier enthusiasm as investors reassess both growth potential and execution risk.
Scan beyond Shake Shack and look for other consumer stocks with similar momentum or a potential reset in expectations using our hand picked 19 high quality undiscovered gems list.
The share price has rebounded on an earnings beat, while longer term returns still lag. For anyone eyeing Shake Shack here, a key question is whether it makes more sense to step in now or wait for a cleaner entry on valuation grounds.
Most Popular Narrative: 12% Undervalued
On the most followed view of Shake Shack, a fair value of $81.38 sits above the recent $71.89 close, so the current rebound still prices in some doubt about execution.
The focus on urban expansion and faster roll out of both domestic company operated Shacks and international licensed locations, including new formats such as drive thrus and smaller footprints, is being backed by reduced build costs to under US$2 million per unit and over 30% cash on cash returns on recent openings. This can support system wide revenue growth and improving earnings.
See why 15 investors see Shake Shack as 12% undervalued.
Result: Fair Value of $81.38 (UNDERVALUED)
Still, if beef and broader operating costs stay elevated, or heavy spending on marketing and tech fails to lift profitability, the Shake Shack narrative could quickly lose support.
Find out about the key risks to this Shake Shack narrative.
Another Angle On Shake Shack’s Valuation
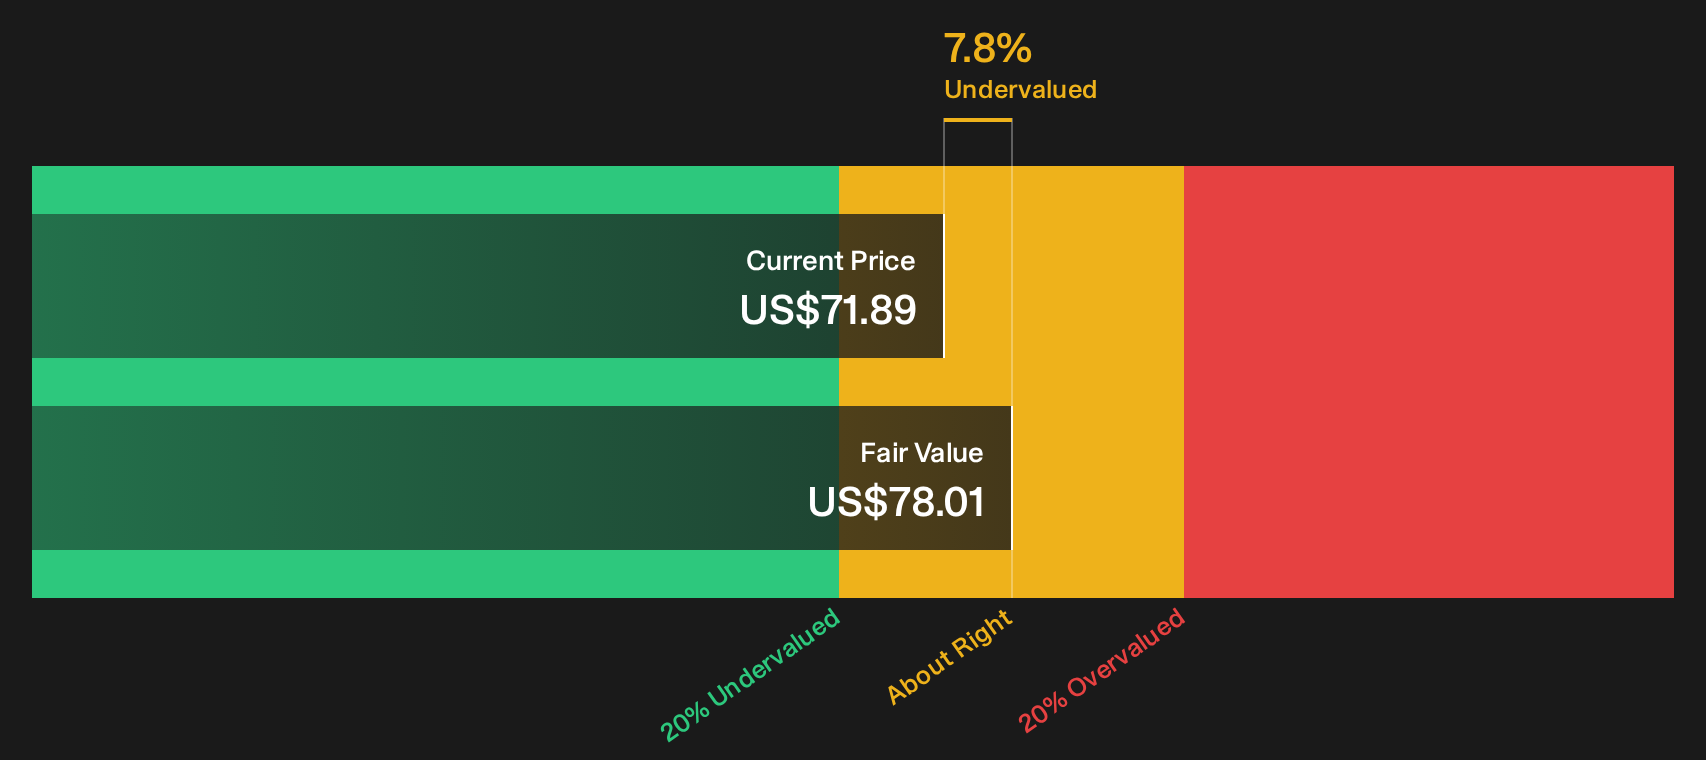
On the cash flow view, Shake Shack screens differently. Our DCF model points to a future cash flow value of about $78.01 per share, which is only modestly above the recent $71.89 price. That is a far tighter gap than the $81.38 fair value. The question is which signal you treat as more important.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Shake Shack is clearly split, with recent data pointing in different directions for value focused investors. Act quickly, review the full picture, and weigh those potential bright spots using the 3 key rewards.
Looking for more investment ideas beyond Shake Shack?
If you stop with Shake Shack, you risk missing other setups that better match your goals, risk tolerance, and timeline for building wealth.
- Spot potential mispricing early by scanning a curated 39 high quality undervalued stocks that filters for quality businesses at discounted valuations.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (24 results) that filters for companies with cleaner finances and sturdier fundamentals.
- Lock in potential income streams by reviewing a 8 dividend fortresses that highlights stocks offering higher yields with a focus on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com