


EN
Did Nine Month Earnings Strength Just Shift DEUTZ Stock's Investment Narrative?
- DEUTZ reported earnings for the nine months ended September 30, 2026, with sales of €1,669.2 million and net income of €39.5 million, compared with €1,500.4 million and €19.9 million a year earlier.
- The more than twofold increase in net profit and the rise in basic earnings per share from €0.14 to €0.26 highlight stronger profitability across DEUTZ's operations.
- Next, the focus shifts to how this step up in nine month earnings power could influence DEUTZ's existing investment narrative and risk balance.
Scan beyond DEUTZ and line up other industrials that pair earnings momentum with solid fundamentals using our hand picked 224 high quality undervalued stocks.
DEUTZ Investment Narrative Recap
For DEUTZ, the core belief is that the shift from traditional engines toward a more diversified mix across Services, Energy, Defense and NewTech can support earnings even when legacy engine demand is soft. The latest nine month figures show higher sales and net income, which supports that transition story but does not change the need for disciplined integration and cost control in the near term.
The key short term swing factor remains how effectively DEUTZ turns its newer divisions into consistent profit pools while engine volumes stay under pressure. Balance sheet risk still matters, with higher leverage and financing costs a live issue. If cash generation lags, that becomes the biggest near term operational risk.
The most relevant context for this earnings release is DEUTZ's ongoing build out of the Energy division. Management previously highlighted €37 million of additional Energy revenue in the first half of 2026 and a €220 million backlog, alongside an internal ambition for materially higher revenue over time. The latest nine month profit picture arrives against that backdrop of heavier investment and scaling efforts.
For you as a shareholder or potential shareholder, the link is straightforward. Progress in Energy gives DEUTZ another lever to offset weak engine demand and support margin mix, and it also ties into the leverage discussion because growth here has leaned on acquisitions. Execution on integration, order conversion and cash collection in this unit will influence how comfortable investors feel with the higher debt load and with treating the recent EPS improvement as repeatable rather than one off.
DEUTZ's current earnings of €78.7 million are set against analyst forecasts for €301.0 million of profit and €4.2 billion of revenue by 2029, which implies revenue growth of 25.1% per year and an earnings increase of roughly 3.8x from today into that 2029 estimate year.
Uncover why DEUTZ's fair value indicates a 70% potential upside to its current price, which could narrow quickly.
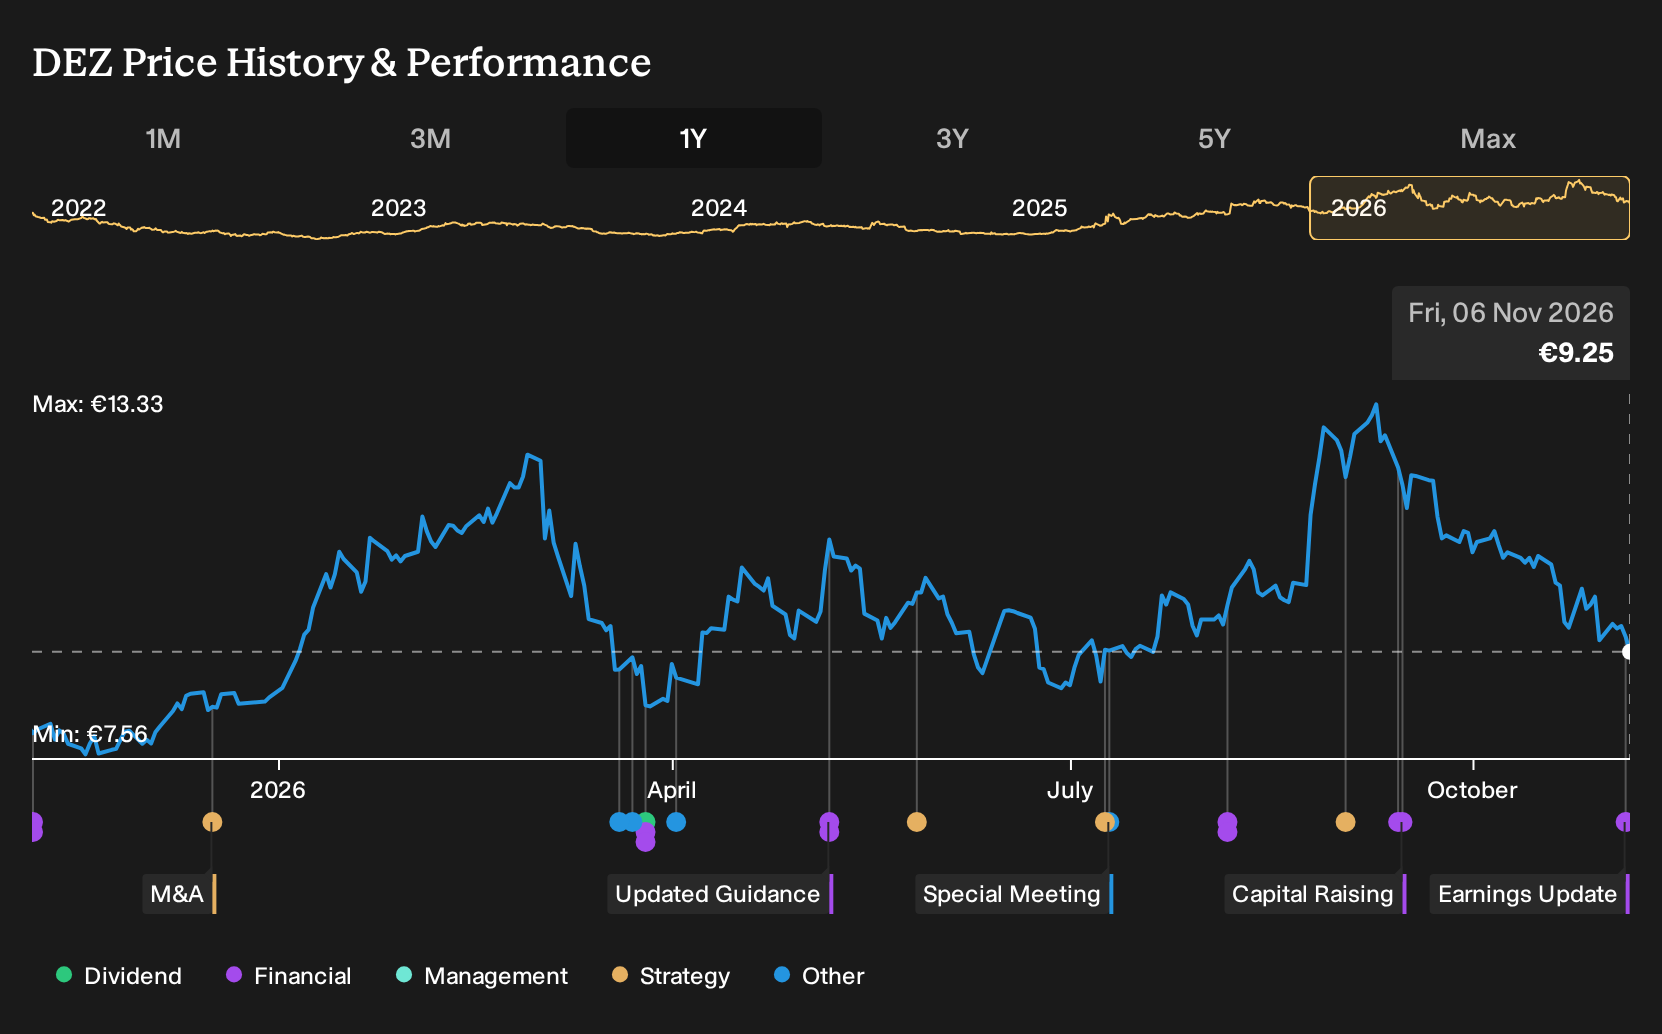
Exploring Other Perspectives
Some of the most bullish analysts frame the FFG acquisition as the big swing factor. Before these nine month earnings, they were modelling revenue of about €5.3b and profit of €572.5 million by 2029, far above the consensus €4.2b and €301.0 million. Your view on DEUTZ could shift as forecasts move after this update.
Explore 5 other DEUTZ fair value estimates, including one that suggests potential upside of as much as 320% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DEUTZ research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DEUTZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DEUTZ's overall financial health at a glance.
Looking for more investment ideas beyond DEUTZ?
Once you have a view on DEUTZ, it can help to compare it with other opportunities that fit different goals, whether that is value, resilience, or income.
- For investors looking for potentially mispriced quality, compare DEUTZ against a broader pool of candidates using the 224 high quality undervalued stocks.
- If capital protection and steadier business profiles matter most to you, focus on companies with stronger financial positions using the list of solid balance sheet and fundamentals (193 results).
- Those who care most about regular cash returns can focus on companies with higher yields by scanning the 232 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com