


EN
What Cytokinetics (CYTK)'s MYQORZO Launch Means For Shareholders
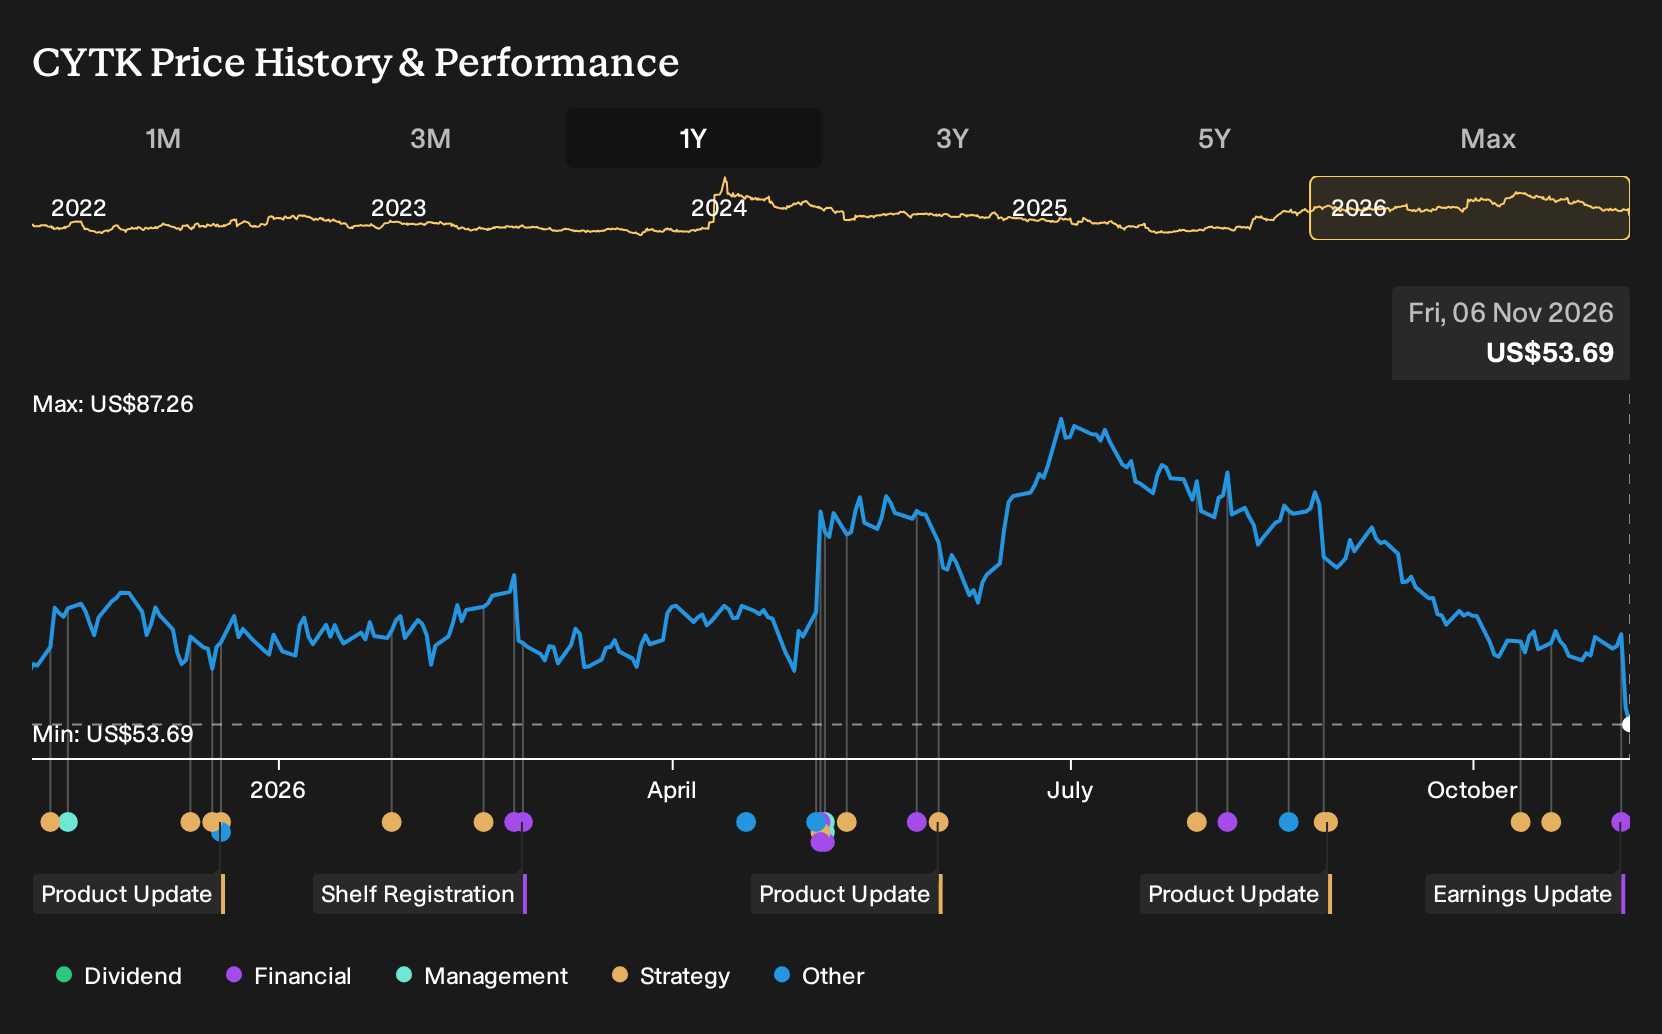
- Cytokinetics reported third quarter 2026 revenue of US$47.56 million compared with US$1.94 million a year earlier, while the quarterly net loss narrowed to US$190.07 million from US$306.18 million, helped by US$44.5 million in MYQORZO net revenue.
- The MYQORZO launch is reshaping Cytokinetics’ profile, with a rapidly expanding prescriber base, rising patient demand, and plans to extend its cardiomyopathy franchise following positive Phase 3 data.
- The potential shift in Cytokinetics’ investment narrative will now be assessed in light of MYQORZO’s rapid launch traction and pipeline momentum.
Cytokinetics Investment Narrative Recap
For Cytokinetics, the core belief is that MYQORZO and aficamten can turn a research heavy heart drug platform into a commercial cardiomyopathy franchise. The latest quarter points in that direction, with MYQORZO contributing US$44.5 million of the US$47.56 million in revenue and the overall loss narrowing. The business is still loss making, so that thesis hinges on execution, not just science.
The most important near term catalyst remains regulatory progress and label expansion for aficamten in hypertrophic cardiomyopathy, alongside continued MYQORZO uptake. The biggest risk is that high operating costs and a concentrated pipeline persist while regulatory decisions or reimbursement processes slow the cardiomyopathy rollout. The third quarter update reinforces those existing swing factors rather than changing them.
The earnings release for the third quarter of 2026 is the clearest operational marker tied to these catalysts. Revenue reached US$47.56 million compared with US$1.94 million a year earlier, helped by MYQORZO, while the quarterly net loss narrowed to US$190.07 million from US$306.18 million. That combination shows the cardiomyopathy franchise starting to matter on the income statement, even as losses stay substantial.
For an investor, this update links directly to the regulatory and commercialization milestones around aficamten and MYQORZO. Progress toward a supplemental NDA in non obstructive HCM, along with continued launch spending, keeps both the opportunity and the funding risk in focus. Execution on label expansion, payer access and cost discipline will shape how long Cytokinetics can absorb losses while trying to scale this cardiomyopathy platform.
Cytokinetics' current analyst narrative points to revenue of US$1.0b and earnings of US$178.9 million by 2029, which implies very large yearly revenue growth of 114.3% and an earnings swing of about US$1.0b from current earnings of a US$829.6 million loss.
Uncover why Cytokinetics' fair value indicates a 101% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Cytokinetics focuses on how quickly MYQORZO could scale in non obstructive HCM. The most optimistic analysts were already pencilling in revenue of about US$1.7b and earnings near US$296.7 million by 2029 before this quarter. You can treat today’s MYQORZO launch data as a fresh test of those higher hopes.
Explore 2 other Cytokinetics fair value estimates, including one that suggests as much as 540% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cytokinetics research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cytokinetics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cytokinetics' overall financial health at a glance.
Looking For More Ideas Beyond Cytokinetics?
If you want to put Cytokinetics in context, it can help to line it up against other companies with different risk and return profiles using the Simply Wall St Screener.
- For investors hunting for potential mispricing, compare Cytokinetics with a wider field of companies screened as 39 high quality undervalued stocks that may offer attractive fundamentals.
- If capital preservation is high on your list, weigh Cytokinetics against a 29 resilient stocks with low risk scores to see which opportunities fit a more cautious approach.
- When balance sheet strength matters most, set Cytokinetics alongside a list of solid balance sheet and fundamentals (24 results) to find businesses with financial structures that suit your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com