


EN
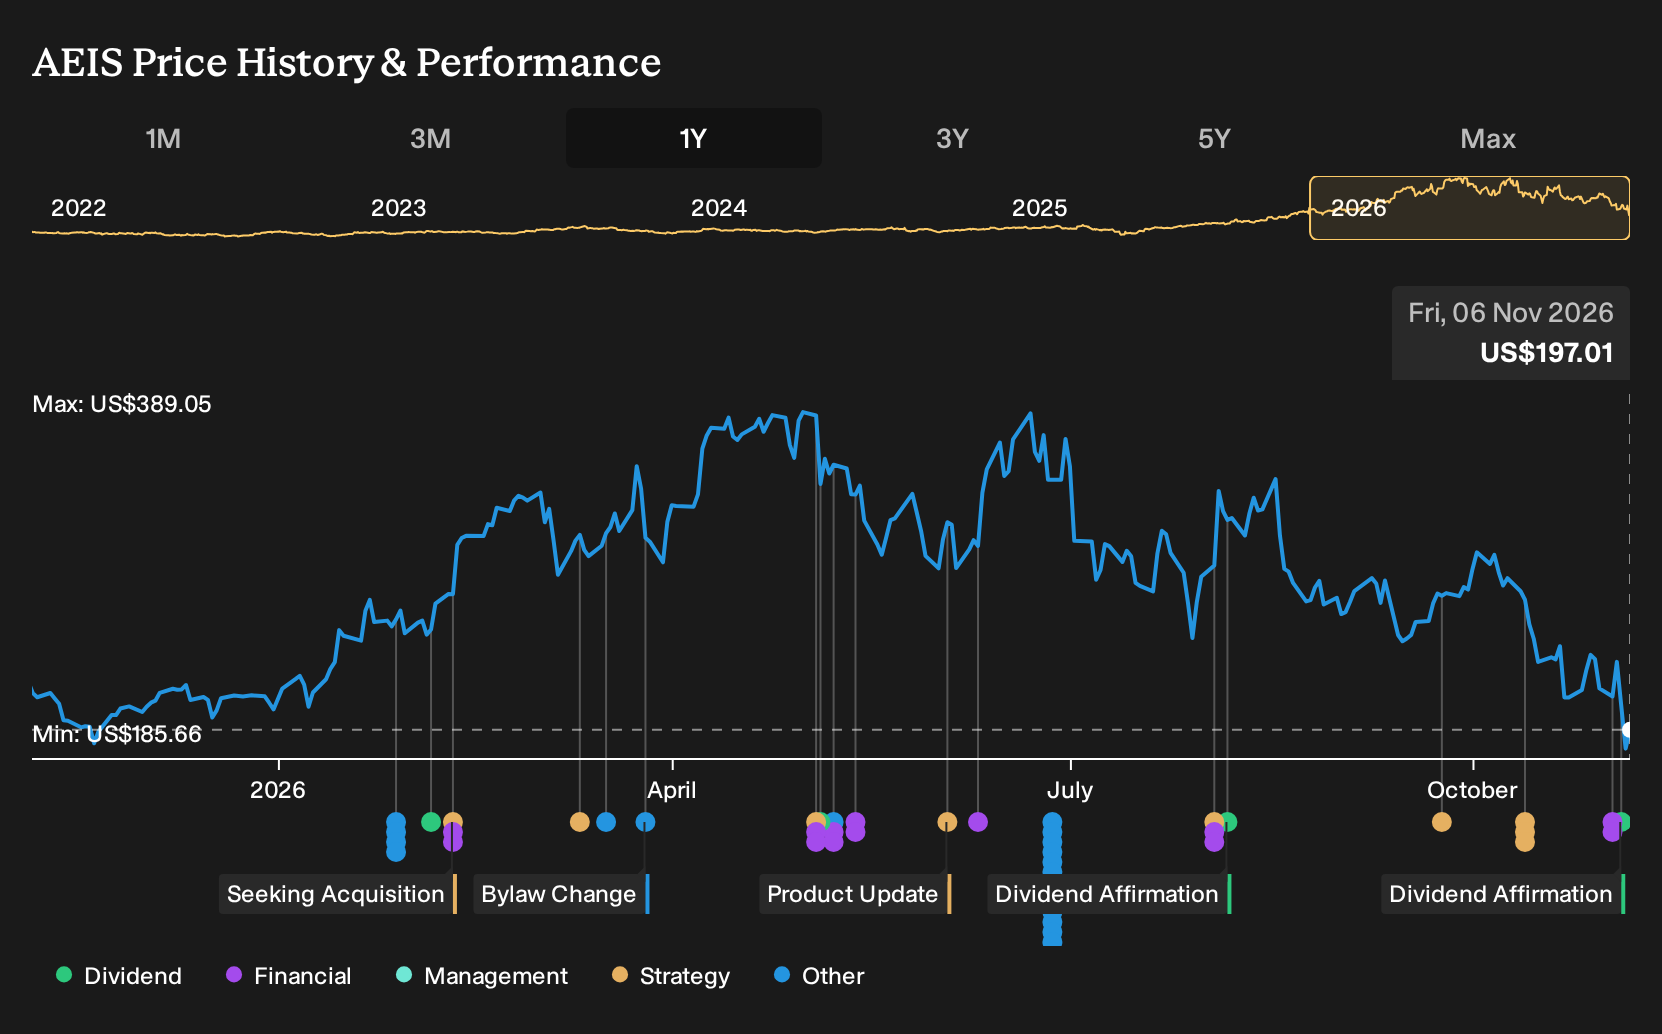
Advanced Energy (AEIS) Is Up 6.1% What's Changed After Strong Earnings Guidance
- Advanced Energy Industries reported third quarter 2026 sales of US$696.4 million and net income of US$115.6 million, alongside board approval of a US$0.10 per share quarterly dividend paid in December 2026.
- The combination of higher earnings per share across both the quarter and year to date, together with revenue guidance of about US$735 million for the fourth quarter, gives investors fresh data on how the business is handling demand across its key end markets.
- We will look at how Advanced Energy Industries' investment narrative aligns with this strong third quarter earnings performance and forward guidance.
Scan handpicked peers showing similar earnings momentum and capital return stories using the 8 dividend fortresses
Advanced Energy Industries Investment Narrative Recap
To own Advanced Energy Industries, you need to be comfortable that demand for AI data centers, semiconductor tools, and high end industrial and medical gear can support the capacity the group is building out. The latest quarter points to solid execution on that thesis, while fourth quarter revenue guidance around US$735 million keeps the near term growth story alive.
The biggest short term swing factor is still how quickly those AI and semiconductor programs convert into sustained orders that fully use new manufacturing capacity. The key risk is overbuilding, given higher CapEx, inventory and the 0% convertible notes, which could weigh on returns and earnings per share if utilisation disappoints.
The most relevant update here is the third quarter 2026 earnings release. Sales of US$696.4 million and net income of US$115.6 million give you a clearer read on how Advanced Energy Industries is turning its product wins into actual profit. Earnings per share from continuing operations above US$2.7 on both a basic and diluted basis underline that point.
For catalysts, that profit base matters because it is intended to support heavy investment into capacity for AI data center and advanced semiconductor platforms. The risk side is just as clear. With sizeable capital commitments and a large convertible note, any slowdown in orders, pricing pressure, or weaker utilisation could quickly pressure margins, free cash flow, and investor confidence in the growth plan.
Advanced Energy Industries' narrative projects US$4.5b revenue and US$1.2b earnings by 2029. This assumes 25.9% yearly revenue growth and an earnings increase of about US$910m from US$290.1m today.
Uncover why Advanced Energy Industries' fair value indicates a 97% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts leaned hard into capacity risk. Before this earnings beat and dividend affirmation, they were only pencilling in about US$4.0b of revenue and US$923.0m of earnings by 2029. That is well below the consensus path, and it shows how far opinions on Advanced Energy Industries can spread. You should expect those views to evolve as fresh results land, and explore a range of scenarios rather than anchoring on a single forecast.
Explore 5 other Advanced Energy Industries fair value estimates, including one that suggests it could be worth just $360.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Advanced Energy Industries research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Advanced Energy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Energy Industries' overall financial health at a glance.
Looking For More Ideas Beyond Advanced Energy Industries?
If the Advanced Energy Industries story has sharpened your thinking on earnings quality, balance sheets, and capital returns, broaden that lens with a wider watchlist built from the Simply Wall St Screener.
- If you care most about finding steady businesses with strong finances, start with a list of solid balance sheet and fundamentals (24 results) as a base for deeper research.
- If your priority is limiting downside risk, focus on a 29 resilient stocks with low risk scores that aims to keep volatility and financial stress in check.
- If you want underfollowed opportunities with room for the story to develop, scan a 19 high quality undiscovered gems that filters for quality fundamentals hiding off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com