


EN
Westrock Coffee (WEST) After Mixed Q3 Results And Refinancing Looks Undervalued
Westrock Coffee (WEST) is back in focus after third quarter earnings on 5 November 2026, with weaker sales and a wider loss per share than forecast, but stronger adjusted EBITDA and a large refinancing deal.
That mixed earnings release and refinancing update has come alongside some sharp price swings, with Westrock Coffee’s share price falling 13.31% on the day and 9.47% over the past week, yet still posting a 120.88% year to date share price return and a 132.30% total shareholder return over one year, which indicates strong longer term momentum despite the recent pullback.
Surf 19 high quality undiscovered gems picked for investors watching Westrock Coffee’s sharp swings and looking for other under the radar stories with improving earnings profiles.Westrock Coffee now trades at a discount to analyst targets and a sizeable gap to some intrinsic value estimates. After a year of strong gains and a fresh pullback, is that caution priced right or misfiring?
Most Popular Narrative: 10% Undervalued
On the most followed valuation view, Westrock Coffee screens about 10% below an implied fair value of $10, compared with a last close of $8.99. That gap rests heavily on how much profit the business can eventually pull out of the capacity and systems it has already built.
Recent investments in advanced extraction and RTD (ready to drink) manufacturing facilities, particularly the Conway plant, are reaching planned production levels with further scaling expected through additional lines (for example, second can and glass lines). This is expected to enable substantial capacity growth and operating leverage, supporting both top-line revenue growth and expanded EBITDA margins as fixed costs are absorbed over higher volumes.
See why 8 investors see Westrock Coffee as 10% undervalued.
Result: Fair Value of $10 (UNDERVALUED)
Still, that 10% discount hinges on big assumptions. A setback with a major customer or prolonged cost and execution issues at Conway could quickly challenge this fair value story.
Find out about the key risks to this Westrock Coffee narrative.
Another View: Westrock Coffee Looks Expensive On Sales
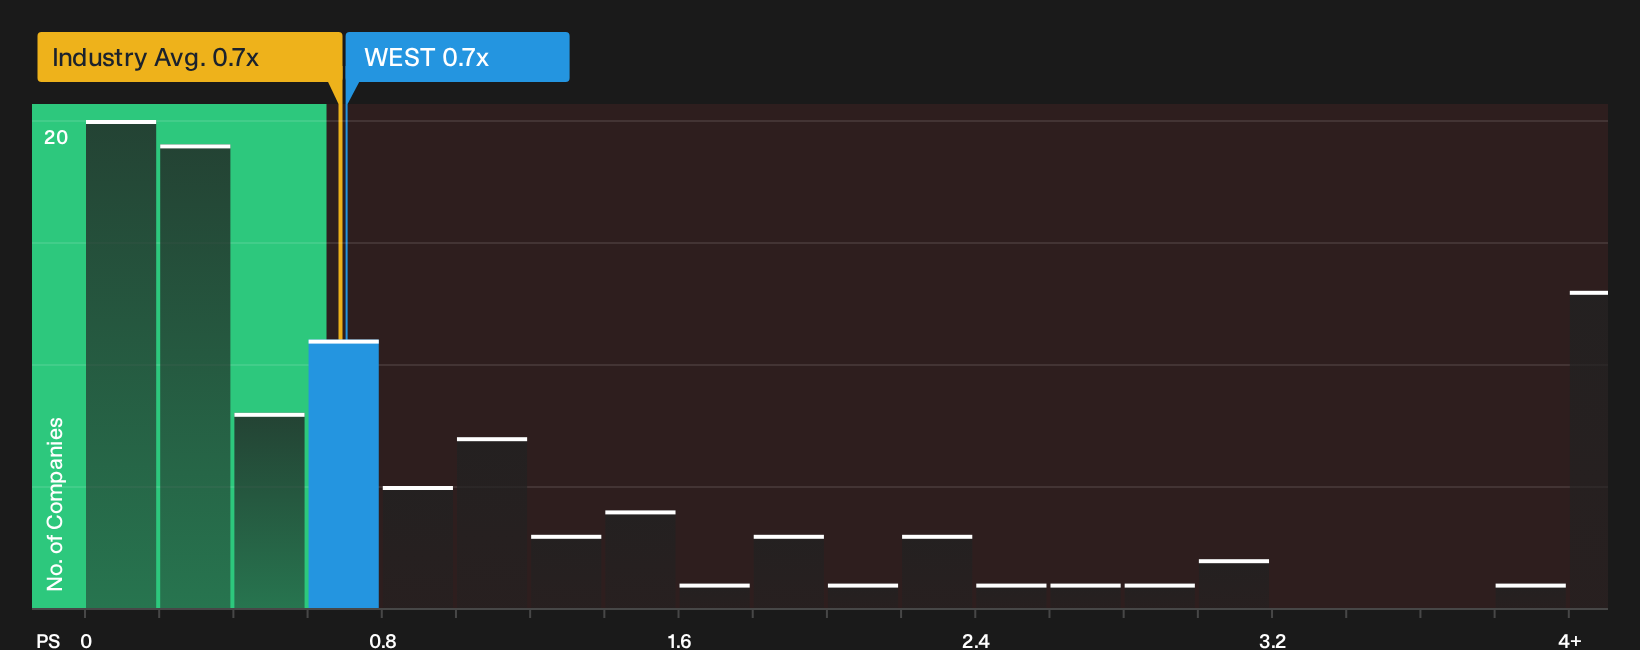
The SWS DCF model points to a large gap between Westrock Coffee's share price of $8.99 and an estimated future cash flow value of $82.83. This screens as heavily undervalued. On a simple P/S lens though, WEST trades at 0.7x versus a 0.6x peer average and a 0.4x fair ratio. The question for investors is how comfortable they are paying a premium on sales while leaning on a very optimistic cash flow curve.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Westrock Coffee can leave the picture feeling blurred, so check the numbers yourself and weigh both sides of the story quickly. To see a concise rundown of the key downside flags alongside the potential upside case, review the 1 key reward and 1 important warning sign.
Looking for more Westrock Coffee investment ideas?
If Westrock Coffee has your attention, do not stop at a single ticker. Spread your research so one story does not quietly dominate your portfolio.
- Target stability first and scan a 29 resilient stocks with low risk scores that can help you focus on companies where volatility and risk scores stay under tighter control.
- Hunt for value gaps by reviewing a 39 high quality undervalued stocks that highlights businesses combining solid fundamentals with prices that lag behind their underlying metrics.
- Prioritise resilience and funding strength by checking a list of solid balance sheet and fundamentals (24 results) so you do not miss companies with healthier financial foundations than Westrock Coffee.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com