


EN
Ovintiv (OVV) Guidance And Buybacks Put Valuation Back In Focus
Ovintiv (OVV) packed several updates into one day, pairing fresh fourth quarter and full year 2026 production guidance with third quarter earnings, a maintained dividend, and progress on its ongoing share repurchase program.
Ovintiv’s share price has retreated over the past week, with a 7 day share price return that declined 16.66%, even as fresh 2026 production guidance, third quarter results, dividend affirmation and buybacks keep the focus on cash returns and capital discipline.
Despite this short term pullback, the stock’s year to date share price return of 49.47% and 1 year total shareholder return of 59.33% indicate momentum has built over a longer horizon. The 3 year and 5 year total shareholder returns of 46.98% and 90.76% provide investors with a wider context for the recent volatility around US$60.52.
Spot similar cash return and production stories to Ovintiv by scanning our handpicked 39 high quality undervalued stocks.Ovintiv now trades at a steep discount to both analyst targets and some intrinsic estimates after that sharp pullback. Is the gap a genuine opportunity, or a warning the market is treating appropriately as risks build in?
Most Popular Narrative: 25% Undervalued
Ovintiv’s most followed valuation story pegs fair value at $80.78 using a 7.24% discount rate, compared with the latest close at $60.52. That gap rests on a detailed view of drilling productivity, inventory depth, and cash returns rather than just a simple multiple.
Expansion of premium drilling inventory, with over 3,200 additional Permian and Montney locations since 2023 that now underpin roughly 15 years of premium Permian inventory and close to 20 years of premium Montney oil inventory, gives Ovintiv more scope to sustain high quality volumes and support revenue and cash flow visibility over a long period.
See why 12 investors see Ovintiv as 25% undervalued.
Result: Fair Value of $80.78 (UNDERVALUED)
Still, the Ovintiv story can change quickly if future acquisitions underdeliver on promised synergies, or if further impairments again drag reported earnings into the red.
Find out about the key risks to this Ovintiv narrative.
Another View: Ovintiv On Earnings Multiples
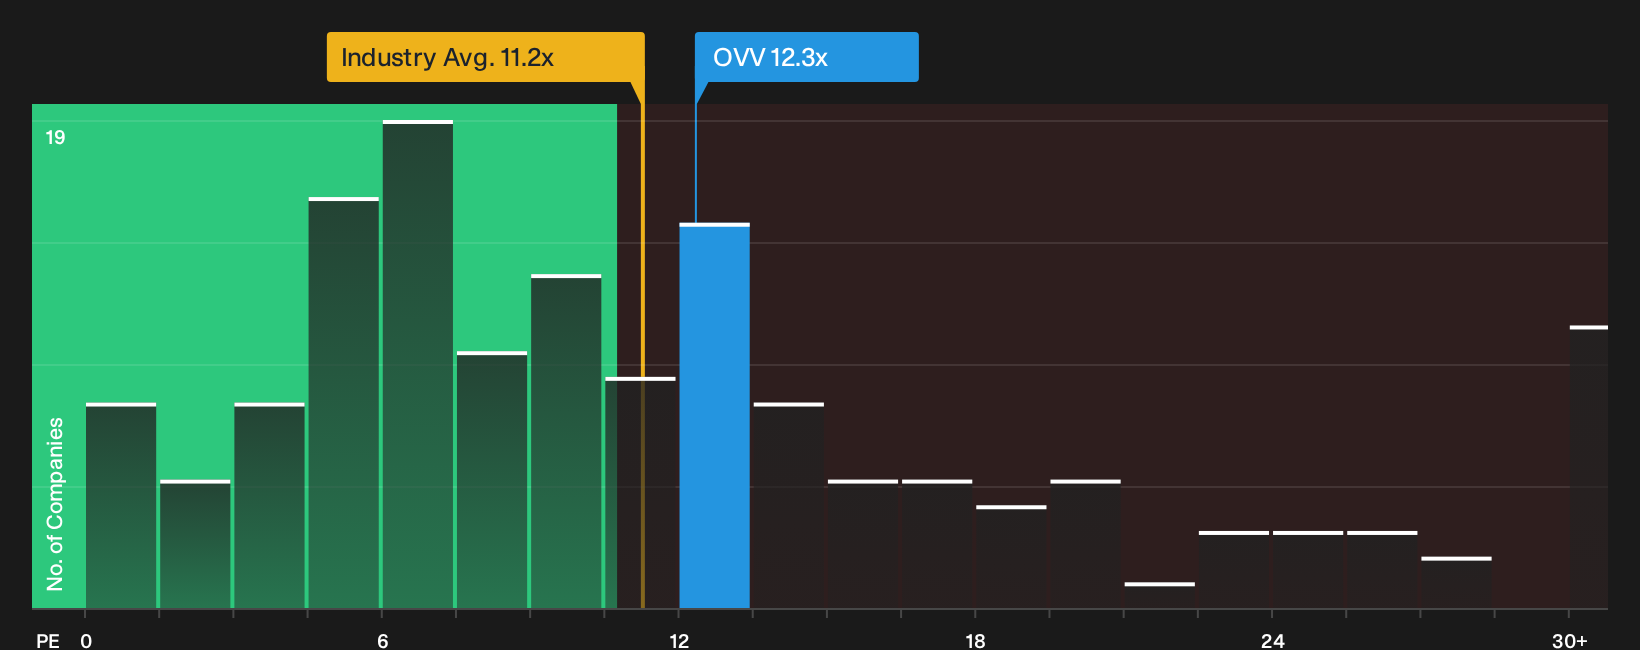
The SWS DCF model lines up with the underpriced story, yet Ovintiv’s P/E of 12.3x tells a different tale. That multiple sits slightly above the US Oil and Gas industry at 11.1x, but below the fair ratio of 19x. Is the market gently pricing in risk, or understating the cash story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the recent Ovintiv headlines or a clear signal? Act on the data, not the mood, and weigh the 4 key rewards and 2 important warning signs.
Ready for more Ovintiv style ideas?
If Ovintiv has sharpened your focus on value, do not stop here. Broaden your watchlist now or you risk missing the next opportunity.
- Target potential mispricings by scanning a curated set of quality candidates through the 19 high quality undiscovered gems.
- Strengthen your downside protection by filtering for companies with resilient finances using the list of solid balance sheet and fundamentals (24 results).
- Build a steadier income stream by reviewing businesses in the 8 dividend fortresses that combine yield with disciplined fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com