


EN
Agnico Eagle Mines (AEM) Posted Strong Q3 Earnings, Is The Stock Now Too Expensive?
Agnico Eagle Mines (AEM) moved back into focus after reporting higher net income and earnings per share for the third quarter of 2026, alongside steady dividends, active buybacks, and sector support from stronger gold prices.
Agnico Eagle Mines has also been busy on the chart, with the share price gaining 15.8% over the past week and 12.4% year to date, while the total shareholder return over three and five years is very large, reflecting reinvested dividends and price gains. Recent earnings, buybacks, and firm gold prices have helped shift sentiment toward stronger momentum, as investors reassess both growth potential and risk after the latest production and cash flow updates.
Spot opportunities alongside Agnico Eagle Mines by reviewing a curated group of 33 elite gold producer stocks that share similar sector drivers and precious metals exposure.Agnico Eagle Mines now screens as a powerful cash generator with a global mine portfolio, yet the share price has sprinted ahead. The real work starts with one issue: Is that quality already fully reflected in today’s valuation?
Most Popular Narrative: 100% Undervalued
Agnico Eagle Mines last closed at $191.57, while the most followed narrative pegs fair value at $123,914, which points to an extremely large perceived gap between price and intrinsic worth in that storyline.
With gold hovering near record highs, a massive structural shift is quietly playing out in the Abitibi greenstone belt that the broader market has completely failed to price in.
If you are holding Agnico Eagle ($AEM) or hunting for the ultimate asymmetric micro-cap play, you need to look at the cold engineering reality currently facing the Canadian Malartic complex, and the tiny junior right next door that holds the key to fixing it: Renforth Resources (CSE: RFR | OTCQB: RFHRF).
See why 35 investors see Agnico Eagle Mines as 100% undervalued.
Result: Fair Value of $123,914 (UNDERVALUED)
Still, this storyline depends on assumptions about undeclared acquisition plans at Agnico Eagle Mines and on future permitting and development timelines at neighboring projects that may not materialize.
Find out about the key risks to this Agnico Eagle Mines narrative.
Another View: DCF Flags Agnico Eagle Mines As Overvalued
The narrative fair value of $123,914 paints Agnico Eagle Mines as extremely cheap. Our DCF model tells a different story. On this view, AEM at $191.57 sits above an estimated future cash flow value of $157.57, which points to an overvalued stock instead.
For investors comparing these two signals, the key question is which set of assumptions feels more realistic for Agnico Eagle Mines over the next decade.
Look into how the SWS DCF model arrives at its fair value.
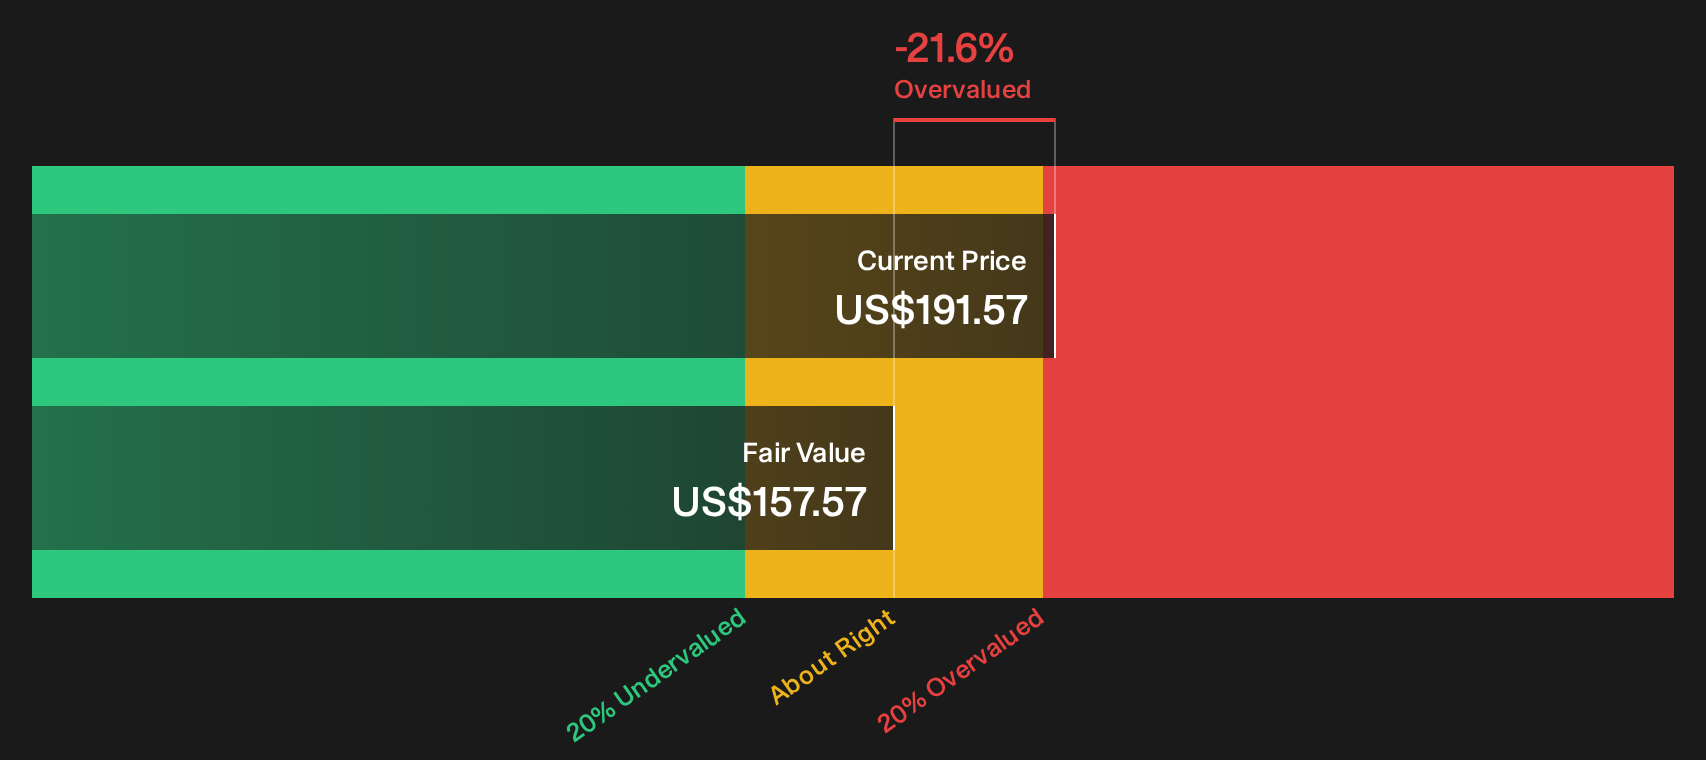
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Agnico Eagle Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Agnico Eagle Mines so far. If you want to move quickly and reach your own verdict, start by weighing its 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Agnico Eagle Mines?
Do not stop with a single ticker. Broader context matters, and the right mix of opportunities can sharpen how you judge Agnico Eagle Mines in your portfolio.
Use the Simply Wall St Screener to compare different angles on quality, value, and resilience before you commit fresh capital or reshuffle existing positions.
- Target potential mispricing by scanning a curated 39 high quality undervalued stocks that combine stronger business quality with prices that lag underlying fundamentals.
- Lock in income potential by reviewing a focused group of 8 dividend fortresses that pair higher yields with consistent cash distribution track records.
- Guard against unwelcome surprises by concentrating on 29 resilient stocks with low risk scores that score better on balance sheet strength and risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com